KreditBee Loan Settlement Percentage: What Borrowers Should Know
The KreditBee loan settlement percentage is the share of your total dues that the loan provider behind KreditBee agrees to accept as a one-time, full and final payment. There is no fixed public percentage. The provider decides case by case, and settlement is only for borrowers genuinely unable to repay.
Mohit Juneja
Reviewed by FREED India, Debt Resolution Specialists
 4.7/5
 ₹3,200Cr+
 20,000+
 20,00,000+4.7/5₹3,200Cr+20,000+20,00,000+
Key Summary

There is no fixed KreditBee loan settlement percentage; the loan provider decides case by case.
KreditBee is an app; your loan comes from an RBI-registered NBFC named in your loan papers.
For app loans, the loan provider must share the recovery agent’s details by SMS or email before contact.
RBI bars loan apps from accessing your contact list, call logs or phone files.
A settled loan shows a “Settled” mark on your credit report for up to 7 years.

App Loans You Can No Longer Repay? Get a Settlement Plan
FREED counsellors look at all your loans first.
Start My Debt AssessmentWhat Is KreditBee Loan Settlement?
KreditBee is a lending app. The loan itself is given by an RBI-registered NBFC (a finance company that lends but is not a bank). Its name appears in your loan agreement and your Key Fact Statement (KFS, the one-page loan summary). KreditBee loan settlement is agreed with that loan provider, so that document is where to start.
Settlement means the loan provider accepts a smaller one-time amount as full and final payment. When a lender accepts less than the full contractual dues under a compromise settlement, the account may be reported as “Settled” rather than “Closed.” These statuses can be interpreted differently by future lenders. Ask for the reporting terms in writing and check your credit report after the settlement is completed.
You can read the wider background in our guide to loan settlement.
Settlement is not something a borrower chooses out of preference. Banks and financial companies only consider it when you are in a genuine financial difficulty and are truly unable to repay the full amount.
It also helps to know what settlement is not. Paying overdue EMIs late, with the extra charges, keeps your loan on track and is a different step altogether. If you can do that, it is usually the cleaner path. KreditBee loan settlement is for the situation where even catching up has become impossible.
So what number can you expect? The KreditBee loan settlement percentage is the question almost everyone searches first, and the next section answers it honestly.
What Is the KreditBee Loan Settlement Percentage?
There is no fixed or published KreditBee loan settlement percentage. Any number you see on a forum or a competitor’s page is someone’s single case, not a rule. The loan provider decides each request on its own facts.
These four things shape the figure:
- Your total outstanding. This is the amount borrowed, plus interest and late charges, and each part is counted.
- Proof of genuine difficulty. A job loss, a medical cost or a pay cut, shown with documents.
- How much you can pay at once. A realistic one-time amount, arranged without taking a new loan.
- The loan provider’s own policy. RBI requires every regulated bank and NBFC to have a board-approved settlement policy, and the decision follows it.
A settlement may reduce the amount a borrower pays compared with the total outstanding dues, but the reduction varies by lender and case. There is no guaranteed KreditBee settlement percentage. The lender decides whether to accept a proposal and what amount and conditions to offer.
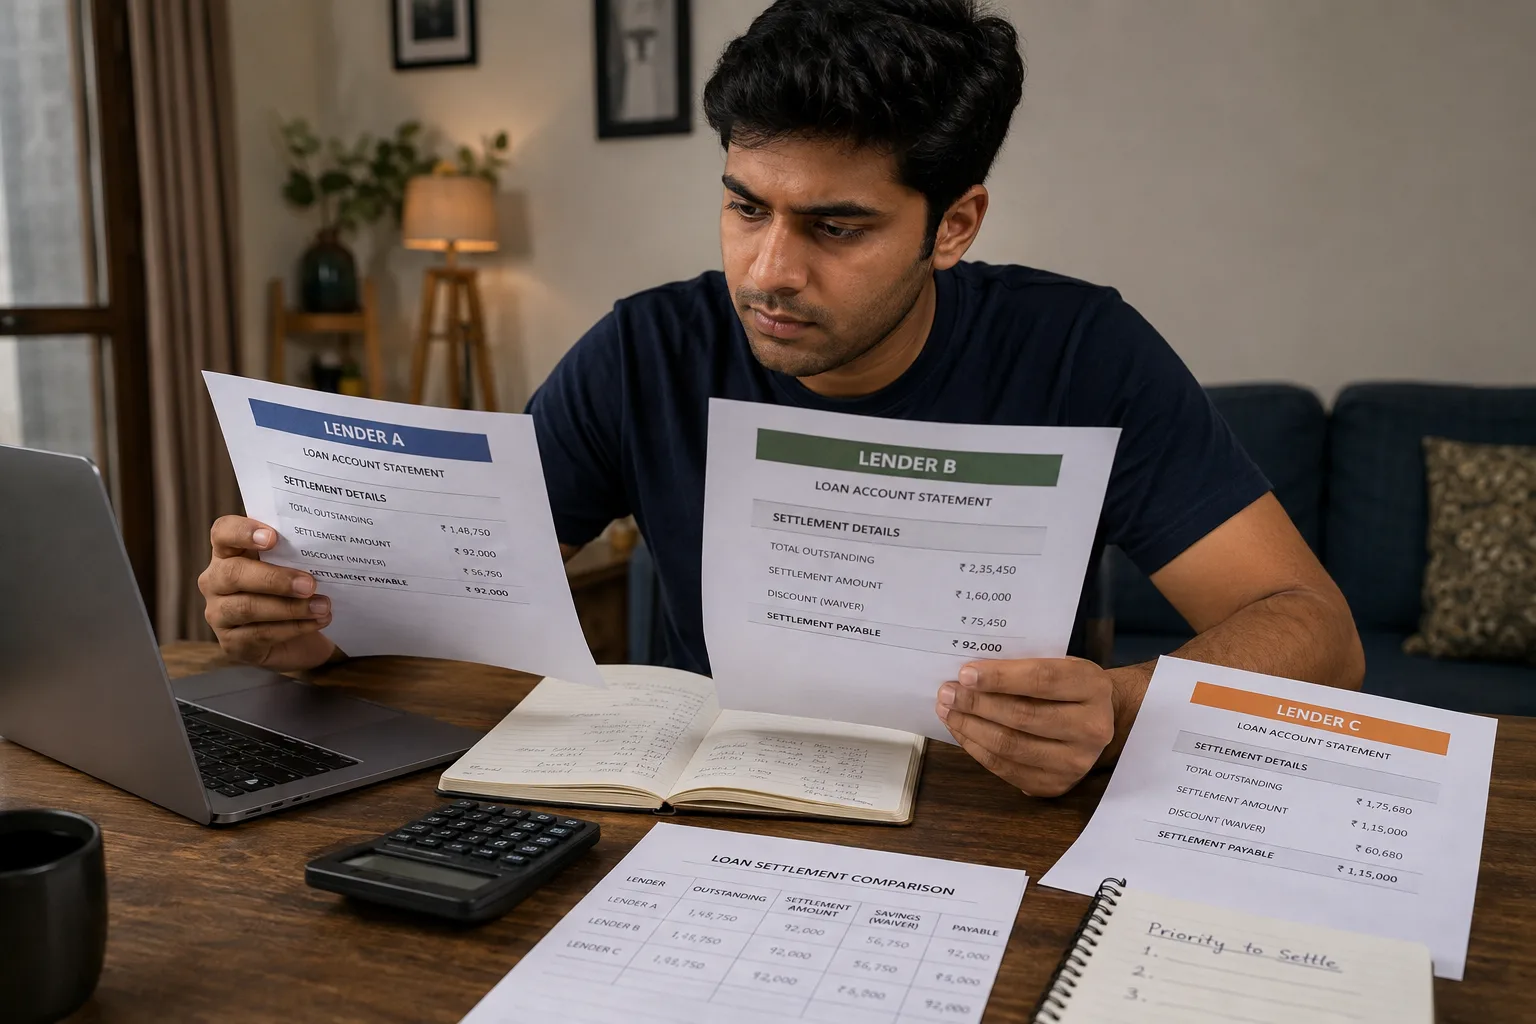
Here is an illustration, and it is only an illustration. Say you owe ₹48,000 across two KreditBee loans, and you can arrange ₹25,000 within 60 days. You offer that amount with your proof. The loan provider may accept it, reject it, or counter with a different figure. You then decide whether the counter-offer is something you can honestly pay.
What you should not do is bargain on guesses. Our guide on the typical personal loan settlement percentage explains how ranges work in general, and what a settlement amount is made of.
Treat any quoted KreditBee loan settlement percentage as a starting question, not an answer. The same goes for any screenshot that claims to show a standard KreditBee loan settlement percentage: it shows one borrower’s outcome on one day.
Rates and ranges shown are indicative. Final terms decided by the bank. FREED is not a Loan Provider. No outcome is guaranteed. Please verify directly with your bank.
Why Do KreditBee Loans Become Hard to Repay?
A ₹15,000 loan came through for the month’s rent. When the first EMI fell due, you took a second app loan to cover it. Then a salary arrived late, and both EMIs slipped in the same week.
This is how it usually goes. App loans tend to have short repayment periods, so the EMI arrives quickly. Fees and interest on small amounts add up faster than people expect. And borrowing from one app to repay another stacks the loans on top of each other, so each month’s payment is bigger than the last.
The small size of each loan hides the total. Three loans of ₹10,000 feel manageable one at a time, but together they can take a large share of a monthly salary.
None of this is a character flaw. It is what a rough patch looks like when money is tight and the only quick option is another app. Many careful people end up here after a late salary, a medical cost or a job change.
This blog does not make claims about KreditBee’s own rates or charges. Your loan agreement and statement list the exact fees, and reading them closely is the first step toward knowing where you stand. If you feel the loans are feeding on each other, our piece on escaping a loan trap explains how the cycle works and how it breaks.
When Should You Think About Settling a KreditBee Loan?
Settlement is meant for one situation: full repayment is no longer possible. Check your month against these signs.
- Your EMIs have slipped for a few months. One late payment is a timing problem. A string of them is a pattern.
- You are taking new app loans to repay old ones. The loans have started paying each other, and the total keeps rising.
- Your EMIs take more than 50% of your take-home pay. At that level, little is left for rent, food and school fees.
- You are skipping essentials. Medicines postponed, meals trimmed, and the EMIs still not covered.
- Your income has dropped with no clear return soon. Job loss, a medical cost, or a business that has slowed.
Now the other side. If you can still pay, even slowly, ask the loan provider for more time, or look at consolidation, where one new loan pays off several. If you can afford repayment under revised terms, ask the lender whether an extension or restructuring is available. Consolidation may also be an option if you qualify for a suitable loan, but compare the interest rate, fees, tenure and total repayment cost before deciding. Neither option guarantees a particular credit score outcome.
If a few of the signs above describe your month, a KreditBee loan settlement percentage becomes worth asking about, and you can use the steps below. If only one or two do, a conversation with a counsellor may be a better first step than a settlement request.
How to Request a KreditBee Loan Settlement, Step by Step
Here is how to ask for a KreditBee loan settlement percentage that fits your situation, in writing, with a record at every step.
- Find the loan provider’s name. Check the KFS, the loan agreement or the sanction SMS.
- Download your loan statement. Note the amount borrowed, interest and late fees separately.
- Work out one amount you can pay. A one-time figure you can arrange without a new loan.
- Write to the loan provider’s grievance or collections email. Use the contact details in the app or on the provider’s website.
- Attach proof of difficulty. Salary slips, a job loss letter or medical bills.
- Wait for a written offer. It should say “full and final settlement.”
- Pay only through official channels. The app or the loan provider’s account, never an agent’s UPI ID.
- Save the settlement letter and the NOC (no objection certificate, the clearance letter). Check your credit report after a couple of months.
The written letter is the only proof that counts. A phone promise disappears the moment the call ends, but a letter on the provider’s official email or letterhead can be shown to anyone who asks later.
If you want help with wording, here is how to write a settlement letter, and what a good reply from the loan provider should include.

FREED Expert Tip
Pay only after the letter names the loan provider, your loan ID, the exact amount and “full and final settlement.”
Book My Free CallWhat Recovery Rules Protect KreditBee Borrowers?
While you work on a settlement, these rules protect you. Some come from RBI’s Digital Lending Directions for app loans, and some from its general recovery-conduct circular.
- Agent details come first. The loan provider must send you the recovery agent’s details by SMS or email before the agent contacts you.
- Apps cannot read your phone. Loan apps must not access your contact list, call logs or phone files.
- The provider stays responsible. The bank or NBFC remains responsible for the partners and agents it uses.
- No shaming. Intimidation, threats, public humiliation and calls to shame your family and friends are not allowed.
- Calling hours. Recovery calls are allowed only between 8 a.m. and 7 p.m.
- New rules from 1 January 2027. From that date, NBFCs must publish their recovery agency list, agents must show ID and hold an IIBF (Indian Institute of Banking and Finance) certificate, and visits too are limited to 8 a.m. to 7 p.m. These are not in force yet.
If a KreditBee recovery agent or any other caller crosses the line, note the date, time and number of each call, and complain to the loan provider’s grievance officer first. FREED Shield is open to everyone who faces abusive recovery calls.
Our guide on app loan harassment covers this in more detail, and so does the one on recovery agent rights.
How Does KreditBee Loan Settlement Affect Your CIBIL Score?
Your score drops, and the loan shows “Settled,” not “Closed.” That is the plain answer.
The “Settled” mark can stay on your report for up to 7 years. A settlement can negatively affect your credit profile, but the size of any CIBIL score change varies by borrower. Future lenders may also view a “Settled” status less favourably than an account reported as fully repaid and closed.
New loans may be harder or costlier for a while. And under RBI’s 2023 framework, there is a gap of at least 12 months before the same loan provider can lend to you again.
Here is a contrast worth knowing, and it is only a fact. An unpaid app loan keeps adding missed-payment marks to your report every month. A settled one stops adding new ones. That does not make settlement painless, but it explains why many people see it as the step that ends the damage getting worse.
Recovery is slow but real. On-time payments on your other loans, low card use and a steady record rebuild the score over time. Our guide on the Settled mark explains how it appears, and this one covers how to rebuild your CIBIL score after a default.
However the KreditBee loan settlement percentage works out, check your report after a couple of months using Credit Insights, and confirm the account shows “Settled” with the right amount.

What the Law Says
After a compromise settlement, RBI rules set at least 12 months before the same bank or NBFC can lend to you again.
Check My Credit InsightsWhat Are Your Options Before Settling a KreditBee Loan?
Think of three steps on a ladder, and start at the lowest one that fits.
- Ask the loan provider for more time or a changed repayment schedule. This keeps your record cleanest.
- Take a Loan Consolidation Plan if you are still paying several app loans and cards. One new loan pays them off, and you pay one lower EMI. Your CIBIL score is not hurt and starts improving over time. FREED’s Loan Consolidation Plan is built for this.
- Use settlement only when full repayment is genuinely impossible. It is the last step, not the first.
Your Options Compared
| More Time / New Schedule | Loan Consolidation Plan | KreditBee Loan Settlement | |
|---|---|---|---|
| Who it suits | Short cash gap | Still paying, several app loans or cards | Genuinely unable to repay in full |
| What you pay | Full amount, later | Full amount, one lower EMI | Reduced one-time amount (up to 50%* less) |
| CIBIL effect | Limited if kept | Score can improve | “Settled” mark for up to 7 years |
| Decided by | Your loan provider | Lending partner after FREED’s matching | Your loan provider |
| With FREED | Not applicable | FREED matches you and gets it done | FREED negotiates once your savings fund is ready |
Rates and ranges shown are indicative. Final terms decided by the bank. FREED is not a Loan Provider. No outcome is guaranteed. Please verify directly with your bank.
Read across a row to see what each route asks of you and what it leaves on your record. The lowest amount in rupees is not always the lightest on your credit report, so compare both before choosing.
Before you decide, use the calculator below to test a KreditBee loan settlement percentage against your total dues.
Are You in a Loan Trap? Quick Check
Move the slider to your total EMIs as a % of monthly salary. See your debt stress level instantly.
EMIs as % of Monthly Salary
How FREED Helps If App Loans Like KreditBee Have Become Unpayable
Many readers hold a KreditBee loan along with other app loans and cards, and writing to each provider separately feels like too much. The FREED Loan Settlement Plan, also called “Settle My Loans,” is built for that.
FREED first looks at your full picture: your app loans, cards, income and essential costs. Then it builds a personalised plan. You save a fixed monthly amount into a separate account held in your own name by an independent trustee. Once enough is saved, FREED talks to each loan provider on your behalf.
You stay in control. You approve or decline every offer. When you approve one, the payment goes to the loan provider, and you receive a settlement letter.
The fee is success-based and is charged only when a settlement is done. The process takes time and is not an overnight fix. It covers app loans, personal loans, cards and BNPL, and it does not cover secured loans. See the Loan Settlement Plan for details.
If recovery calls turn abusive in the meantime, FREED Shield is available to everyone, whether or not you join the plan. For anyone weighing a KreditBee loan settlement percentage alongside other app loans, this is the part FREED takes off your plate: the back-and-forth, the paperwork, and the wording of each letter.
FREED has settled 20,000+ accounts, counselled 20,00,000+ customers and managed ₹3,200 Cr+ debt. Rates and ranges shown are indicative. Final terms decided by the bank. FREED is not a Loan Provider. No outcome is guaranteed. Please verify directly with your bank.
Let FREED Handle the Loan Provider Conversations on Your App Loans
A personalised settlement plan built around your income.
Start My Debt AssessmentTips for a Smoother KreditBee Loan Settlement
- Keep every request in writing. A phone call opens the matter, and an email proves it happened.
- Pay only in the app or to the loan provider’s account. Never to a personal UPI ID, whoever asks.
- Don’t take a new app loan to fund the settlement. It only moves the problem to a new provider, usually at a worse rate.
- Save screenshots of every offer and reply. Date and time visible, in one folder.
- Check your credit report after settlement. Confirm the account shows “Settled” and the amount is right.
- Remove extra app permissions, then uninstall once you are settled. Keep the settlement letter safe first.
Think about the order, too. First get the facts from your statement, then decide the amount, then write. Doing it in that order stops you from agreeing to a figure on a call that you cannot actually pay.
One honest plan, put in writing, is often the first real step out. If you also want a simple way to keep track, see how to keep a record of every call and message. Whether you negotiate the KreditBee loan settlement percentage yourself or with help, the same habits protect you.
Sourcing and Verification
| Claim | Source |
|---|---|
| Agent details before contact (8(v)); apps can’t access contacts, call logs, files (12(i)); provider liable for partners (5(vii)) | RBI Digital Lending Directions, 2025 |
| No intimidation or public humiliation; calls 8 a.m. to 7 p.m.; applies to NBFCs | RBI/2022-23/108 |
| Board-approved settlement policy; 12-month gap before fresh lending | RBI/2023-24/40 |
| NBFCs from 1 Jan 2027: agency list, ID, IIBF, 8 a.m. to 7 p.m. calls and visits | RBI/2026-27/230 |

Mohit Juneja
Mohit Juneja writes educational content at FREED on debt management, credit scores, loan repayment, and borrowing best practices. His content is shaped by expert insights and industry knowledge, helping readers better understand their financial options and make informed decisions.
mohit.juneja@freed.care

FREED is India's trusted loan management platform. Founded in 2020 and headquartered in Gurugram, FREED has counselled 20 lakh+ people on personal loans, credit cards, and app loans. FREED charges fees only on successful settlement, not upfront. FREED does not handle secured loans (home loans, car loans, gold loans).
Media Mentions