Let’s talk
about Loans

Times Of India
Money Control
Economic Times
LiveMint
Financial Times
CNBC
Business Standard
Forbes
Times Of India
Money Control
Economic Times
LiveMint
Financial Times
CNBC
Business Standard
Forbes

75,000+

Customers served

₹450 Cr+

Total savings

4.8/5

Google rating

Indian man comparing two credit cards for a balance transfer decision
By Mohit Juneja | 13 November 2026

One Card Is Not Your Only Debt? When a Balance Transfer Credit Card Helps

A balance transfer credit card can lower the interest on one card. When you also have loans and other cards, it fixes only part of the problem. This guide shows how to judge the full picture.

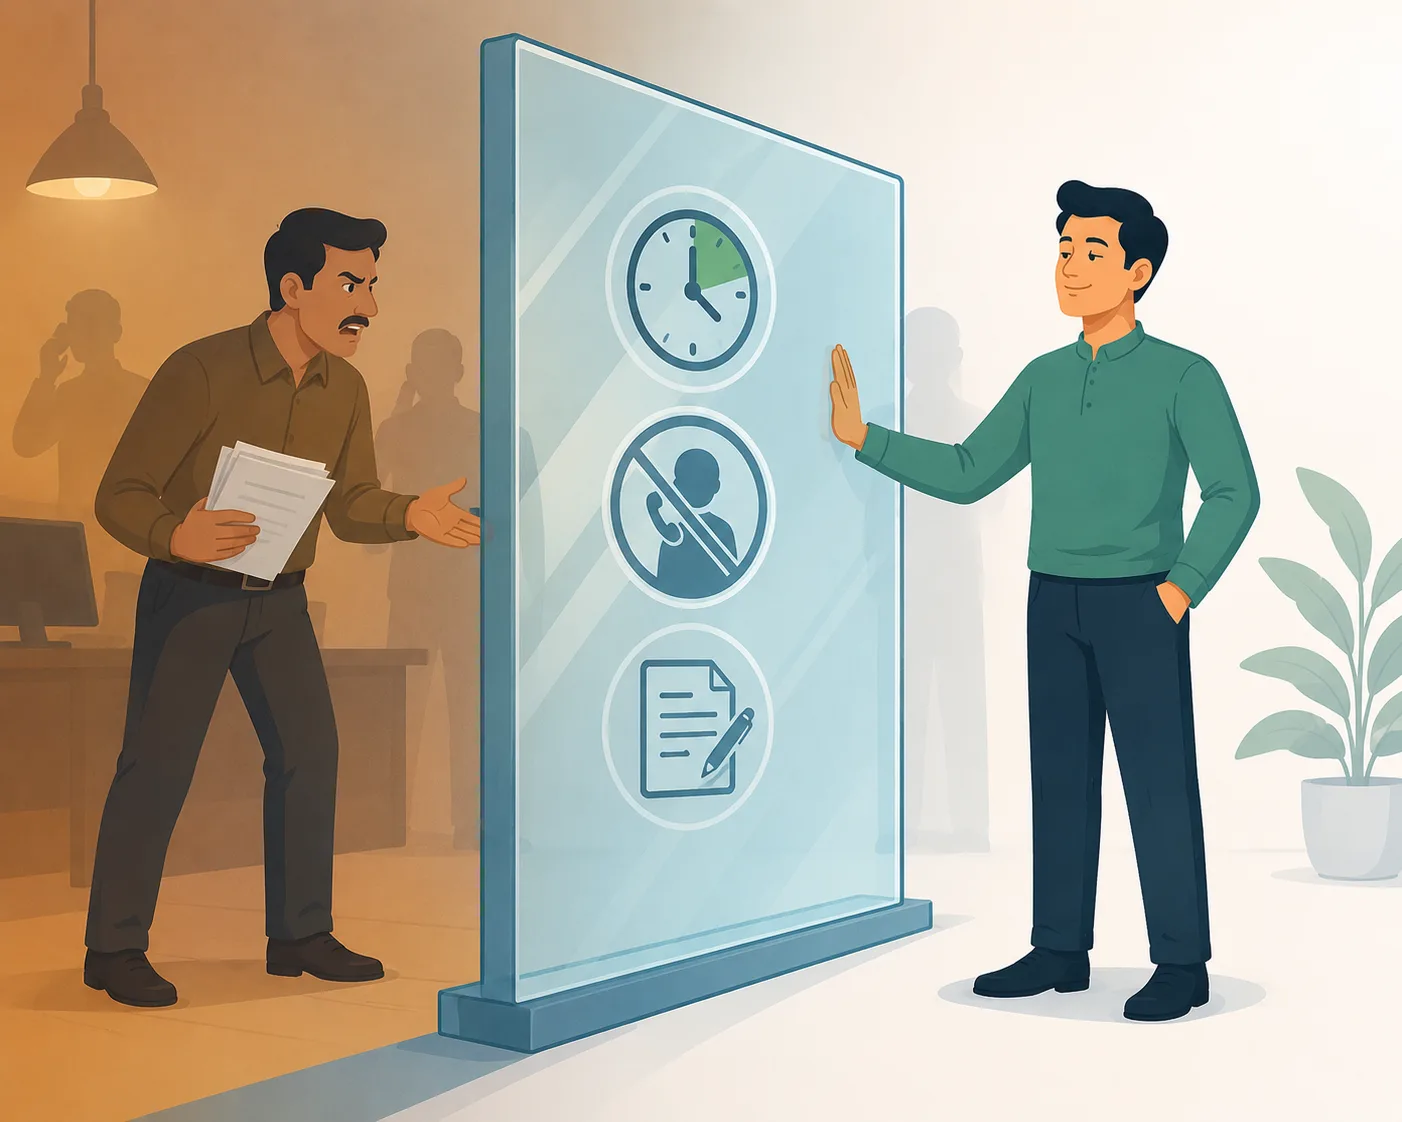
A borrower calmly holding up a boundary against an aggressive recovery agent, with a shield showing RBI protection rules — contact hour limits, no harassment, and written notice rights for loan defaulters in India
By Mohit Juneja | 13 November 2026

When Does Loan Recovery Start, and What Changes From 1 January 2027 Under RBI Guidelines?

When does the loan recovery process start, and what changes from 1 January 2027? This guide explains the start of recovery, the current RBI rules, and the new conduct rules lenders must follow next year.

Indian person reviewing PNB credit card settlement documents at home
By Mohit Juneja | 13 November 2026

Why Do PNB Credit Card Accounts Reach the OTS Stage? Signs and Settlement Steps

PNB credit card settlement (OTS) happens when Punjab National Bank agrees to accept a reduced lump sum, less than your full outstanding, to close a credit card account that has turned into an NPA (a loan marked as bad by the bank). PNB is a public sector bank. That means a Board-approved settlement policy governs the process, though your specific terms still come down to the bank's own assessment of your case.

Indian man reading about one time settlement scheme Central Bank of India on a phone
By Mohit Juneja | 13 November 2026

What Helps During a Settlement With Central Bank of India? One Time Settlement Scheme Guide

One time settlement scheme Central Bank of India is not one fixed offer. The bank can settle a loan you cannot repay for less than the full amount, under its own board-approved policy. Some schemes run only for set dates and loan types. The bank decides. You cannot demand a settlement.

Latest Articles

Indian man comparing two credit cards for a balance transfer decision
By Mohit Juneja | 13 November 2026

One Card Is Not Your Only Debt? When a Balance Transfer Credit Card Helps

A balance transfer credit card can lower the interest on one card. When you also have loans and other cards, it fixes only part of the problem. This guide shows how to judge the full picture.

A borrower calmly holding up a boundary against an aggressive recovery agent, with a shield showing RBI protection rules — contact hour limits, no harassment, and written notice rights for loan defaulters in India
By Mohit Juneja | 13 November 2026

When Does Loan Recovery Start, and What Changes From 1 January 2027 Under RBI Guidelines?

When does the loan recovery process start, and what changes from 1 January 2027? This guide explains the start of recovery, the current RBI rules, and the new conduct rules lenders must follow next year.

Indian person reviewing PNB credit card settlement documents at home
By Mohit Juneja | 13 November 2026

Why Do PNB Credit Card Accounts Reach the OTS Stage? Signs and Settlement Steps

PNB credit card settlement (OTS) happens when Punjab National Bank agrees to accept a reduced lump sum, less than your full outstanding, to close a credit card account that has turned into an NPA (a loan marked as bad by the bank). PNB is a public sector bank. That means a Board-approved settlement policy governs the process, though your specific terms still come down to the bank's own assessment of your case.

Indian man reading about one time settlement scheme Central Bank of India on a phone
By Mohit Juneja | 13 November 2026

What Helps During a Settlement With Central Bank of India? One Time Settlement Scheme Guide

One time settlement scheme Central Bank of India is not one fixed offer. The bank can settle a loan you cannot repay for less than the full amount, under its own board-approved policy. Some schemes run only for set dates and loan types. The bank decides. You cannot demand a settlement.

indian-bank-officer-reviewing-property-documents.webp
By Mohit Juneja | 13 November 2026

Can a Cooperative Bank Use SARFAESI 13(4)? What It Means for Borrowers

Yes, cooperative banks can invoke Section 13(4) of the SARFAESI Act. A five-judge Constitution Bench of the Supreme Court settled this in 2020, after years of conflicting High Court decisions had left the question genuinely unclear. If you took a loan from a cooperative bank and assumed SARFAESI didn't apply to you, this piece explains why that assumption doesn't hold.

SARFAESI Rule 8(6) sale notice being reviewed by a borrower
By Mohit Juneja | 13 November 2026

Why "As Is Where Is" Does Not Excuse Hiding Problems: Rule 8(6) SARFAESI and What It Means for Borrowers

Rule 8(6) requires the authorised officer to provide a 30-day sale notice containing specified details and any other information considered material for a purchaser to assess the nature and value of the property. Courts have interpreted this requirement to include relevant encumbrances in appropriate circumstances. Courts have made clear that the standard "as is where is" disclaimer doesn't let a bank hide a known problem with the asset.

Illustration of a stressed man sitting at a desk with papers, phone, and notebook, looking worried while thinking, representing financial pressure or work overload in a modern office setting.
By Mohit Juneja | 13 November 2026

Why People End Up Settling Their Kotak Credit Card, and When to Consider It

What Is Kotak Credit Card Settlement? A Kotak credit card settlement (also called OTS, or one-time settlement) is when Kotak Mahindra Bank agrees to accept a reduced lump sum as the final payment on your overdue card account. It is the option people turn to when repaying the full outstanding has become genuinely impossible. The account is typically reported as "Settled" in your credit history.

Indian borrower checking SARFAESI Section 31 exemption eligibility for their secured property
By Mohit Juneja | 13 November 2026

What Section 31 Actually Does: The Full Exemptions List Under the SARFAESI Act

Section 31 of the SARFAESI Act lists specific situations the Act's enforcement powers simply don't reach. Traditional security arrangements, very small debts, agricultural land, and, less commonly known, cases where the borrower has already repaid most of what's owed. Knowing this full list matters. One of these exemptions might apply to your situation even if you've never heard of it before.

Make smarter
financial decisions

Get Started

Join over 100,000+ users making smarter moves.