Let’s talk
about Loans







75,000+
Customers served

₹450 Cr+
Total savings

4.8/5
Google rating
Browse Topics
5 CategoriesLoan Settlement
SARFAESI Act: Meaning, Applicability & Effects on Borrowers
The SARFAESI Act (Securitisation and Reconstruction of Financial Assets and Enforcement of Security Interest Act, 2002) lets banks and notified NBFCs take and sell the property pledged against a loan, without going to court first. It applies once the account is an NPA. It never applies to unsecured loans such as credit cards.
IDBI Bank One-Time Settlement: Eligibility & Process
IDBI Bank does something most Indian banks don't bother with. It publishes an actual settlement scheme, by name, with dates and eligibility ranges attached, called Sugam Rinn Bhugtan Yojana. Most borrowers calling their branch about a defaulted loan have no idea this exists, so they end up negotiating blind against terms they never knew were published somewhere.
Bajaj Finserv Loan Settlement: What Borrowers Need to Know
Settlement is not something a borrower chooses out of preference. Bajaj Finserv, like every lender, only considers it when you are in genuine financial difficulty and are truly unable to repay the full amount. This page is for people who know which Bajaj Finserv product they're stuck with, a personal loan, a business loan, the Insta EMI Card or a consumer durable loan, and want to know how settlement works for that product. FREED is not affiliated with Bajaj Finance or Bajaj Finserv.
Axis Bank Personal Loan Settlement: Process & What to Expect
Axis Bank may agree to settle your personal loan, generally where you're genuinely unable to repay in full. Not the full amount. Less. You stop paying EMIs, save a fixed amount each month into a separate account, and after several months or a year, present that accumulated amount as a settlement offer. Axis Bank isn't obligated to accept, but under RBI guidelines, banks must follow a board-approved settlement policy and can't reject an eligible case for reasons outside that policy. If accepted, the account gets marked "Settled" on your report once the agreed amount is paid and the lender confirms it in writing.
How to Settle a Personal Loan When You Have More Than One
To settle a personal loan, you negotiate with your bank or NBFC to accept a reduced lump sum as full and final payment instead of the full outstanding amount. When you have more than one personal loan, this same process repeats separately for each one, in an order that protects you the most.
Borrowed From Multiple Unsecured Lenders? How to Settle All at Once
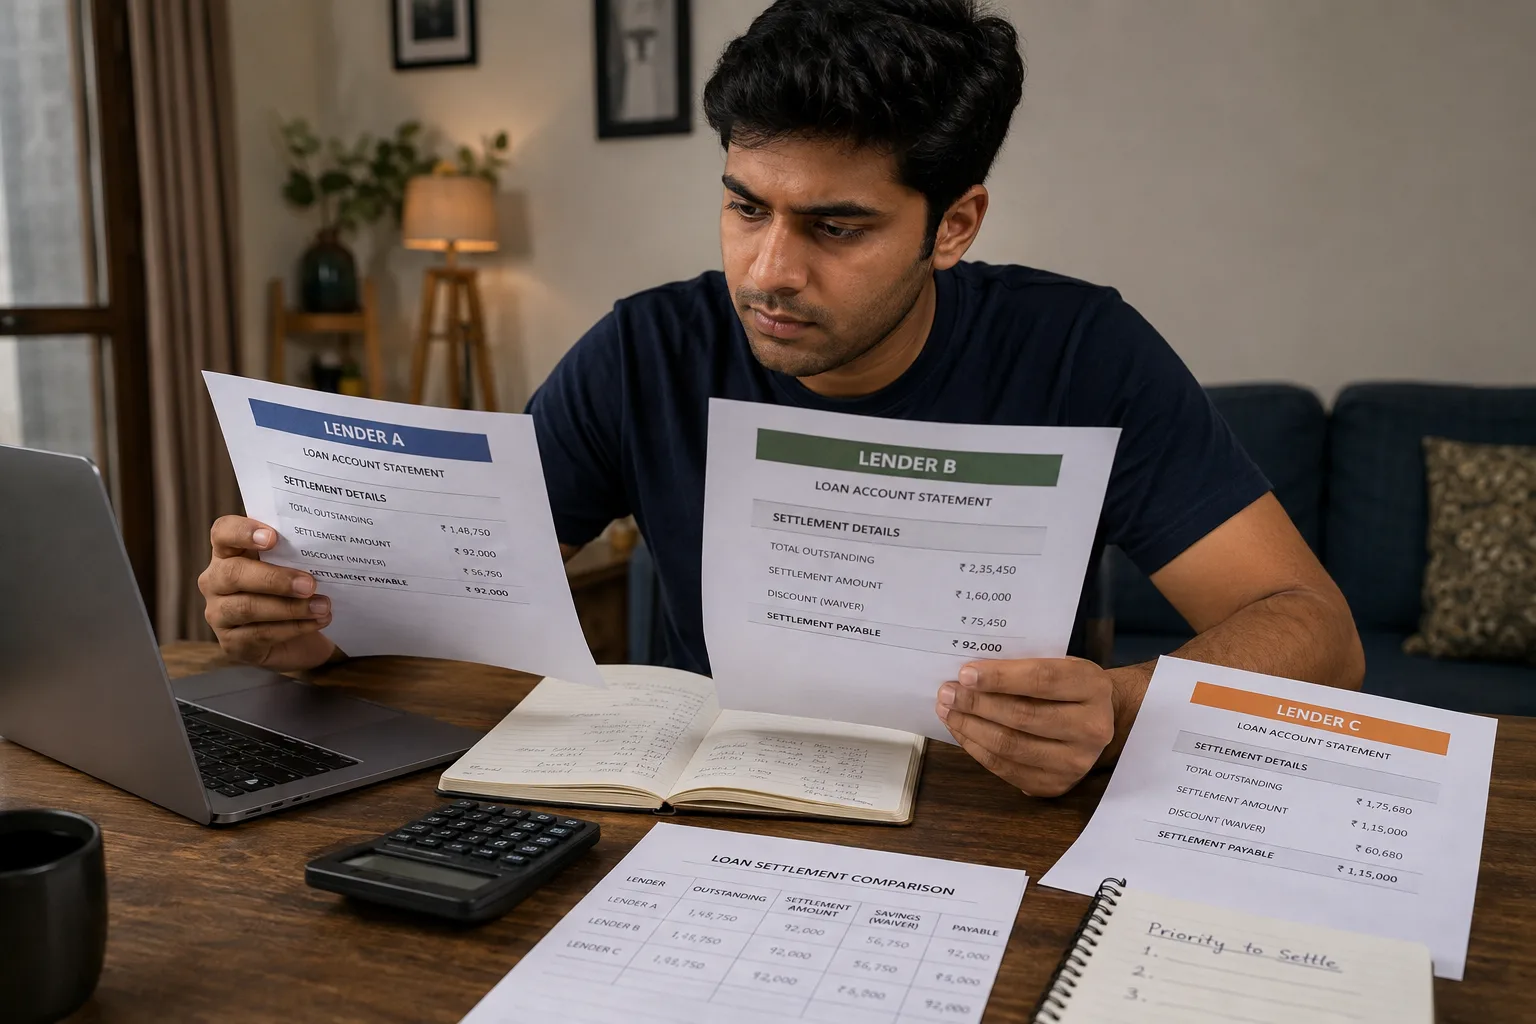
Settling with multiple unsecured lenders means negotiating a reduced final payment with each bank or NBFC separately, one account at a time, until every outstanding personal loan or credit card is marked settled. It is for borrowers who are genuinely unable to repay in full, not a shortcut for anyone juggling loans comfortably.
One-Time Settlement Letter: What a Valid OTS Letter Includes
A one-time settlement letter is the bank's written confirmation of a negotiated settlement, issued after a settlement amount has been agreed upon but before any payment is made. It's different from the request letter a borrower sends to start the negotiation. This is the document you should never pay against unless it has every required element in writing.
लोन सेटलमेंट के नुकसान: करना चाहिए या नहीं
लोन सेटलमेंट के नुकसान वे असर हैं जो बैंक से कम पैसे में लोन सेटल करने पर आपकी क्रेडिट रिपोर्ट और आगे के कर्ज़ पर पड़ते हैं। रिपोर्ट पर "सेटल्ड" टैग लगता है, स्कोर गिर सकता है और नया लोन मिलना मुश्किल हो सकता है। इसलिए सेटलमेंट तभी सोचें जब पूरा चुकाना सच में संभव न हो।

Make smarter financial decisions.
Loan Settlement | Loan Consolidation | Credit Insights | FREED Shield
Get Started