Wishfin CIBIL Score Free: How It Actually Works
Wishfin CIBIL score free is a no-cost score check on Wishfin, a site that compares loans and cards. Wishfin says the score comes from TransUnion CIBIL. You must give consent before you see it, and loan or card offers from partner banks can follow.
Mohit Juneja
Reviewed by FREED India, Debt Resolution Specialists
 4.7/5
 ₹3,200Cr+
 20,000+
 20,00,000+4.7/5₹3,200Cr+20,000+20,00,000+
Key Summary

Wishfin CIBIL score free is a no-cost check, and Wishfin says the score comes from TransUnion CIBIL.
Wishfin's campaign page promises 12 months of free membership with a free CIBIL report each month.
Consent lets Wishfin fetch your CIBIL data for up to 6 months, and partner banks may check too.
RBI directs every credit bureau to give 1 free full credit report each calendar year
What Is Wishfin CIBIL Score Free and Why Is It Free?
Wishfin CIBIL score free is a no-cost score check on a site that compares loans and credit cards. You enter your details, give consent, and see a score. Wishfin says that score comes from TransUnion CIBIL.
First, a quick word on the number itself. A CIBIL score is a three-digit number between 300 and 900. It sums up your loan and card history in one figure. A higher number tells lenders you have repaid on time. Behind the number sits a CIBIL report, which lists your accounts, your payments and the lenders who have checked your file. Here is a plain explainer on what a CIBIL score is.
Now, what does Wishfin say about its own offer? Here is what its campaign page says:
Wishfin runs a marketplace where you compare and apply for loans and cards.
You can reach the free check through its website or a WhatsApp route.
The page promises a free CIBIL score and a credit health report.
It also promises a 12-month free membership, with a free CIBIL report each month.
Its disclaimer says Wishfin does not sell loans itself and does not charge customers a fee.
Notice that "free" shows up in three places here. The score is free. The report is free. The membership is free for 12 months. Each is a separate promise, and each has its own terms. Keep that in mind, because it comes up again later.
So why is it free? The score is the front door. The business is the loan and card matching behind it. Wishfin says it does not charge customers. So the free score sits beside offers from partner banks. That is how a marketplace works. You get a number, and the platform gets a chance to show you products.
Here is a quick example. You check your score and see 702. A moment later, a personal loan offer shows up on screen. That offer is not part of your score. It is a separate layer, and you can ignore it. Your score stays 702 whether you tap the offer or not.
Nothing here says Wishfin is good or bad. It is a platform with its own way of working. "Free" is clear enough. What is worth checking is the CIBIL link, and that is the next section. If you only have your PAN handy, see how to check your score with PAN.
Is Wishfin an Official CIBIL Partner, and How Can You Check?
Wishfin says it is the first official fintech partner of TransUnion CIBIL. News coverage at its launch in December 2017 also reported a tie-up between the two. That is what Wishfin and the coverage say.
Why does this matter to you? Because it tells you where your data comes from. A score from CIBIL's own records is one thing. A score from some other source, shown under the CIBIL name, is another. The partner claim is the way to tell them apart.
CIBIL has its own way of showing partners:
It publishes an official-partners page that lists partners by logo.
It asks you to look for the "Powered by CIBIL" logo.
It warns about false partnership claims.
It says its member banks and NBFCs can offer scores too.
That last point is easy to miss. A score can be genuine without a direct partner badge, because a bank that is a CIBIL member can show you your score. So the badge and the score are two separate questions. A missing badge does not prove a fake score. A badge does not prove the score is right for today.
As of 7 October 2026, Wishfin's name did not appear in the logo list on CIBIL's partners page. That list can change. So we are not saying anything about the claim either way. If you want to be sure, ask Wishfin, or check with CIBIL.
Here is how to check it yourself before you share your PAN:
Open CIBIL's official-partners page.
Look for the logo of the platform you are about to use.
Take your free report straight from CIBIL, and compare it with the platform's score from around the same day.
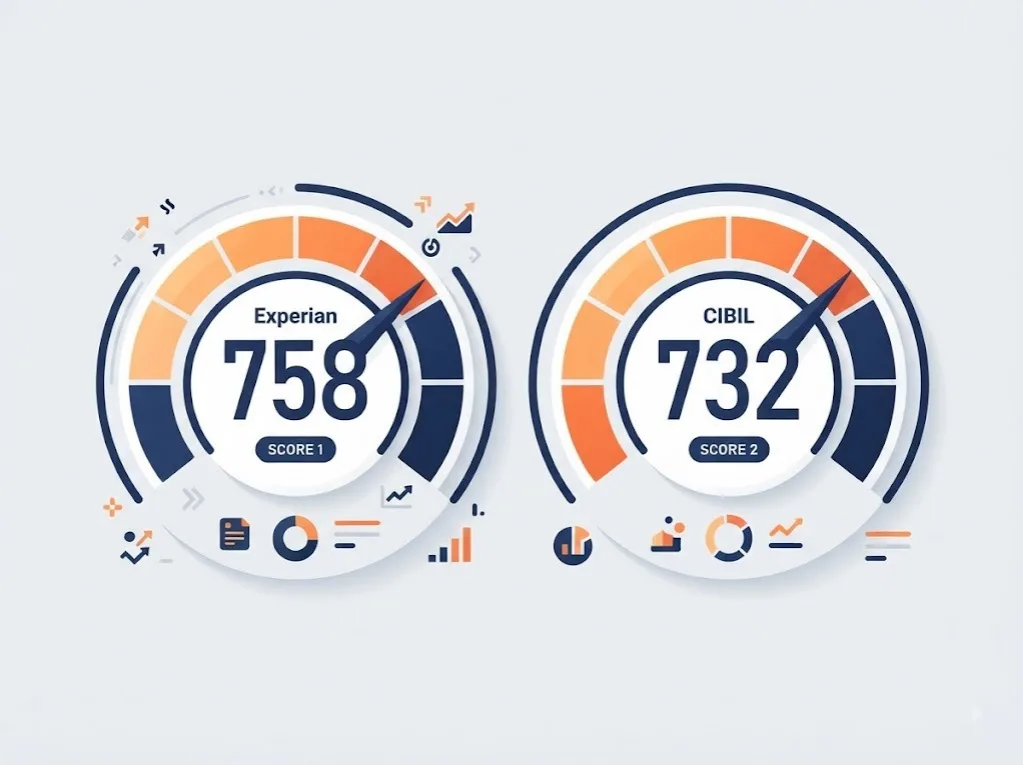
Here is how to read the comparison. Say the platform shows 748 and your CIBIL report shows 744. That is a small gap. Data refreshes on different days, so a few points is normal. Now say the platform shows 748 and your CIBIL report shows 690. That is a big gap. Do not panic. Look at the account list in both reports, and check whether a loan or card is missing or wrong. If you find a real error, here is how to fix wrong entries. To get the CIBIL report itself, see how to download a free CIBIL report.
One more point from CIBIL. It says it never contacts you by email, SMS or phone about improving your score. If a caller claims to be from CIBIL and offers that, do not share your OTP or PAN. You can also see how a Google Pay score check works as another route.

Expert Tip
Open CIBIL's official partners page and look for the Powered by CIBIL logo before you share your PAN.
How to check your score?What Is Free and What Is Not on Wishfin?
The score and a basic report are free. In return, you share data and may get offers.
Where Can You Get a CIBIL Score in India?
Option | Where the score comes from | Cost | What to know |
Direct from CIBIL | TransUnion CIBIL | 1 free full report per calendar year (RBI rule) | Extra reports or monitoring can be paid |
Wishfin free score | CIBIL, per Wishfin | Free, with a 12-month membership per its campaign page | Consent needed; offers from partner banks can follow |
Other score apps and marketplaces | Varies, check the app | Score usually free | Terms and offers vary |
FREED Credit Insights | Experian | ₹249 for 3 months | Gives score, what pulls it down, and step-by-step actions |
Details are indicative and can change. Please verify directly on each platform. FREED is not a Loan Provider.
Here is how to read the table. Look at "Where the score comes from" first. It tells you whose record stands behind the number. Then look at "Cost". Free here means the score and a basic report, plus the promo window. It does not mean every service you see on the site.
Let us walk through three different readers.
A reader who only wants a number. You can stop right after the score. You do not need to open the loan offers or any extra plan. Note the date, close the app, and you are done.
A reader who wants to track the score each month. The 12-month promo may suit you, because it promises a report every month for a year. Set a monthly reminder on your phone so you actually use it.
A reader who wants the score explained. A free score tells you the number but not always why. In that case, read your report's account list yourself, or consider a paid explanation service.
Now the 12-month window. Wishfin's page promises a free report each month for a year. It does not say what applies after month 12. So check Wishfin's current terms before you rely on it. CIBIL also has paid plans for extra reports and monitoring. Read how CIBIL fees and plans work before you pay for anything.
Rates and ranges shown are indicative. Final terms decided by the bank. FREED is not a Loan Provider. No outcome is guaranteed. Please verify directly with your bank.
How to Check Your Wishfin CIBIL Score Free, Step by Step?
Keep your mobile number and PAN ready. The bureau needs them to match your file.
Choose the WhatsApp route or the website route. Both ask for your mobile number first.
Read the consent text before you tick Agree. It sets what Wishfin can fetch and for how long.
Complete the OTP or chat steps. This proves the file is yours.
Read your score and report. Look for late payments, high credit utilisation and recent enquiries, as these can affect your credit score.
Say no to offers you do not want. A score check does not need you to apply for anything.
Checking your own credit report or score is generally treated as a soft enquiry and does not lower your score. A lender's enquiry made in connection with a credit application may be treated as a hard enquiry and can affect your score. Read the full answer on whether checking reduces your score. If you prefer your phone, see how to check your CIBIL score on mobile.
Things do not always go smoothly. Here are the common snags and what to do about each:
The details do not match. A wrong spelling of your name, a different date of birth or a mistyped PAN can pull no file or the wrong one. Re-enter your details exactly as they appear on your PAN card.
The OTP does not arrive. Check that the mobile number is active and has network. Wait a minute before asking for a fresh code.
The screen shows no score. First-time borrowers often have no history yet, so a score may not exist. This guide explains what NH means on a CIBIL report.
Before you tap Agree in step 3, it helps to know what the consent text says. That is the next section.

See Your Score and What to Fix First
Get your Experian score, what pulls it down, and clear next steps.
Check My Credit InsightsWhat Are You Agreeing to When You Share Your Data With Wishfin?
Here is the consent text on Wishfin's campaign page, in plain words:
Wishfin acts as your agent. It fetches your CIBIL data on your behalf. You are asking it to go and get your record, so the platform does not hold the record by default.
One consent covers up to 6 months. After that, you must refresh it. If you do nothing, access should lapse.
Wishfin may store your data for up to 6 months. It stores it until the purpose ends or until you withdraw consent, whichever comes first. So you can end it earlier.
Partner banks may check too. The terms authorise Wishfin and its partner banks to run a CIBIL or Experian check for your profile. This is how offers get matched to you.
CIBIL disclaims liability. The form has a line to that effect, which is common in forms like this.
Here is an example with dates. You give consent on 1 March. Access then lasts until about 1 September, unless you refresh it. If you withdraw consent on 1 June, the storage can end then, instead of running to September.
Does a partner bank check count as a hard enquiry? We could not find a verified source that says so. So the safer step is to look yourself. Check the enquiries section of your report to see who looked. Here is what to do with that section:
Look at each enquiry's date and the name of the lender or platform.
Match each one to something you did, like an app you used or a loan you asked about.
If you see a name you do not recognise, note it down and keep a copy.
This guide on soft and hard enquiries explains the difference, and this one shows how to read your CIBIL report. Your report also updates as banks send new data. See how long a CIBIL score takes to update.
None of this makes the terms unfair. It is simply what you agree to. Read the text, then decide. Terms can change, so read the live version on the day you sign up.
How to Get Your Real CIBIL Score Free Directly From CIBIL Once a Year?
RBI has a simple rule. Every credit information company must give you 1 free full credit report, with your score, once in a calendar year (January to December). The circular took effect on 1 January 2017.
The full report is meant to carry the same level of detail as the version lenders see. That is why the direct report is worth taking, even if you also use an app. The app gives you a quick number. The report gives you the full record, including each account and each enquiry.
Here is how to get it:
Go to the bureau's own website.
Verify with the OTP sent to your mobile.
Download the full report with your score.
Set a reminder for January, when your free report renews.
You can take one free report from each bureau. So that is one from CIBIL, Equifax, CRIF High Mark and Experian. Here is a smart way to use that. Spread them across the year. Take CIBIL in January, Experian in April, Equifax in July and CRIF High Mark in October. That gives you a fresh look at your credit every three months, at no cost. Here is a guide to the annual credit report and a page on getting a free Experian report.
This right is separate from any app promo. So you can use both and compare the two scores. When you have both in hand, check three things:
Do the account lists match?
Are the balances roughly the same?
Does any enquiry look unfamiliar?
If the two numbers are close, good. If they are far apart, look at the accounts listed in each report.

What the Law Says
Every credit bureau must give you 1 free full credit report, including the score, each calendar year.
Download Free ReportHow FREED Helps If You Want to Understand and Improve Your Score?
A free score tells you where you stand. It does not always tell you what to fix. That is where a paid option can help, and it is fair to say that up front.
FREED Credit Insights ("Check My Credit") is not free. It costs ₹249 for a 3-month subscription. It is open to everyone, whether or not you are in any FREED program.
It uses your Experian report. So it is an Experian score, not a CIBIL one. It does three things:
It shows your score.
It shows what is pulling that score down.
It gives step-by-step actions to improve it.
It does not rebuild your score for you. It shows you what to fix, and you do the fixing. Think of it as a map with arrows, not a car.
It is also one option next to the free ones. A platform's free score gives you a quick number. A bureau's free yearly report gives you the full record. Credit Insights is for readers who want that record explained in plain words, with next steps attached. If you want to know how the two bureaus differ, read about Experian versus CIBIL. If you are weighing a paid credit score improvement agency, read what is included before you pay.
If EMIs are the real strain, there is another route. When several EMIs stretch your month, FREED's Debt Consolidation Program is built for people who can still repay. FREED assesses your profile and matches you with a lending partner. One new loan then replaces your existing ones, so you pay one lower EMI to one lender. It is for readers who pay every EMI but want one simpler payment.
Are You in a Loan Trap? Quick Check
Move the slider to your total EMIs as a % of monthly salary. See your debt stress level instantly.
EMIs as % of Monthly Salary
Sourcing and Verification
Claim | Source |
Every credit information company gives 1 free full credit report, with score, per calendar year (effective 1 January 2017) |
All other claims are unlinked and softened in the text: "Wishfin says", "per its campaign page", "commonly reported".

Mohit Juneja
Mohit Juneja is FREED’s Content & Communication Lead with 12+ years of experience across content, media, advertising and digital communications. He holds a postgraduate diploma in Communications from Xavier Institute of Communications, Mumbai, and has worked with organisations including NDTV, The Indian Express, McCann Worldgroup and NABARD.
At FREED, he leads content and communication across loan management, debt resolution, debt consolidation and financial well-being. His work combines research, storytelling and consumer-focused communication to make complex financial topics easier to understand and act on. He has also scripted and produced 11 documentaries on rural development and agriculture for NABARD, with film's selected for the Mumbai International Film Festival.
mohit.juneja@freed.care

FREED is India's trusted loan management platform. Founded in 2020 and headquartered in Gurugram, FREED has counselled 20 lakh+ people on personal loans, credit cards, and app loans. FREED charges fees only on successful settlement, not upfront. FREED does not handle secured loans (home loans, car loans, gold loans).
Media Mentions