Ram Fincorp Recovery Agent Home Visit: Your Rights and What to Do
A Ram Fincorp recovery agent home visit may occur when payments on a loan are overdue. Before discussing your account or making a payment, verify the lender named in your loan agreement or Key Fact Statement (KFS) and ask the visitor to establish their identity and authority. Recovery agents must follow applicable conduct requirements; threats, harassment, public humiliation and improper intrusions into privacy are not acceptable.
Mohit Juneja
Reviewed by FREED India, Debt Resolution Specialists
 4.7/5
 ₹3,200Cr+
 20,000+
 20,00,000+4.7/5₹3,200Cr+20,000+20,00,000+
Key Summary

A Ram Fincorp recovery agent home visit is allowed, but threats and harassment are not.
RBI bars agents from humiliating you publicly or intruding on your family’s privacy.
For app loans, RBI requires the company to share the recovery agent’s details with you before contact.
Recovery calls are allowed only between 8 a.m. and 7 p.m.
If a visit crosses the line, complain to the company first, then to RBI.

Recovery Agent Crossed the Line? You Don’t Have to Face It Alone
Understand your rights and report harassment with FREED Shield.
Get Help With HarassmentWhat Happens During a Ram Fincorp Recovery Agent Home Visit?
A recovery visit is how a loan provider reaches a person who has stopped picking up calls about overdue payments. It is a collection step, and companies use it when calls and messages bring no reply.
A recovery agent may contact you or visit your address to discuss overdue loan payments. Before discussing the account, check your loan agreement and Key Fact Statement (KFS) to identify the bank or NBFC that provided the loan and confirm which agency, if any, has been authorised to handle recovery.
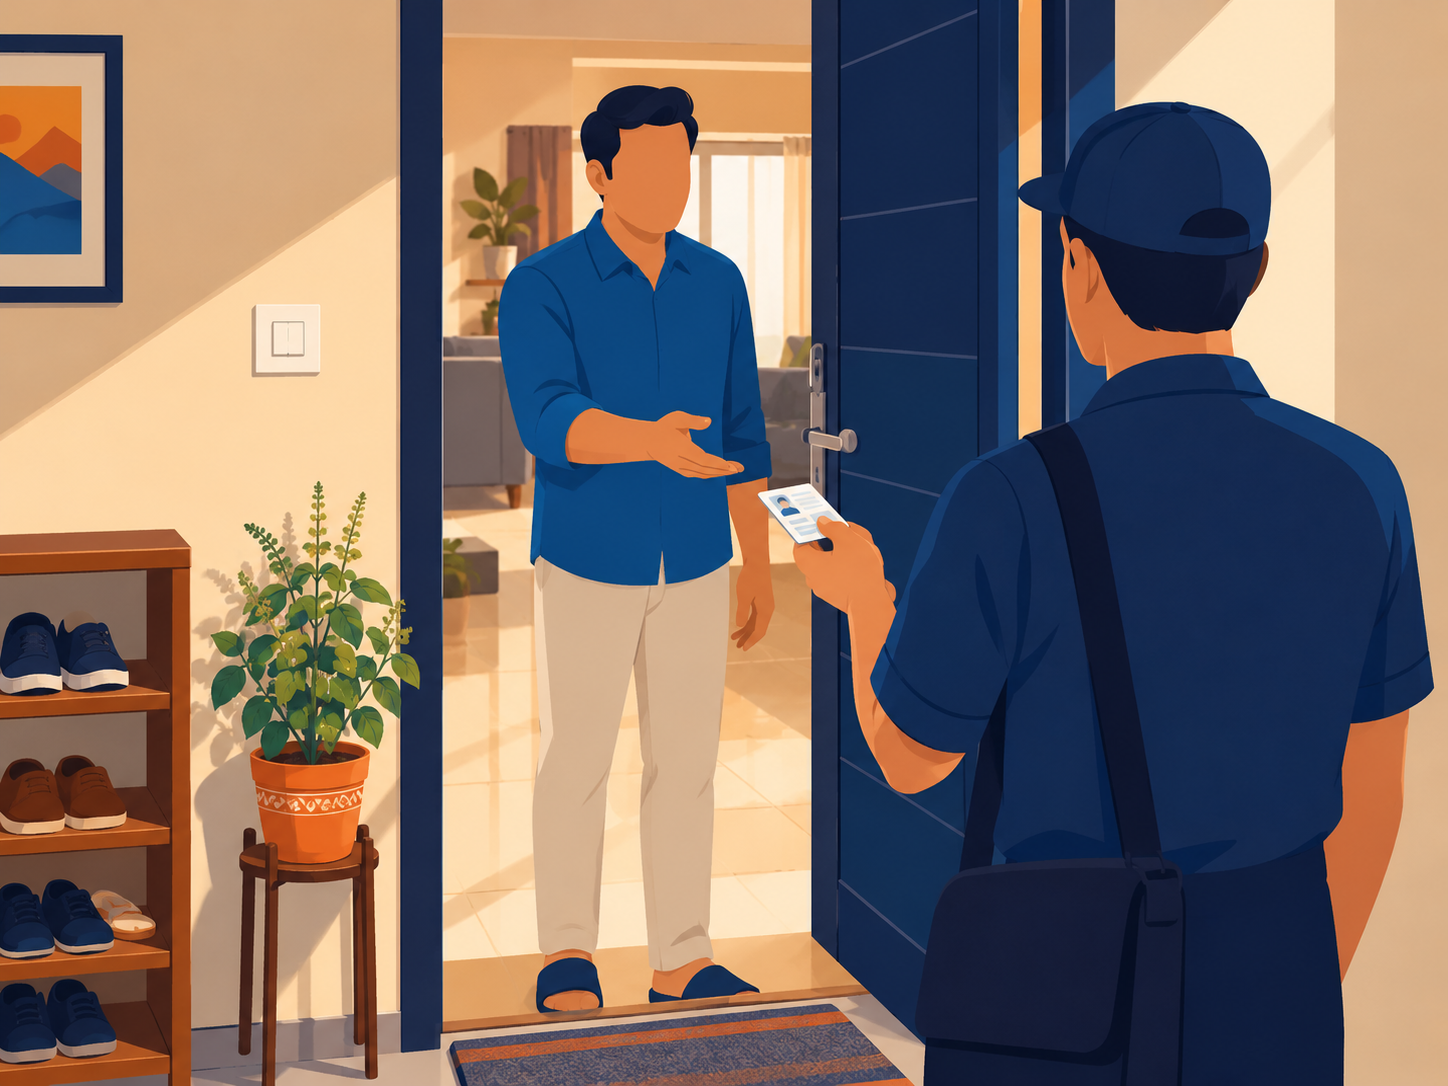
During a visit, an agent may explain the outstanding amount, ask about repayment, or provide a written communication. You can request identification, verify the agent’s authority through the lender’s official contact channel, and ask for any repayment proposal or notice in writing.
A recovery visit does not, by itself, mean that you will be arrested. Do not assume that a loan is secured or unsecured based only on the app through which you applied. Check the loan documents. If an agent threatens to seize belongings, ask for the legal basis and verify the claim directly with the lender or a qualified legal professional.
Knowing this changes how a Ram Fincorp recovery agent home visit feels. The person at your door is a collection agent with a job to do, and there are rules for how they do it. To understand those rules, read who a recovery agent is and what they are authorised to do.
First, though, why did the visit happen at all?
Why Does a Recovery Agent Visit Your Home?
Two short-term app loan payments slipped after a pay cut. The calls went unanswered because you had no good news to share. Then one evening the doorbell rings, and the kids are home.
Visits usually follow missed payments and unanswered calls. App loans often have short repayment windows, so dues and late charges build up fast, sometimes faster than a household can adjust. By the time the first visit happens, the amount on the notice can look much larger than what you borrowed.
If this has happened to you, the feelings are real. There is embarrassment in front of neighbours, fear for your family, and the sinking sense that everyone can see your private problem. Those reactions are normal, and they do not say anything bad about you.
Here is the reassuring part. This happens to many careful people after a rough patch, a pay cut or a medical bill. One agent at your door is not a verdict on your character. And there are rules, written down by RBI, about how that agent may behave. A Ram Fincorp recovery agent home visit has to follow the same conduct rules as any other.
For many families the hardest part is not the money. It is the 10 minutes after the agent leaves, when the house is quiet and nobody knows what to say. Planning for that moment helps as much as planning for the visit.
Read your rights as a borrower in full when you have a quiet moment. For now, let’s go through the main ones.
What Are Your Rights During a Ram Fincorp Recovery Agent Home Visit?
RBI’s rules on recovery conduct, and its Digital Lending Directions for app loans, give you these protections. Keep this list handy.
- No intimidation or harassment. RBI says verbal or physical intimidation or harassment of any kind is not allowed.
- No humiliation or privacy intrusion. Agents must not act in a way meant to humiliate you publicly, or intrude on the privacy of your family, referees or friends.
- No false or misleading claims. An agent cannot make untrue statements about your loan, your rights or what will happen next.
- No threatening or anonymous calls, no persistent calling. Calls are allowed only between 8 a.m. and 7 p.m.
- Agent details before contact. For app loans taken through a digital lending app (DLA), the company must share the recovery agent’s details with you by email or SMS before the agent contacts you. This applies when an agent is assigned after a default.
- The company stays responsible. The bank or NBFC that gave you the loan remains responsible for the acts of the service providers it uses, which includes recovery.
Now an honest note. RBI does not fix specific hours for home visits. The 8 a.m. to 7 p.m. rule is written for calls. But a visit at an odd hour that harasses or humiliates you still breaks the conduct rules.
For loans from banks, RBI’s 2008 instructions add that agents should carry an identity card, an authorisation letter and a copy of the notice. That rule is addressed to banks, so it may not cover your loan directly. Even so, asking any agent for these is a reasonable request.
These protections are summarised in our guide to RBI recovery agent rules.

What the Law Says
RBI bars recovery agents from humiliating you publicly or intruding on your family’s privacy.
Get Help With HarassmentWhat Should You Do When a Recovery Agent Comes Home?
If a Ram Fincorp recovery agent home visit happens, these steps keep things calm and on record.
- Stay calm and speak at the door. You do not have to let anyone inside.
- Ask for ID and an authorisation letter. Note the name, agency and ID number.
- Confirm the company and the loan. Ask which bank or NBFC sent them and which loan account they mean.
- Don’t pay cash or to a personal UPI ID. Pay only to the company’s official account.
- Don’t sign anything on the spot. Ask for any notice or offer in writing.
- Write down what happened. Date, time, names, what was said and who was present.
- Call the company’s official customer care. Check the agent is genuine and log the visit.
If you can pay something, tell the company in writing rather than the agent at the door. A written message gives you a record, and the agent’s promise at the door gives you nothing.
One more habit helps. After the visit, send the company a short email the same day: the date, the time, the agent’s name and what was said. If this was your first Ram Fincorp recovery agent home visit, that email also starts the paper trail you may need later.
Good notes make any later complaint stronger. Our guide on how to keep a record shows what to write down and how to store it.
How Do You Know a Home Visit Has Crossed the Line?
Start with what a normal collection visit looks like:
- A polite reminder of the dues
- ID shown without being asked twice
- A written notice left with you
- A visit at a reasonable hour
- A conversation only with you
Now the other side. These signs mean the visit has crossed the line.
Shouting or abuse. Raised voices and insults are harassment, whatever the amount owed.
Threats about police, jail or taking household items. This is a common pattern of false claims. Agents sometimes use these lines to frighten people into paying on the spot. Do not treat them as a legal statement, and ask for anything official in writing.
Telling neighbours or relatives about your loan. RBI bars acts meant to humiliate you or intrude on your family’s privacy.
Refusing to show ID. A genuine agent has no reason to avoid it.
Demanding cash with no receipt. Pay only through the company’s official account.
Coming at night or repeatedly to shame you. Repeated visits meant to embarrass are harassment, even when each visit is short.
Contacting your workplace to embarrass you. That is also an intrusion on privacy.
If you feel physically unsafe at any point, call 112. Do not wait for the visit to end.
If you recognise two or more of these signs after a Ram Fincorp recovery agent home visit, read about recovery harassment and how to respond to it.
Agent Visited Without Following the Rules?
FREED Shield helps you document and report it.
Report HarassmentHow to Complain About a Ram Fincorp Recovery Agent?
If a visit crossed the line, here is the route to follow. Start at the bottom of the ladder and work upward.
- Write to the company’s grievance redressal officer. The name and email are usually on the app or the company’s website. Attach your notes, dates and any photos or messages, and keep the acknowledgement.
- Go to RBI if there is no reply. If you hear nothing within the time the scheme allows (commonly 30 days), or you are not satisfied, file a complaint on RBI’s CMS portal (complaint management system, cms.rbi.org.in) under the Integrated Ombudsman Scheme, 2026.
- Call the RBI Contact Centre on 14448. It can help you with the process.
- Go to the local police if your safety is threatened. Do not wait for the complaint steps to finish.
Under the scheme, compensation may be possible for harassment and mental anguish. The amount and the conditions are in the scheme itself.
A Ram Fincorp complaint works best when it is short and factual: dates, times, names and what was said. For wording help, see our sample complaint letter. Our guide to the RBI complaint process walks through each step.
What Are Your Options If You Can’t Repay the Ram Fincorp Loan?
An honest opener first: complaining about harassment does not cancel the loan. The dues remain. Both things can be true, and you can deal with both. Here are your options, in order.
- Ask the company in writing for more time or a changed repayment schedule. This costs nothing and keeps the record clean.
- Take a Loan Consolidation Plan if you are still paying several loans. One new loan pays off your existing app loans and card dues, and you pay one lower EMI. Your CIBIL score is not hurt and starts improving over time. FREED’s Loan Consolidation Plan is built for people in this situation.
- Use loan settlement only if you genuinely cannot repay. Settlement is not something a borrower chooses out of preference. Banks and financial companies only consider it when you are in a genuine financial difficulty and are truly unable to repay the full amount. A settled loan shows a “Settled” mark on your credit report for up to 7 years, and settlement can bring dues down by up to 50%*. See the Loan Settlement Plan and our guide to loan settlement.
Rates and ranges shown are indicative. Final terms decided by the bank. FREED is not a Loan Provider. No outcome is guaranteed. Please verify directly with your bank.
If you are weighing these options after a Ram Fincorp recovery agent home visit, start with the one that keeps your record cleanest and move down only as needed. Use the calculator below to estimate what a settlement might look like for your loans.
Rates and ranges shown are indicative. Final terms decided by the bank. FREED is not a Loan Provider. No outcome is guaranteed. Please verify directly with your bank.
Are You in a Loan Trap? Quick Check
Move the slider to your total EMIs as a % of monthly salary. See your debt stress level instantly.
EMIs as % of Monthly Salary
How FREED Helps If a Recovery Agent Visit Turns Into Harassment
When recovery conversations cross the line into abusive, threatening, or harassing behaviour, FREED provides an added layer of support through FREED Shield, a dedicated borrower-support service. FREED Shield helps you understand your rights as a borrower and can assist you in preparing and submitting a complaint through the appropriate channels where necessary.
FREED Shield is open to everyone, not only FREED customers. FREED steps in when a call turns abusive or threatening, or when an agent visits your home or office without following protocol. You can file a complaint on the FREED app. If a harassment call is happening right now, you can call the FREED helpline for support.
If you have received a legal notice, FREED’s in-house team checks whether the notice is genuine and helps draft a reply if needed. This is pre-litigation support. To understand what these notices mean, read about a legal notice for loan recovery.
To be clear about what FREED does not do: FREED does not stop calls, and it does not speak to agents in standard cases. FREED Shield helps ensure that customers don’t have to face recovery-related pressure alone.
If a Ram Fincorp recovery agent home visit left you shaken, filing a report through FREED Shield gives you a calm, documented way to respond.
FREED has settled 33,000+ accounts, counselled 20,00,000+ customers and managed ₹3,500 Cr+ debt. Rates and ranges shown are indicative. Final terms decided by the bank. FREED is not a Loan Provider. No outcome is guaranteed. Please verify directly with your bank.
Don’t Face Recovery Pressure Alone
Report a visit or call that crossed the line.
Report Harassment on FREEDTips for Staying Calm During a Recovery Agent Visit
A visit is easier to handle when your household has already talked about it.
- Tell your family in advance what to do if an agent comes. One person speaks at the door. Everyone else stays inside and carries on.
- Keep your loan papers and a notebook in one place. A folder by the door means you are never searching while someone waits. After any visit, write down your own version within the hour, while the details are fresh.
- Speak at the door and keep it short. “Please leave your details and any notice. I will reply in writing.” That is enough.
- Don’t argue or match their tone. If a voice rises, yours stays level. Raised voices help no one, and they weaken your own complaint later.
- Share the situation with one trusted person. A cousin, a close friend, someone who can sit with you after the visit. Saying it out loud to one person makes it smaller.
- Reply to the company in writing. A written reply makes the next contact calmer, because the conversation moves onto paper.
The visit is stressful, but the rules are on your side, and there are clear steps to follow. Even a Ram Fincorp recovery agent home visit has limits, and you know them now. Our guide to your rights even if you default explains what still protects you when payments have already been missed.
Sourcing and Verification
| Claim | Source |
|---|---|
| No intimidation, public humiliation or privacy intrusion; no false claims; calls 8 a.m. to 7 p.m.; applies to NBFCs | RBI/2022-23/108, 12 August 2022 |
| App loans: recovery agent details shared by email/SMS before contact (para 8(v)) | RBI Digital Lending Directions, 2025 |
| Banks: agents carry ID card, authorisation letter, copy of notice | RBI/2007-2008/296, 24 April 2008 |
| Integrated Ombudsman Scheme, 2026 in force from 1 July 2026 | RBI press release, 16 January 2026 |

Mohit Juneja
Mohit Juneja is FREED’s Content & Communication Lead with 12+ years of experience across content, media, advertising and digital communications. He holds a postgraduate diploma in Communications from Xavier Institute of Communications, Mumbai, and has worked with organisations including NDTV, The Indian Express, McCann Worldgroup and NABARD.
At FREED, he leads content and communication across loan management, debt resolution, debt consolidation and financial well-being. His work combines research, storytelling and consumer-focused communication to make complex financial topics easier to understand and act on. He has also scripted and produced 11 documentaries on rural development and agriculture for NABARD, with film's selected for the Mumbai International Film Festival.
mohit.juneja@freed.care

FREED is India's trusted loan management platform. Founded in 2020 and headquartered in Gurugram, FREED has counselled 20 lakh+ people on personal loans, credit cards, and app loans. FREED charges fees only on successful settlement, not upfront. FREED does not handle secured loans (home loans, car loans, gold loans).
Media Mentions