Let’s talk
about Loans







75,000+
Customers served

₹450 Cr+
Total savings

4.8/5
Google rating
Browse Topics
5 CategoriesPersonal Finance
Small Loan Without CIBIL: Options for Salaried Borrowers
Yes, you can get a small loan without CIBIL. Lenders lend small amounts to first-time borrowers all the time, especially salaried ones. Expect a smaller limit and a higher interest rate than someone with a long credit history gets. And check the lender before you share a single document, because this is where fake apps hunt.
Kotak Personal Loan Foreclosure: Process and Charges
Foreclosure means paying off your entire Kotak personal loan before the last EMI date. You pay the outstanding amount, accrued interest, and a foreclosure charge plus GST. The loan then closes, and you receive a No Dues Certificate.
ICICI Personal Loan Foreclosure: Charges and Steps
Foreclosure means paying off your whole ICICI personal loan before the last EMI date. You pay the outstanding principal, interest due, and any foreclosure charge, plus GST. The bank then closes the loan and issues a No Objection Certificate.
लीगल नोटिस फॉर्मेट: पैसे की रिकवरी के लिए हिंदी में पूरी गाइड
पैसे की वसूली के लिए लीगल नोटिस फॉर्मेट एक लिखित मांग-पत्र का ढांचा है। इसमें पैसा देने वाला कर्ज़दार से बकाया रकम, कारण और भुगतान की आख़िरी तारीख़ माँगता है। यह कोर्ट का आदेश नहीं है। नोटिस हमेशा वकील से तैयार या जाँच करवाकर भेजें।
P2P Loans for Bad Credit in India: What to Know Before You Borrow
P2P loans for bad credit in India are unsecured loans from individual lenders, arranged by an RBI-registered NBFC-P2P platform. The platform checks your credit profile, but each lender decides whether to fund you. A low score makes approval harder and the rate higher. RBI does not promise that any borrower gets funded.
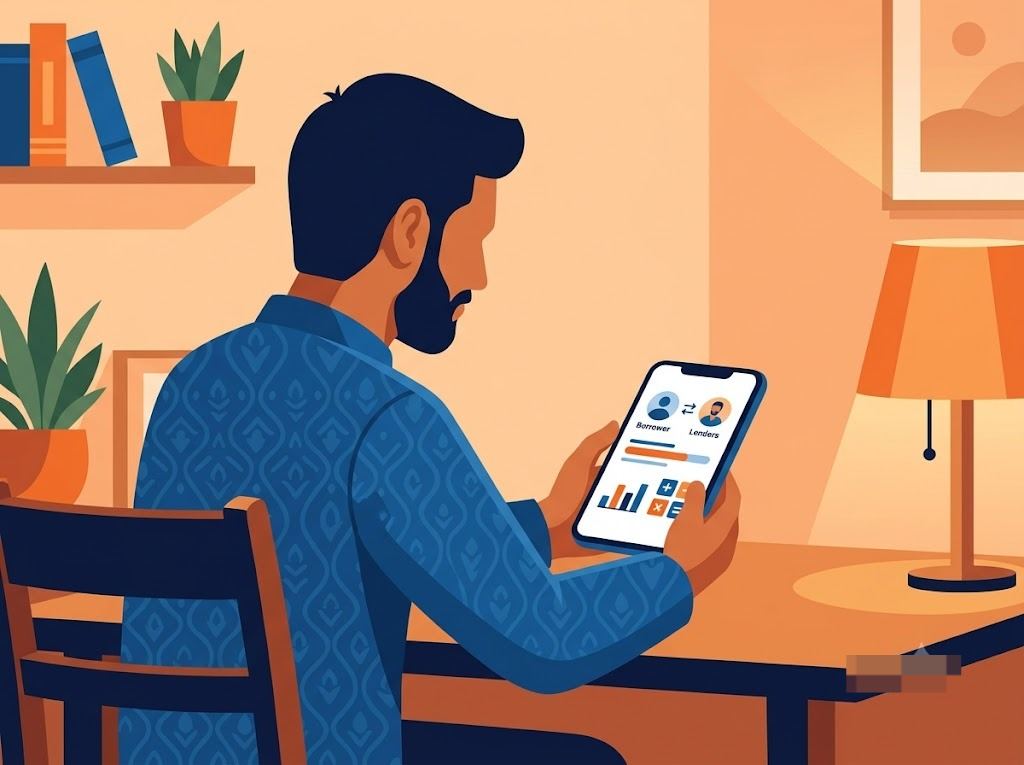
P2P Loans in India: How They Work and Is It Safe to Borrow?
P2P loans are personal loans where an online platform matches you with individual lenders instead of a bank. In India, only platforms registered with the RBI as NBFC-P2P can run this. The platform arranges the loan and moves money through an escrow account (a neutral holding account). It never lends its own money.
Mental Harassment by a Bank: What Counts, What You Can Do
Mental harassment is not simply a label for an unpleasant recovery call. Depending on the conduct and the forum involved, borrowers may be able to seek redress for harassment, mental anguish or loss caused by improper recovery practices. It covers a pattern of conduct, repeated abusive calls, threats, or contact with your family, designed to cause psychological distress beyond the legitimate purpose of collecting a debt. It comes with a real compensation remedy, not just a complaint.
What Is Cap Credit? Meaning Explained
Two friends apply for the same personal loan the same week. One asks for ₹5 lakh and gets it. The other asks for the same amount and walks away approved for ₹2.8 lakh instead- same bank, same product, wildly different number. That gap is cap credit, the highest amount a lender will actually extend you, a personal loan sanction or a card's credit limit, based on its own risk read of your income, your credit score, and your existing debt, not on what you asked for.

Make smarter financial decisions.
Loan Settlement | Loan Consolidation | Credit Insights | FREED Shield
Get Started