Creditmantri Free CIBIL Score in India: What's Really Free and What's Not
CreditMantri free CIBIL score is the credit score you can check at no cost on CreditMantri. The score is free, but CreditMantri's own site says it comes from Equifax and CRIF High Mark, not TransUnion CIBIL. So it is a free credit score, not an official CIBIL score.
Mohit Juneja
Reviewed by FREED India, Debt Resolution Specialists
 4.7/5
 ₹3,200Cr+
 20,000+
 20,00,000+4.7/5₹3,200Cr+20,000+20,00,000+
Key Summary

CreditMantri free CIBIL score costs nothing, but its site names Equifax and CRIF High Mark as sources.
RBI directs every credit bureau to give 1 free full credit report, with score, each calendar year.
Checking your own score is a soft enquiry. It does not lower your score.
Improvement services, health reports and extra bureau reports are separate offers, so read the terms first.
Scores from different bureaus can differ. Compare the bureau name, not just the number.
What Is the CreditMantri Free CIBIL Score?
The CreditMantri free CIBIL score is a free credit score on the CreditMantri platform. CreditMantri is a credit marketplace. It shows you your score and also matches you with loans and cards.
Here is the part most people miss. CreditMantri's free-score page says the score is powered by its bureau partners, Equifax and CRIF High Mark. It describes the free analysis as based on the Equifax report. The CreditMantri page reviewed for this article identifies Equifax and CRIF High Mark as its bureau partners; it does not identify TransUnion CIBIL as the source of the free score. So the number you get is a credit score, but it is not a CIBIL score.
That is not unusual, and it is not a problem by itself. India has four credit bureaus (companies that keep a record of your loans and card payments): CIBIL, Equifax, CRIF High Mark and Experian. Each bureau uses its own formula. All four show scores on the same 300 to 900 range, but the numbers can differ for the same person. You can read more about credit bureaus in India.
Why do so many people type "CIBIL" when they mean any credit score? Because CIBIL is the name most Indians know. It became the short word for "credit score", the way some people say "Xerox" for any photocopy. That is why the search is "CreditMantri free CIBIL score" and not "CreditMantri free Equifax score".
If you want your actual CIBIL number, that is a separate path. This guide shows how to check it on the official CIBIL website.
CreditMantri is not a scam, and nothing here says it is. It is a platform with its own way of earning. A free number is useful. It helps to know why it is free, and that comes next.
Why Is CreditMantri Giving a Free Credit Score?
You searched, tapped the "free" button, and typed in your PAN and mobile number. Now a small voice asks, "What is the catch?" That is a fair thing to wonder.
The short answer is that the score is the front door. The business sits behind it. Three things are worth knowing:
The platform matches you with lender products. CreditMantri shows loan and card offers based on your profile. It also sells credit improvement services. The free score brings you in, and the offers are what the platform runs on.
It has said publicly that lenders pay it. In a 2016 reply on its own forum, CreditMantri said it earns most of its revenue from lenders. That statement is old, so treat it as background and not as today's fact.
A consent screen usually comes first. You are asked to agree before you see the score. Offers by call, SMS or email are commonly reported to follow, so read what you agree to.
Here is a quick example. You check your score and see 690. A few seconds later, an app shows a personal loan offer you never asked for. That offer is not part of your score. It sits in the offer layer, which is separate. You can ignore it, and your score stays the same.
None of this means the app is unsafe. Free scores are common across credit marketplaces. Knowing how it works lets you use the free part and skip the rest.
So what exactly is free, and what costs money? The next section sorts that out.

Expert Tip
Read the consent screen before you tap Agree. It tells you whether loan offers and calls come with the free score.
See what a soft enquiry isWhat Is Free and What Is Not With the CreditMantri Free CIBIL Score?
The score and a basic health check are free. Several other things on the site are separate offers.
Where Can You Get a Credit Score in India?
Option | Score bureau | Cost | What to know |
Direct from a bureau (CIBIL, Equifax, CRIF High Mark, Experian) | That bureau | 1 free full report per calendar year (RBI rule) | Extra reports or monitoring can be paid |
CreditMantri free score | Equifax and CRIF High Mark (per its site) | Score free | Not a CIBIL score; extras are separate offers |
Other credit score apps and marketplaces | Varies, check the app | Score usually free | Offers and consent screens vary |
FREED Credit Insights | Experian | ₹249 for 3 months | Gives score, what is pulling it down, and step-by-step actions |
Details are indicative and can change. Please verify directly on each platform. FREED is not a Loan Provider.
Here is how to read the table. Look at the "Score bureau" column first. It tells you whose record stands behind the number. Then look at "Cost". Free here means the score. It does not mean every service on the site.
Say you only want to know your number. You need nothing paid. Check the free score, note the bureau name, and stop there. If you want your CIBIL number, take your one free report straight from the bureau. Here is how to get a free CIBIL report.
The paid items are separate offers with their own terms. They include credit improvement services, a detailed credit health report, and extra bureau reports. Paid plans exist for these, so check the current price on the site before you pay. If you are weighing a credit score improvement agency, read what is included first. This page on CIBIL fees and plans explains how bureau plans are priced.
Rates and ranges shown are indicative. Final terms decided by the bank. FREED is not a Loan Provider. No outcome is guaranteed. Please verify directly with your bank.
How to Check Your CreditMantri Free Score, Step by Step?
Keep your PAN, date of birth and mobile ready. The bureau needs them to match your file.
Open the free credit score page on CreditMantri and sign up. You get an OTP on your mobile to prove the number is yours.
Read the consent text before you agree. It tells you what data is shared and what offers may follow.
Enter your details and view your score. Note the bureau name shown next to it, so you know whose record it is.
Read the credit health analysis. Look for late payments, high card use and recent enquiries, because these move a score the most.
Say no to offers you do not want. A score check does not need you to apply for anything.
Checking your own score is a soft enquiry (a check that does not touch your score). It does not lower it. A hard enquiry (a check made when a lender looks at your file after you apply) is different. Here is a full answer on whether checking reduces your score. If you only have your PAN handy, see how to check your score with PAN.
Once you have the number, you may find it differs from another one you saw. That is normal, and the next section explains why.

See Your Score and What to Fix First
Get your Experian score, what pulls it down, and clear next steps.
Check My Credit InsightsWhy Is My CreditMantri Score Different From My CIBIL Score?
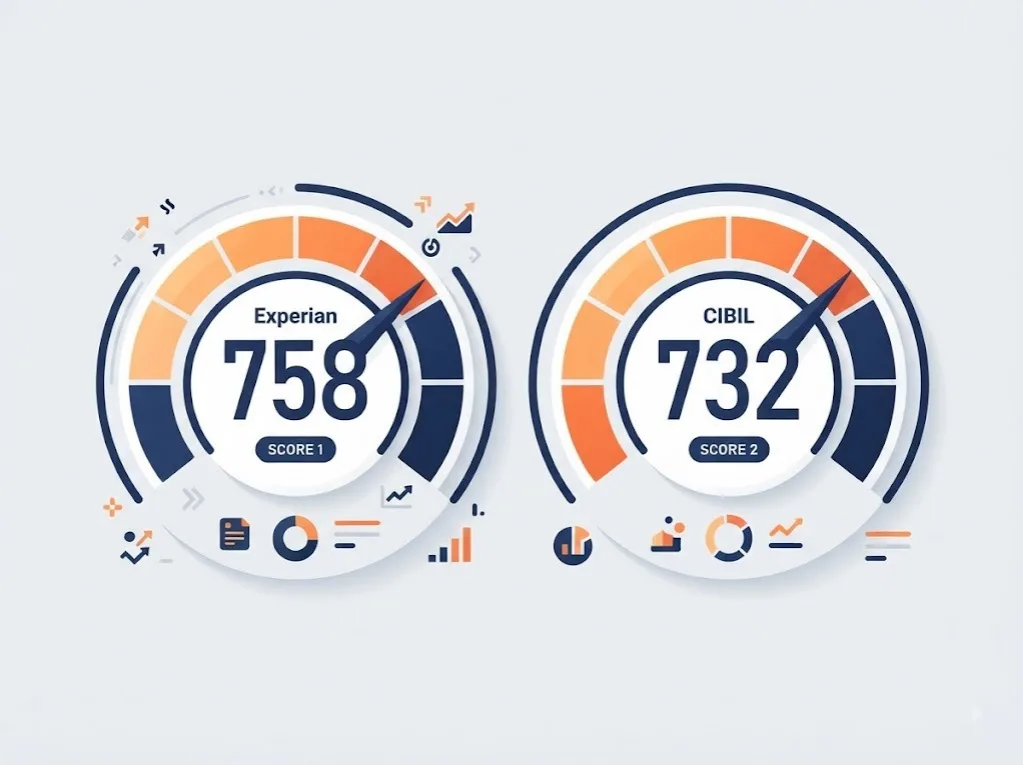
Different numbers are normal. They do not mean something is wrong with your file. Three simple reasons explain most gaps:
Each bureau uses its own formula. Two bureaus can read the same loan history and still give different scores. Each one weighs the details a little differently.
A lender may report to one bureau earlier or more fully than another. So one bureau can hold a newer or fuller record of you than the other.
The day you check matters. Bureaus refresh as banks send new data. A score from today and a score from two weeks ago are two different readings.
Here is an example with made-up numbers. Say one app shows 712 and your CIBIL score is 738. That is a gap of 26 points. For many lenders, both numbers sit in the same broad score band. The gap looks bigger than it is.
What if the gap feels large? Compare the account list in both reports. Check that each loan and card is yours and the status looks right. Raise a dispute only for real errors, such as a loan you never took. Here is how to fix wrong entries.
No bureau is "more accurate" than the others. Lenders may check any of them, so they do not look at CIBIL alone. Read more on CRIF score versus CIBIL score and why scores vary between bureaus.
How to Get Your Real CIBIL Score for Free Once a Year?
RBI has a simple rule. Every credit information company must give you 1 free full credit report, with your score, once in a calendar year (January to December). The circular took effect on 1 January 2017.
A full credit report contains substantially more account and enquiry information than a score-only display, making it more useful when you want to check the details behind your score. That is why the free official report is worth taking, even if you also use a free app. The app gives you a quick number. The report gives you the full record.
Here is how to get it:
Go to the bureau's own website.
Verify with the OTP sent to your mobile.
Download the full report with your score.
Set a reminder for next January, when your free report renews.
The rule works for each bureau. So you can take one free report from CIBIL, one from Equifax, one from CRIF High Mark and one from Experian. That is four free reports in a year.
A second CIBIL report in the same year is a paid plan. Paid plans are available, so check the current plans on the CIBIL site before you decide. This guide on the annual credit report explains how the yearly cycle works.

What the Law Says
Every credit bureau must give you 1 free full credit report, including the score, each calendar year.
Learn how to download your free reportHow FREED Helps If You Want to Understand and Improve Your Score
A free score tells you where you stand. It does not tell you what to fix. That is where a paid option can help, and it is fair to say so up front.
FREED Credit Insights ("Check My Credit") is not a free score. It costs ₹249 for a 3-month subscription. It is open to everyone, whether or not you are in any FREED program.
It uses your Experian report, so it is an Experian score and not a CIBIL one. It shows you three things: your score, what is pulling it down, and step-by-step actions to improve it. It does not rebuild your score for you. It shows you what to fix, and you do the fixing.
Think of it as one option next to the free ones. A free app gives you a quick number. A bureau's free yearly report gives you the full record. Credit Insights is for readers who want that record explained in plain words, with next steps attached. Experian also gives its own free Experian report once a year, so you can take that first.
If your real problem is too many EMIs, there is another route. When several EMIs stretch your month, FREED's Debt Consolidation Program is built for people who can still repay. It is for readers who are paying every EMI but want one simpler payment.

Mohit Juneja
Mohit Juneja is FREED’s Content & Communication Lead with 12+ years of experience across content, media, advertising and digital communications. He holds a postgraduate diploma in Communications from Xavier Institute of Communications, Mumbai, and has worked with organisations including NDTV, The Indian Express, McCann Worldgroup and NABARD.
At FREED, he leads content and communication across loan management, debt resolution, debt consolidation and financial well-being. His work combines research, storytelling and consumer-focused communication to make complex financial topics easier to understand and act on. He has also scripted and produced 11 documentaries on rural development and agriculture for NABARD, with film's selected for the Mumbai International Film Festival.
mohit.juneja@freed.care

FREED is India's trusted loan management platform. Founded in 2020 and headquartered in Gurugram, FREED has counselled 20 lakh+ people on personal loans, credit cards, and app loans. FREED charges fees only on successful settlement, not upfront. FREED does not handle secured loans (home loans, car loans, gold loans).
Media Mentions