Let’s talk
about Loans







75,000+
Customers served

₹450 Cr+
Total savings

4.8/5
Google rating
Browse Topics
5 CategoriesCredit Score
CIBIL Score Required for Personal Loan Approval
CIBIL score required for personal loan approval isn't one fixed number. There's no universal CIBIL threshold for personal loan approval. Each lender applies its own underwriting policy, and score is only one factor among several, alongside income, existing obligations, and repayment history. Score alone doesn't decide it. Income, job stability, and existing EMI load matter too.
CIBIL Member: What It Means and Which Lenders Report Your Data
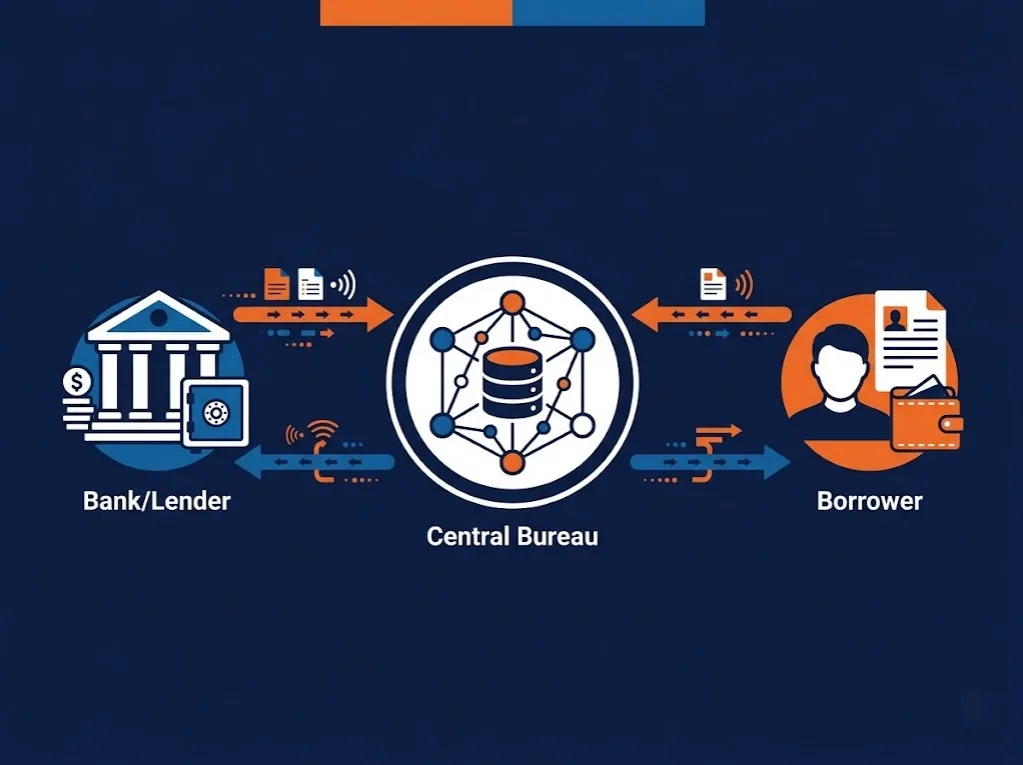
A CIBIL member is an organisation that is authorised to participate in TransUnion CIBIL's credit-information system and, where applicable, furnish and access credit information under the applicable regulatory framework. Members both contribute borrower information monthly and access CIBIL reports when deciding on loans. TransUnion CIBIL has over 5,000 members, including banks, financial institutions, NBFCs and HFCs. From January 1, 2025, credit information is required to be updated on a fortnightly basis, or more frequently where agreed between the credit institution and the credit information company. Only borrowal accounts get reported, loans and credit cards. Savings accounts and fixed deposits stay private. Once reported, your payment history becomes visible to every CIBIL member.
How to Build Your Credit Score From Scratch or After Debt
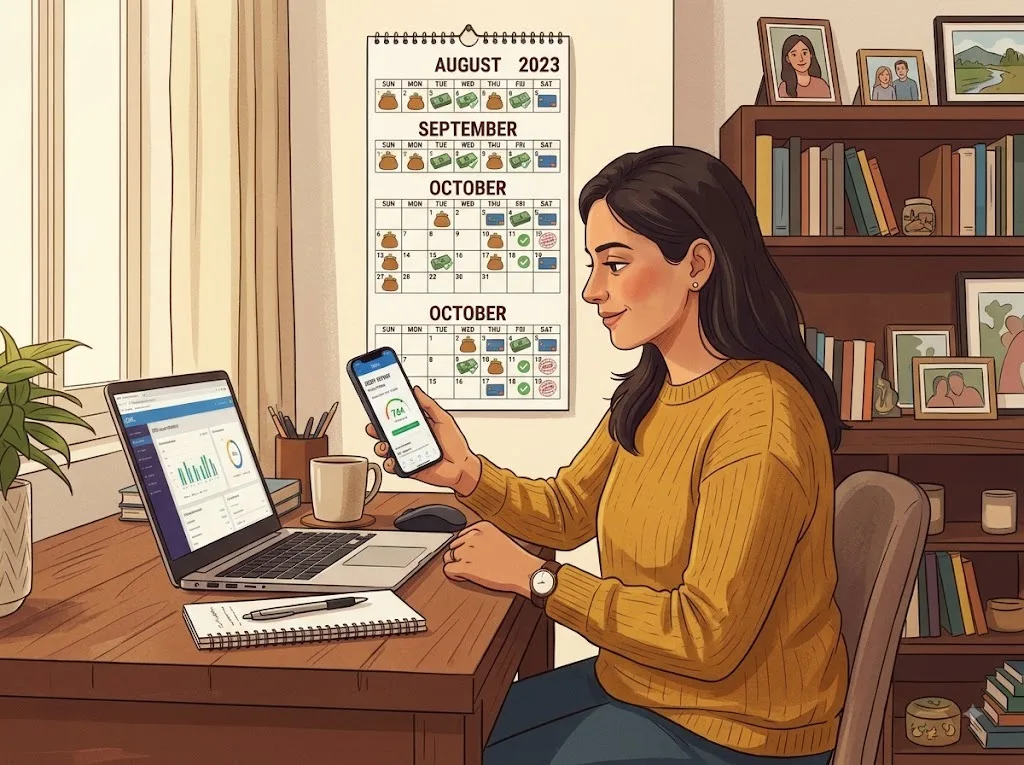
Building your credit score means creating a payment history that lenders trust, by using credit responsibly over time. It can take time for enough reported credit activity to build a score. The exact timing depends on when your lender reports your account information and whether the bureau has sufficient data to generate a score. After debt, recovery from default or settlement usually needs 12 to 24 months of clean behaviour, on-time payments, low credit card usage, no new loan applications. The score starts low and climbs steadily with each on-time payment, not quickly.
Bajaj Finserv CIBIL Score Requirements: What Lenders Actually Check
Bajaj Finserv does not assess a personal-loan application on CIBIL Score alone. Your credit history is one part of the assessment, alongside income, existing debt obligations, repayment history, employment or business stability and other eligibility criteria. Bajaj Finserv doesn't publish one fixed minimum. Different official pages and applicant categories cite figures ranging from 650 to 685, and third-party trackers report requirements as high as 750 for salaried applicants. Treat any single number here as a rough reference point, not a guaranteed cutoff; check the current eligibility page for the figure that applies to your applicant type before assuming where you stand.
How to Check CIBIL Score With Aadhaar Card
Aadhaar alone may not be enough to complete a CIBIL Score and Report request. The online process asks for personal details and an identifier, followed by identity authentication. Your PAN card is the mandatory identifier CIBIL uses to pull your credit history. Aadhaar may be used as an identity/KYC document in some verification contexts, but the exact documents requested can depend on the CIBIL authentication process.
CRIF Credit Report: India's Other Credit Bureau, Explained
A CRIF credit report is a detailed credit history compiled by CRIF High Mark, one of 4 RBI-licensed credit bureaus in India alongside CIBIL, Experian, and Equifax. It includes your accounts, payment history, and a 3-digit score between 300 and 900, and is especially detailed for NBFC and microfinance loans.
Credit Utilisation Ratio: How Much of Your Limit You Should Use
Credit utilisation ratio is your outstanding credit card balance divided by your total credit limit, shown as a percentage. Keeping it below 30%, ideally 10-20%, signals responsible credit use to lenders and protects your CIBIL score.
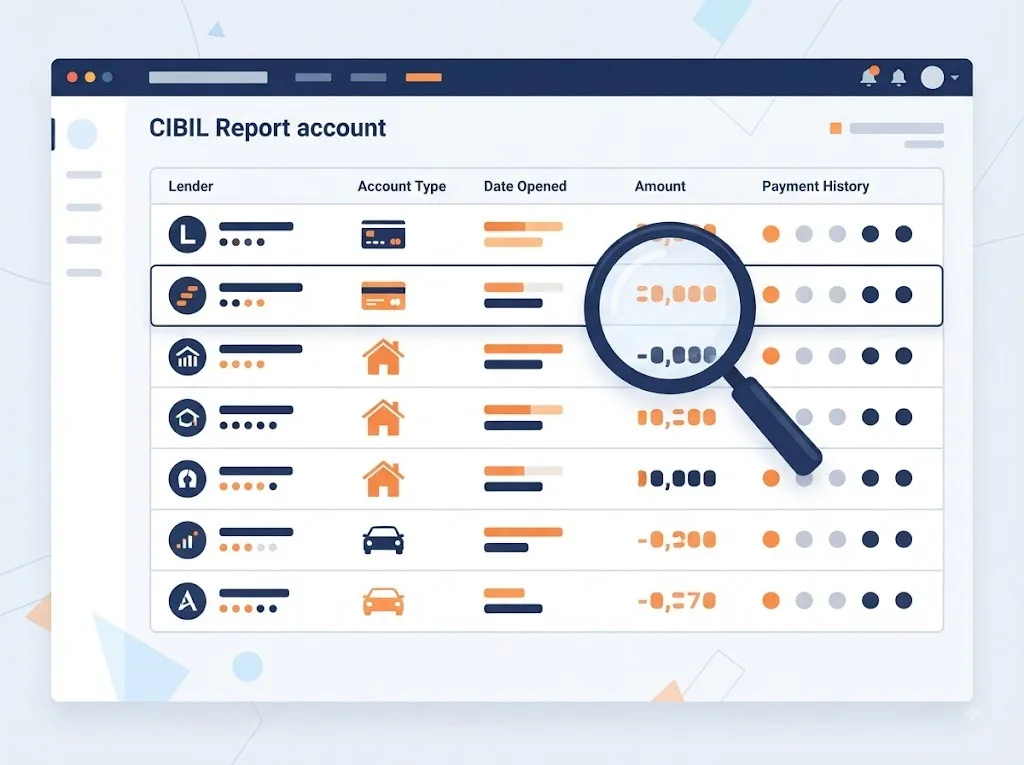
CIBIL Report Details: What Each Section Means
Your CIBIL Report combines your CIBIL Score with personal, contact, employment, account and enquiry information. The Accounts and Enquiries sections contain the credit-behaviour information used to calculate your score, while the other sections help identify and contextualise your credit profile. The report brings together your identity, employment and credit information. Your CIBIL Score is calculated from credit-behaviour information, particularly the Accounts and Enquiries sections.

Make smarter financial decisions.
Loan Settlement | Loan Consolidation | Credit Insights | FREED Shield
Get Started