Let’s talk
about Loans


75,000+
Customers served

₹450 Cr+
Total savings

4.8/5
Google rating
Browse Topics
5 CategoriesCredit Score
How to Find Your CIBIL Score and Locate Lender Details on Your Report
Finding your CIBIL score just means pulling your report from CIBIL, Experian, or Equifax. The harder part for many people is recognizing the lender names listed against each account, since the legal entity that actually lent you money often isn't the app or brand name you remember using. This guide covers both, briefly on the score, mostly on making sense of the lenders.
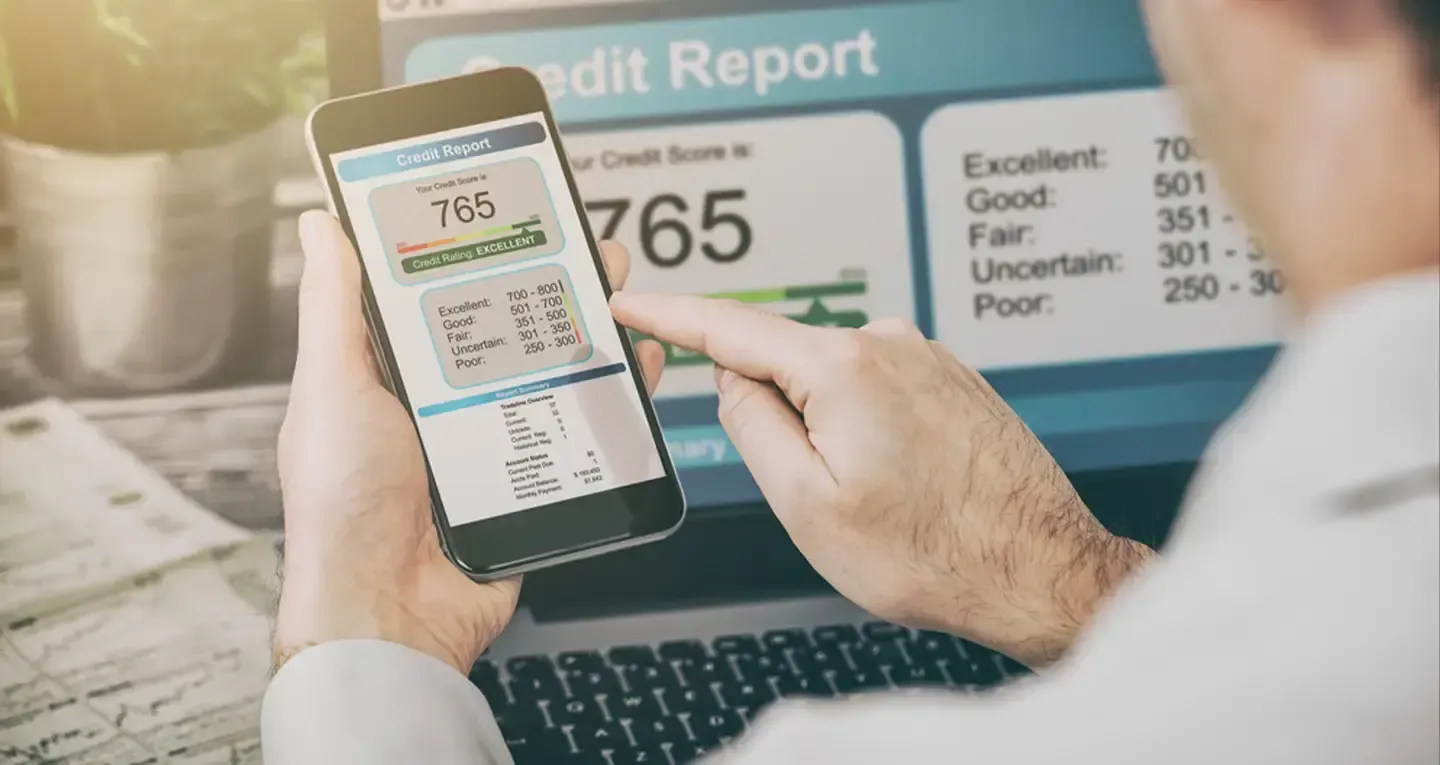
Credit Score Ranges Explained: A Complete, Simple Guide
Recognize how your credit utilization, CIBIL score, and credit score range impact the approval of credit cards, house loans, and personal loans.
776 CIBIL Score: Is It Good Enough for a Loan?
A 776 CIBIL Score is generally considered a strong score on India's 300–900 scale. It can support your chances of getting competitive credit terms, but lenders may use different internal eligibility criteria. It's usually strong enough for an unsecured personal loan, most credit cards, and competitive rates on secured loans, though a few premium products and larger loan amounts can still depend on income and other factors.
Consumer Durable Loan for Low CIBIL Score
A consumer durable loan is a small, unsecured EMI loan used to buy things like a refrigerator, TV, laptop, or smartphone. Approval is usually easier than a personal loan, but your CIBIL score still decides which lender says yes and what it costs you.
How to Improve Credit Score Fast: What Works, What Takes Time, and What to Ignore
Improving your credit score fast means taking the highest-impact actions first, in the right order. Some actions may begin reflecting in your credit profile sooner than others, depending on the lender's reporting cycle and your individual circumstances. Other changes require consistent repayment behaviour over time. A few things, like reversing a default or removing a genuine "Settled" tag, cannot be rushed at all. This guide explains which actions may have a quicker effect and which generally take longer.
CIBIL Defaulter List 2026: Does It Really Exist? How to Check & Remove Your Name
No. CIBIL does not keep a public defaulter list. Neither does Experian, Equifax or CRIF High Mark either. What you do have is your CIBIL report and any missed EMI, settlement or write-off remains on it for 7 years. Every bank or financial company will look at this before they give you your next loan. That’s what a “CIBIL defaulter” actually means, people say.
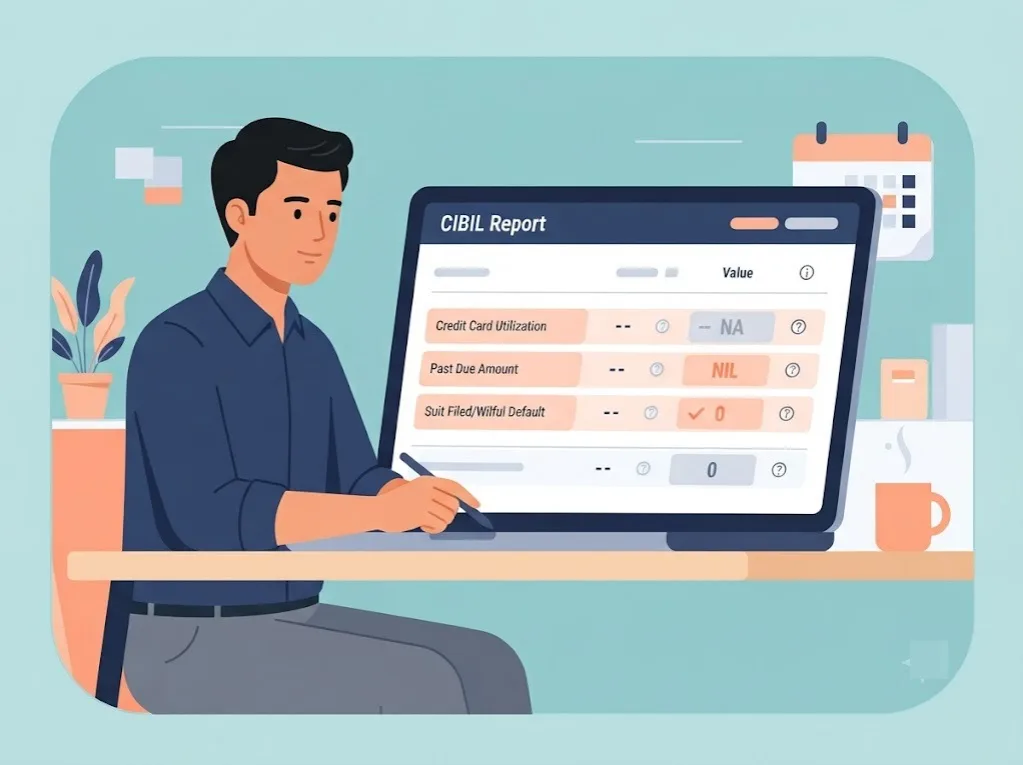
Reading Your CIBIL Report: What 'NA/NIL' and Special Account Facilities Mean
In a CIBIL report, NA can indicate that a particular field is not applicable or has not been reported for that account, while NIL may indicate that the reported value is zero. The exact presentation can vary by field and account type. Both are normal, expected entries on most reports. This guide covers exactly which fields show each, plus what "special account facilities" like overdrafts and add-on cards look like when they appear.
How to Update CIBIL Score After Loan Closure or Settlement
You paid the last EMI. The bank confirmed your loan is closed. You're feeling lighter already. But you open the CIBIL app, and the same loan is still showing as "active". Or worse, your score hasn't moved a single point. This is one of the most confusing moments for any Indian borrower, and you're not alone in feeling stuck here.

Make smarter financial decisions.
Loan Settlement | Loan Consolidation | Credit Insights | FREED Shield
Get Started