Loan Settlement Help in Delhi NCR: What Borrowers Should Check
A loan settlement agency in Delhi may help borrowers present a settlement proposal to a bank or NBFC for consideration. The lender decides whether to accept the proposal and sets the terms. Before engaging an agency, verify its legal identity, fees, agreement and explanation of possible credit-report effects. It cannot guarantee the result, because the bank decides. A genuine agency shows its office, explains fees in writing and tells you about the CIBIL impact before you start.
Mohit Juneja
Reviewed by FREED India, Debt Resolution Specialists
 4.7/5
 ₹3,200Cr+
 20,000+
 20,00,000+4.7/5₹3,200Cr+20,000+20,00,000+
key Takeaways

A loan settlement agency in Delhi cannot promise a result. The bank decides.
RBI says each bank or NBFC sets settlement terms under its own Board-approved policy.
Delhi Lok Adalats charge no court fee, and the award is binding and non-appealable, says DSLSA.
A Settled status can stay on your credit report for up to 7 years.
Visit the office, get fees in writing and never pay a personal account.
What Does a Loan Settlement Agency in Delhi Actually Do?
The recovery calls started three weeks ago. Some come in the morning, some late in the evening. You open your phone and type “loan settlement agency near me.” The results show many names, many promises and many phone numbers. You cannot tell which one is real. That feeling is common, and it is a fair reason to slow down before you pay anyone.
Start with what the service actually is. A loan settlement agency talks to your bank or NBFC for you. It prepares the documents, puts your case to the bank and tries to agree a lower full-and-final amount. “Full and final” means the bank accepts that amount and treats the account as settled.
Three points to remember
It works only on unsecured loans. That means personal loans, credit cards and app loans. It does not cover home loans, car loans, gold loans or other secured loans.
It cannot force a bank to agree. The bank decides whether to settle and on what terms. An agency can only present your case.
You approve any offer before payment. A genuine agency never pays or commits on your behalf without your say.
Does being in Delhi NCR change the rules?
No. If you live in Delhi, Noida, Gurugram, Ghaziabad or Faridabad, the same national rules apply to your bank. What changes is where you can visit, file and attend. You can walk into an office in Delhi NCR to check it. You can attend a Lok Adalat in your district. Those local steps matter, and this guide covers them.
What this guide will and will not do
We do not name or rank any agency. We do not claim any agency is best. Instead, we give you checks you can run yourself. For the wider picture, read our guide to loan settlement companies in India. For a factual look at one program, see FREED’s Debt Resolution Program.
First, the question many borrowers skip: why are so many people in Delhi NCR looking for this help? The next section answers it without blame.

Not Sure Where to Start With Your Loans?
Share your loan details and get a free assessment from FREED’s counsellors.
Start My Debt AssessmentWhy Do Delhi NCR Borrowers Look for Loan Settlement Help?
Nobody searches for settlement help because things are going well. Most people reach this point after months of pressure. Here are four real triggers.
Several loans at once. A personal loan, a couple of app loans and a card balance can add up to EMIs that eat most of your pay.
Credit card dues growing on interest. When you pay only the minimum, the unpaid part keeps growing. A small bill can become a large one.
A job or income break. A layoff, a business slowdown or a medical bill can cut your income while your EMIs stay the same.
Recovery calls after missed EMIs. Once EMIs are missed, the calls begin. The calls add stress and make clear thinking harder.
What banks look at
Lenders assess settlement requests according to their applicable policies and the borrower’s circumstances. Settlement may be considered when full repayment is not feasible, but eligibility and approval depend on the lender’s assessment. Borrowers should compare available repayment options before committing to a settlement arrangement.
If you are still paying
If you can still repay each month, a different route may fit better. Many borrowers who are stretched thin do not need settlement at all. We cover that route in a later section.
How to know where you stand
Ask yourself three plain questions:
Can I pay my EMIs this month without borrowing again?
Is more than half of my take-home pay going to EMIs?
Have I started to miss payments?
If the answers are “no,” “yes” and “yes,” you may be at the stage where settlement is worth understanding. Our guide on what loan settlement is and when to consider it explains the full picture.
We have not used local numbers in this guide, because we did not find a verified source for Delhi NCR borrower statistics. Please be careful with any agency that quotes exact local figures without a source.
What Are the Red Flags in a Loan Settlement Agency in Delhi?
A real agency can fail one point because of poor presentation. A fake one usually fails several. Watch for these seven.
A guaranteed waiver before looking at your loans. No one can promise a fixed discount before seeing your accounts, because the bank decides.
A large upfront fee, or a request to pay a personal account. Money sent to a person’s account is hard to trace and hard to recover.
Advice to stop all EMIs and calls with no written plan. Stopping payments without a plan can raise your charges and trigger legal notices.
A Delhi address you cannot visit, or a shared or virtual one. If the office is closed, hidden or shared with many firms, be careful.
No company name, registration details or named leaders. A business that hides who runs it gives you nowhere to turn if things go wrong.
Reviews that look copy-pasted or uniform. Real reviews differ in tone, length and detail.
A countdown, such as “offer ends today.” Pressure to decide in hours is a classic scam tactic.
How to use this list
Count the flags. One flag deserves a question. Two or three deserve a pause. Four or more means walk away. Do not pay anyone while you are still unsure.
How to Check a Loan Settlement Agency in Delhi in 7 Steps?
Follow these seven steps in order. They take about a day, and they can save you from a costly mistake.
1. Find the legal company name.
Look for it on the website and in the agreement. A trading name alone is not enough.
2. Check its registration.
Search the name and CIN (the company’s registration number) on the Ministry of Corporate Affairs website.
3. Visit the office.
Confirm the address in Delhi NCR is real, staffed and not shared with many unrelated firms.
4. Ask for fees in writing.
Fees should depend on a successful settlement. Ask exactly when each payment falls due.
5. Ask about CIBIL impact.
A genuine agency explains the Settled status upfront, before you sign.
6. Read the agreement fully.
Check refunds and cancellation terms before you sign. Do not sign a blank or half-filled paper.
7. Confirm any offer with your bank.
Use the number printed on your loan statement, not one the agency gives you.
On visiting the office
An in-person visit is a good test, but it is not required. A genuine online-first agency should still show a verifiable address and a named company. If an agency works only by phone and refuses to share any address, treat that as a red flag.
What to carry when you visit
A list of your loans and the amount due on each.
A notebook for names, dates and promises.
A phone to photograph the signboard and office, if allowed.
For the longer nine-point version, read how to evaluate a loan settlement agency before signing.

FREED Expert Tip
Before you sign, ask the agency to put its fee terms and your refund rights in writing.
Book My CallCan You Settle Through a Lok Adalat in Delhi Instead of Paying an Agency?
Yes, for some borrowers this free route is worth knowing. A Lok Adalat is a forum where parties settle disputes by agreement. The Delhi State Legal Services Authority (DSLSA) holds Lok Adalats across Delhi’s districts.
What DSLSA says
There is no court fee.
If you have already paid a court fee and the dispute settles, the fee is refunded.
The award is binding, with the status of a civil court decree, and it cannot be appealed.
What it handles
DSLSA’s page says it settles pending and pre-litigation civil cases, and that it has handled recovery matters for banks. Pre-litigation means a matter that has not yet gone to court.
How it works in practice
The bank must agree to the matter being heard.
The bank decides on the terms.
It tends to suit borrowers whose accounts are already overdue.
You usually attend in person, with your documents.
The limits you must know
There is no guarantee the bank will attend or agree.
The award is final, so read every line before you accept it.
Schedules change. Check the current Lok Adalat schedule on dslsa.org. We do not list dates here.
Agency or Lok Adalat?
A Lok Adalat costs no court fee, but it needs your time and effort. An agency does the work for you, at a fee. Neither can force a bank to agree. Read our practical guides on how to settle a bank loan at Lok Adalat and Lok Adalat loan settlement to decide.

What the Law Says
In a Delhi Lok Adalat there is no court fee, and the award is binding with the status of a civil court decree and cannot be appealed.
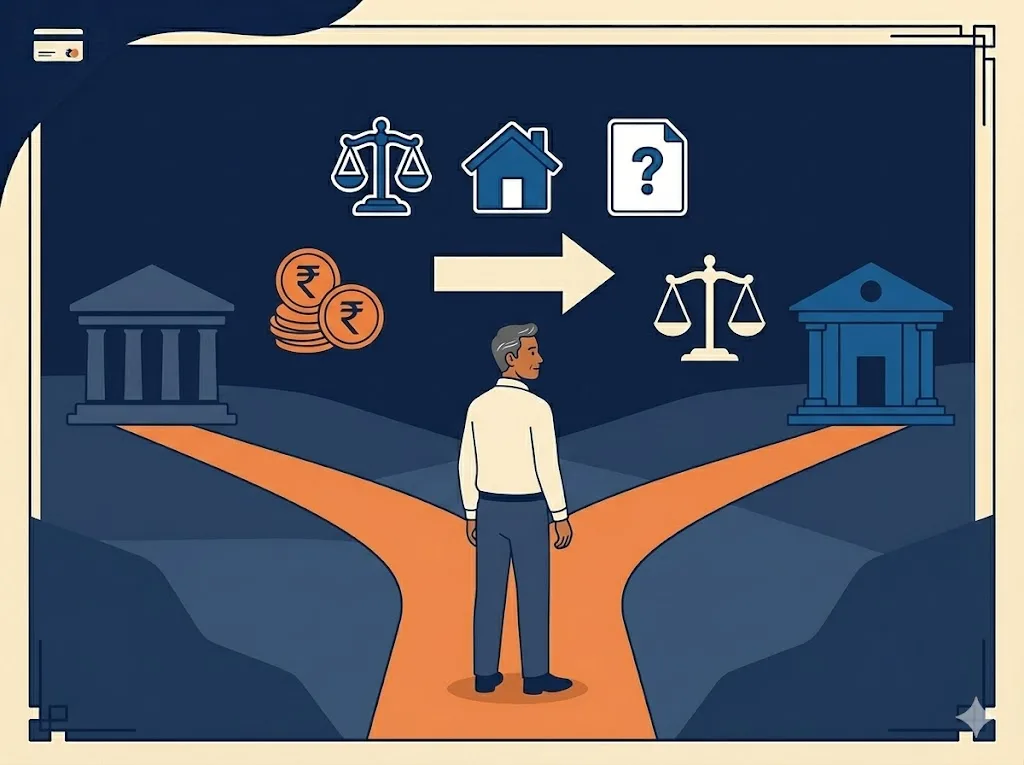
Talk to a CounsellorAgency, Lawyer, Lok Adalat or Your Bank: Which Route Fits You?
The order of options matters. Start with the gentlest one.
If you are still paying
If you can still pay each month but your EMIs feel too heavy, settlement may not be the right step. FREED’s Debt Consolidation Program is designed for this case. It merges eligible unsecured loans into one lower EMI on one date. Read what debt consolidation is to understand it. To check whether your EMIs are too heavy, try the EMI Score.
If you genuinely cannot repay
Here are the four routes side by side.
Route | Who does the work | Typical cost | Main limit |
Talk to your bank directly | You | No service fee | Takes time and paperwork; you follow up |
Loan settlement agency | The agency, for you | Fee tied to a successful settlement | Verify first; bank still decides |
Lawyer | The lawyer | Professional fees | Better when a legal notice or case is involved |
Lok Adalat in Delhi | You, with the bank | No court fee | Bank must agree; the award is final |
What RBI’s framework says
RBI’s framework sets requirements for regulated entities handling compromise settlements. Lenders apply their approved policies within the applicable regulatory requirements. The classification of an arrangement depends on the precise terms and the relevant directions, so borrowers should ask their lender to confirm the settlement terms and reporting treatment in writing.
How to choose
If you have time and the paperwork does not scare you, start by speaking to your bank. Read how to negotiate a personal loan settlement with your bank.
If you want help and the agency passes all seven checks, an agency may fit.
If you have received a legal notice or a case is filed, a lawyer is the safer choice. See loan settlement lawyers in India.
If your account is overdue and you want a free forum, a Lok Adalat may fit.
Rates and ranges shown are indicative. Final terms decided by the bank. FREED is not a Loan Provider. No outcome is guaranteed. Please verify directly with your bank.
How Does FREED Handle Loan Settlement for Delhi NCR Borrowers?
The FREED Loan Settlement Plan (Debt Resolution Program, “Settle My Loans”) is for borrowers who genuinely cannot repay their unsecured loans in full.
Where FREED is based
FREED’s corporate office is in Gurugram, in Delhi NCR. The process runs through the app and counsellor calls, so borrowers across NCR can use it without travelling. We do not promise walk-in service.
How the process works
FREED assesses your full financial situation. This includes your loans, income, essential expenses and repayment capacity.
You get a personalised plan. The plan is built around your real finances.
You build monthly savings in a Special Purpose Account (SPA). The SPA is held by an independent trustee, in your name. FREED cannot touch it without your approval.
FREED negotiates with the bank. Once the fund is large enough, FREED negotiates, and you accept or decline the offer.
Be clear about time. The process takes time. Savings build first, then negotiation follows. It is not instant, and we do not claim it is.
Transparency
The fee is charged only when a settlement is completed.
If a bank refuses to settle, FREED does not charge the service fee and refunds the initial evaluation fee.
A Settled status can stay on your report for up to 7 years.
Waivers of up to 50%* may apply. Final terms are the bank’s decision.
Track record. FREED has settled 20,000+ accounts, counselled 20,00,000+ customers and managed ₹3,200 Cr+ of debt.
To learn more, see the Debt Resolution Program.
Rates and ranges shown are indicative. Final terms decided by the bank. FREED is not a Loan Provider. No outcome is guaranteed. Please verify directly with your bank.
Cannot Repay Your Loans in Full?
Get a free assessment and a clear plan, with no pressure.
Start My Debt AssessmentWhat Will Loan Settlement Do to Your CIBIL Score?
Be ready for the honest answer. A settled account may be reported differently from an account repaid in full. This can affect how future lenders assess a credit application, although the impact varies by borrower and lender. Confirm in writing which obligations the settlement covers, what conditions remain and how the account will be reported. After completing the agreement, keep the settlement confirmation and check your credit report for accuracy.
What “Settled” means in practice
The bank has accepted less than the full amount as full and final.
Your report shows the account as settled, not closed in full.
New lenders may treat this as a risk signal.
What settlement does for you
Once the bank confirms the settlement in writing, recovery on that account ends. The calls and notices for that loan should stop. That relief is real, and it is why some borrowers choose this route when nothing else is possible.
A trust test
A genuine agency tells you all this on day one. If an agency says there is no effect on your score, or avoids the question, treat that as a warning. Ask for the CIBIL impact in writing.
We do not quote score-drop numbers, because they vary by person and by report. To see where you stand today, Check Credit Insight. For a full explanation, read loan settlement: meaning, process and CIBIL impact.
Are You in a Loan Trap? Quick Check
Move the slider to your total EMIs as a % of monthly salary. See your debt stress level instantly.
EMIs as % of Monthly Salary
What Helps During the Loan Settlement Process?
Once you start, a few habits protect you. Each one has a reason.
Keep every document and receipt. Records decide disputes later.
Never pay a personal account. Pay only to the bank’s own account, and keep the receipt.
Do not sign a blank paper. A blank signature can be filled in against you.
Get every offer in writing from the bank. A phone promise is not proof.
Keep paying essential bills first. Rent, food, medicine and school fees come before settlement savings.
Ask for the settlement letter after payment. This letter is your proof that the account is settled.
Check the credit report later. Make sure the update shows the right status.
A simple tracker you can copy
What | Date | Proof saved? |
Offer received in writing | ||
Amount paid | ||
Settlement letter received | ||
Credit report checked |
On recovery pressure
If calls turn abusive, or an agent visits without following protocol, FREED Shield is open to everyone. It helps you document and report the behaviour. It does not stop calls. Read our guide on RBI recovery agent rules to know where the line is.
It is not too late to ask for help. Step by step, with the right checks, a hard situation can move toward a clear end.
Ready to Resolve Your Loans?
See how a structured loan settlement plan could work for you.
Settle My LoansSourcing and Verification
Claim | Source | Link |
No court fee; fee refunded if the dispute settles in Lok Adalat; award binding, with civil court decree status, non-appealable | DSLSA, “What are the special features of Lok Adalat?” | https://dslsa.org/hrf_faq/what-are-the-special-features-of-lok-adalat/ |
DSLSA settles pending and pre-litigation civil cases across Delhi’s districts; has handled bank loan recovery matters; continuous Lok Adalats (page is undated) | DSLSA Lok Adalat activities page | |
Board-approved settlement policy; terms set by the regulated entity; cash settlement; over 3 months treated as restructuring (paras 1, 2, 3, 7) | RBI/2023-24/40, Framework for Compromise Settlements and Technical Write-offs, 8 June 2023 | https://www.rbi.org.in/Scripts/NotificationUser.aspx?Id=12513 |
FREED corporate office in Gurugram | FREED website footer |

Mohit Juneja
Mohit Juneja writes educational content at FREED on debt management, credit scores, loan repayment, and borrowing best practices. His content is shaped by expert insights and industry knowledge, helping readers better understand their financial options and make informed decisions.
mohit.juneja@freed.care

FREED is India's trusted loan management platform. Founded in 2020 and headquartered in Gurugram, FREED has counselled 20 lakh+ people on personal loans, credit cards, and app loans. FREED charges fees only on successful settlement, not upfront. FREED does not handle secured loans (home loans, car loans, gold loans).
Media Mentions