Let’s talk
about Loans


75,000+
Customers served

₹450 Cr+
Total savings

4.8/5
Google rating
Browse Topics
5 CategoriesLoan Consolidation
Using a Personal Loan to Consolidate Debt: Does the Math Work?
Using a personal loan for debt consolidation means taking one new loan to pay off several existing debts, credit cards, other personal loans, at once. Whether it actually saves money depends on comparing the total remaining cost of your existing debts with the total cost of the new loan, including interest, fees and any applicable prepayment charges. It isn't automatic, and the math is genuinely worth checking before applying.
Personal Loan Consolidation Companies: What to Know Before You Decide
Personal loan consolidation companies help borrowers combine multiple existing loans or credit card dues into a single new loan with one EMI, usually at a lower overall interest rate. They work by matching you to a lender, not by lending you money directly themselves, an important distinction most people miss.
What Loan Consolidation Means: How It Works and When It Is Not Enough
Five EMIs. Five due dates. Five reminder calls before the 10th. By the time salary hits your account, half of it is already spoken for. Loan consolidation is one fix people hear about and it works for some people in some situations. But it is not the only option, and it is not always the right one. Let's break it down properly.
Myth vs Reality: What People Get Wrong About Consolidating Debt
Heard that debt consolidation is risky? Or that it ruins your credit score? Most of what people believe about it is simply not true. Let's bust the myths - one by one - in plain simple language.
Joint Debt Consolidation Loan With Your Spouse: Is It a Good Idea?
A joint debt consolidation loan is one new loan taken by you and your spouse together. It pays off your existing loans and cards. You get one EMI. Both of you are fully responsible for it, and it shows on both credit reports. It can help when one income is not enough.
Debt Consolidation Plan Money Lender: What It Means
Debt consolidation plan money lender usually means one new loan from a non-bank lender, used to repay several dues. In India, banks and NBFCs are regulated by RBI. Money lenders fall under state laws. Who lends to you decides your rate, your paperwork and your protection.
Debt Consolidation Loan No Credit Check: What It Means
A debt consolidation loan with no credit check is a loan offer that says it will not look at your credit record. In India, regulated lenders must still assess your ability to repay and report digital loans to credit bureaus. An offer with no checks at all is a warning sign, not a shortcut.
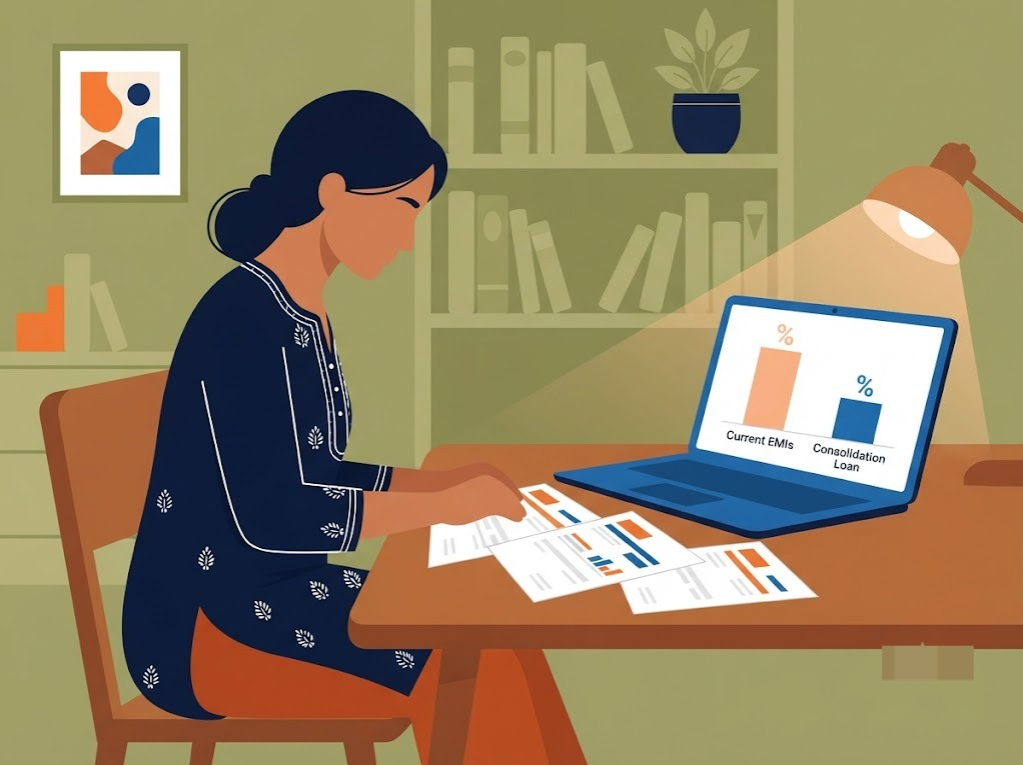
Average Debt Consolidation Loan Interest Rate in India
The average debt consolidation loan interest rate has no official figure in India. Comparison sites commonly report a wide range, from about 10% to 24% a year for a personal loan used to repay other dues. Your own rate depends on your profile, the loan size, and the tenure.

Make smarter financial decisions.
Loan Settlement | Loan Consolidation | Credit Insights | FREED Shield
Get Started