How to Get a Debt Consolidation Loan With Bad Credit: A Step-by-Step Guide
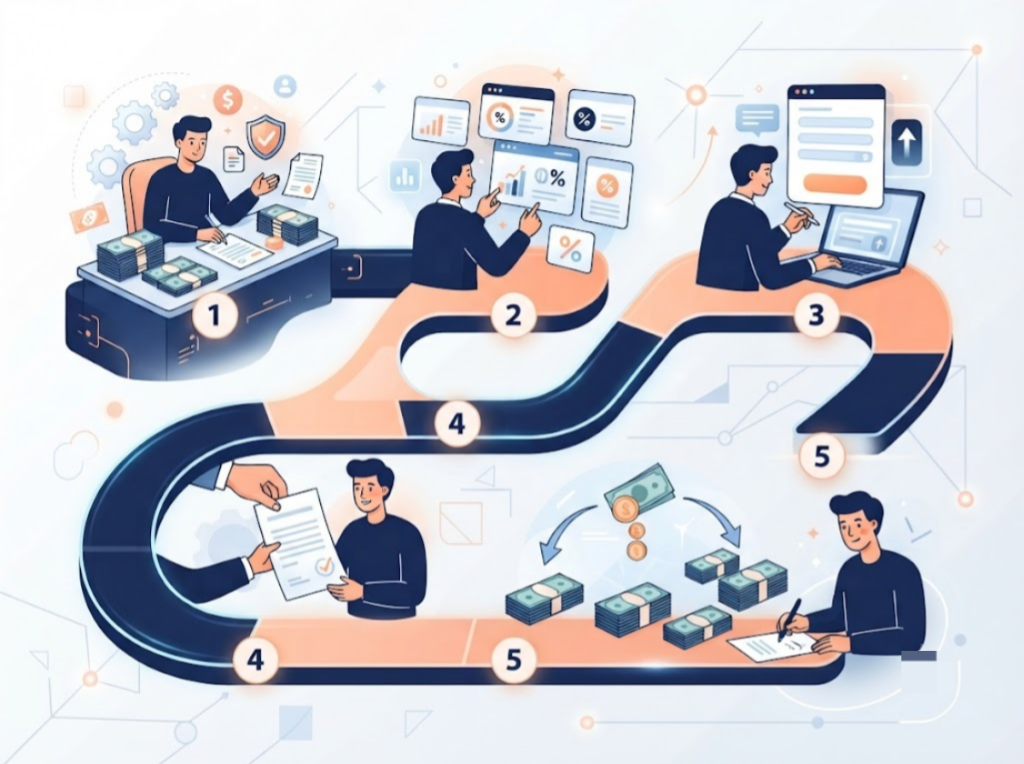
Getting a debt consolidation loan with bad credit follows the same five broad steps as any application: check your score, total your debt, soft-check eligibility, apply, then pay off and close. But each step has a specific bad-credit wrinkle worth knowing before you start, not after a rejection.
Mohit Juneja
Reviewed by FREED India, Debt Resolution Specialists
 4.7/5
 ₹3,200Cr+
 20,000+
 20,00,000+4.7/5₹3,200Cr+20,000+20,00,000+
KEY TAKEAWAYS

Knowing your exact score, not an estimate, before you start determines whether you're realistically applying to a bank, an NBFC, or a secured route.
Totaling your debt precisely, principal and accrued interest, matters more with bad credit since lenders scrutinise the request amount more closely.
A soft-check saves a hard inquiry you can't afford to waste. Each one further pressures an already-strained score.
The order you apply in, and what you do immediately after disbursement, changes whether this process actually improves your situation or just adds a new complication.
What This Guide Covers
This is the expanded, step-focused companion to the broader bad-credit consolidation picture: why bad credit makes approval harder in the first place, and what to do specifically if you're rejected. Our complete guide to consolidating your loans covers that wider context, including the different lender types and how they weigh a lower score.
This piece stays on the mechanics. It walks through each of the five steps with the kind of specific detail a one-line summary can't give: what exact number to check, what exact figure to calculate, and what exact order to apply in.
If you haven't yet confirmed consolidation is even the right route for your situation, start with the fuller piece first. This guide assumes you've already decided to apply and just need to know how to do it properly with a score that's working against you.

Freed Expert Tip
Read all five steps once before starting any of them. Knowing what step 4 requires changes how you should approach step 1.
Talk to FREED's TeamStep 1: Check Your Actual Score, Not an Estimate
This step matters more with bad credit specifically than it would otherwise. If your score has genuinely dropped, knowing the exact number, not a rough sense of "it's not great," determines which route is realistic: an unsecured bank loan, an NBFC option, a secured route against property, or FREED's matching program.
Here's why the exact figure matters. A borrower who assumes their score is around 600 but discovers it is materially lower may find that fewer lenders or loan products are available. Conversely, a higher score may broaden the range of products they can consider, depending on the lender's criteria. Someone who assumed 600 but is actually 640 has real options that most people in that range don't realise exist. The ten or twenty points either side of a rough guess can be the whole difference.
Pull your report directly rather than relying on an app's rough estimate. FREED's Credit Insights pulls your Experian report along with what's actually affecting the number, so you're working from something real. Note the exact figure before moving to step 2.
Step 2: Calculate Your Total Outstanding Debt Precisely
Precision matters more here than a rough total would suggest. A lender assessing a bad-credit application scrutinises the requested amount more closely, and a request that does not match your current debt statements may lead to additional questions or document requests during the application process.
Here's a worked example. Say you have three unsecured debts: a personal loan at ₹1,80,000 outstanding, a credit card at ₹95,000 including accrued interest, and a BNPL balance at ₹22,000. That totals ₹2,97,000. This precise figure, not a rounded "around ₹3 lakh," is what should go on the application. Using current statements rather than a rounded estimate helps ensure that the amount requested is consistent with the outstanding balances shown in your documents.
Pull a current statement for every debt rather than relying on memory or an old figure. Interest accrues. An outdated total undercuts the very application you're trying to strengthen.
Step 3: Soft-Check Before Any Hard Application
This step is especially critical with bad credit. Each hard inquiry causes a small drop on its own, but on a score that's already stretched, several inquiries in a short window from rejected applications can meaningfully compound the problem.
A soft-check gives an indicative sense of eligibility without a hard credit pull, letting you see where you'd likely qualify before committing to a formal application anywhere. It costs you nothing to look first, and it tells you exactly where step 4 should actually start.
Use a soft-check route, whether a specific lender's own tool or a matching program that checks eligibility across several lending partners at once, before submitting anything that triggers a hard inquiry. FREED's Debt Consolidation Program runs this kind of check across its partner network in one pass, rather than one lender at a time.

Sorting out unsecured debt while dealing with this?
Check eligibility across multiple lenders with one soft check.
Check your optionsStep 4: Apply to One Lender at a Time, in the Right Order
The order that actually makes sense with bad credit starts with whichever route the soft-check suggested is most likely to approve, rather than starting with the most desirable rate and working down. Submitting a full application to a lender that may not fit your profile can result in an unnecessary credit inquiry, depending on the lender's process.
Sequencing matters specifically here because each rejection makes the next application look slightly worse to the following lender. Space applications out and don't apply broadly hoping one sticks. That approach does more damage than it saves in time.
If the soft-check pointed to an NBFC or a secured route as the realistic option, apply there directly rather than starting with a bank likely to decline. Following the actual signal beats following your own preference for a lower headline rate.
Step 5: Disburse, Pay Off, and Get Every NOC
This final step matters as much as approval itself. Once the new loan disburses, the funds need to go directly toward closing every existing debt on the list, not partially, and not toward anything else.
The documentation discipline here protects you specifically in a bad-credit situation. Request a closure confirmation, NOC, no-dues certificate, or other applicable proof from each lender after repayment. These read very differently to a future lender, and the difference isn't automatic just because you paid. Our piece on what happens when you're reported to a credit bureau covers exactly how that "Closed" status actually gets reflected.
Don't consider the process finished until every old account shows correctly closed, not just paid, on your report. A payment that hasn't been reflected yet still looks open to anyone checking.
If Every Step Still Ends in Rejection
Following these five steps carefully improves the odds but doesn't guarantee approval when a score is genuinely low. That's a real possibility worth planning for rather than being surprised by.
A few paths remain. Secured consolidation, tenure extension, or restructuring with an existing lender are worth exploring next. For genuine, sustained inability to repay, settlement is the separate, structured last resort. Settlement is not something a borrower chooses out of preference. Banks only consider it when someone is in genuine financial difficulty and is truly unable to repay in full. FREED's Debt Resolution Program is that separate, later-stage path, and our guide to the settlement letter format covers what the paperwork actually looks like if it comes to that.
How FREED Helps Through This Process
FREED's Debt Consolidation Program may support eligible applicants through the assessment and consolidation process, subject to the applicable lender and programme requirements. This reduces the number of individual hard-inquiry applications a bad-credit borrower would otherwise need to make on their own, one lender at a time, hoping each one lands.
No specific score floor, rate, or lending partner can be guaranteed as fact. What FREED does is run the sequencing described in these five steps on your behalf, so you're not the one absorbing a string of rejections while you figure out the right order yourself.
Tips Through Each Step
Confirm your exact score before assuming which route applies to you. A guess in either direction sends you toward the wrong lender first.
Total your debt precisely, using current statements, not memory. A rounded figure is the easiest, most avoidable reason for a follow-up delay.
Soft-check before any hard application, every time, even when you feel confident about the outcome.
Apply in the order most likely to succeed, not the order of preference. The lender with the nicest rate isn't useful if it's also the least likely to say yes.
Don't consider the process done until every old account shows properly closed.
Freed Expert Tip
Keep every NOC and closure confirmation in one folder as you go, not scattered across emails. You'll want them together if anything needs confirming later.
Talk to FREED's Team
Mohit Juneja
Mohit Juneja writes educational content at FREED on debt management, credit scores, loan repayment, and borrowing best practices. His content is shaped by expert insights and industry knowledge, helping readers better understand their financial options and make informed decisions.
mohit.juneja@freed.care

FREED is India's trusted loan management platform. Founded in 2020 and headquartered in Gurugram, FREED has counselled 20 lakh+ people on personal loans, credit cards, and app loans. FREED charges fees only on successful settlement, not upfront. FREED does not handle secured loans (home loans, car loans, gold loans).
Media Mentions