Let’s talk
about Loans







75,000+
Customers served

₹450 Cr+
Total savings

4.8/5
Google rating
Browse Topics
5 CategoriesLoan Settlement
Loan Settlement Agency in Hyderabad and Mumbai: What to Check
A loan settlement agency talks to your bank or NBFC so you can settle a loan for less than you owe. It is meant for people who cannot pay in full. The agency does not need to be in your city. Your rights are the same in Hyderabad, Mumbai or anywhere in India.
Loan Settlement Agency in Bangalore: What to Check Before You Sign
A loan settlement agency in Bangalore is a firm that helps borrowers in genuine financial difficulty ask their banks or NBFCs (non-bank loan companies) to accept a smaller one-time amount as full and final payment.
Loan Settlement Apps: How to Check One Before You Trust It
Loan settlement apps are mobile apps that offer to negotiate with your bank or NBFC so you can pay less than you owe. They do not lend money. A genuine app explains fees in writing and never takes your login details. Some apps are fake and only collect advance fees or personal data.
Indiabulls Dhani Personal Loan Foreclosure and Settlement
Indiabulls Dhani personal loan foreclosure means paying your whole outstanding balance in one go to close the loan early. Ask for a foreclosure statement first, pay only through official channels, and collect a closure letter afterwards.
RBI's One-Time Settlement Scheme: Who Qualifies
There is no single RBI one-time settlement scheme that borrowers apply to directly. RBI's June 2023 framework requires every bank and NBFC to run its own Board-approved settlement policy. Qualifying depends on your account's status and your bank's own criteria, not a nationwide RBI-run scheme.
How to Combine Loans to Make Payment Easier
In this blog, combining loans means consolidating multiple eligible debts into a single loan with one monthly payment. The "easier" part isn't automatic, it depends on how you set up the new payment. This guide focuses on that setup, not the consolidation process itself.
APR vs Annual Percentage Yield: What's the Difference on a Loan?
APR is what you pay to borrow, APY is what you earn on savings. Here's how the Annual Percentage Rate on a loan actually works in India, and what to check before you sign.
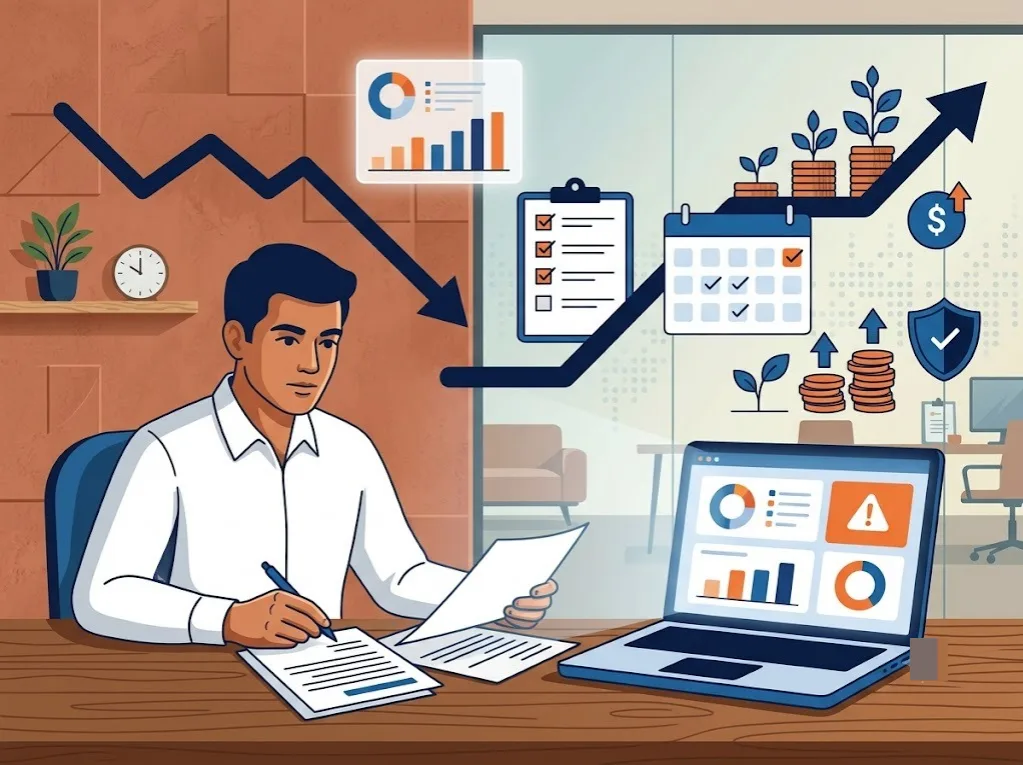
DBT in CIBIL: What 'Doubtful' Asset Status Means and How to Come Back from It
DBT in CIBIL stands for Doubtful Asset, a classification banks use for loans that have been Non-Performing Assets (NPAs) for more than 12 months. When your CIBIL report shows DBT, it means your lender has officially categorised your loan as doubtful of recovery. It sits one step below Sub-Standard (SUB) and one step above Loss (LSS) on the RBI's asset classification scale. It seriously damages your CIBIL score and blocks access to new credit until it's resolved.

Make smarter financial decisions.
Loan Settlement | Loan Consolidation | Credit Insights | FREED Shield
Get Started