Good Credit Cards for Balance Transfers: A Complete Guide
A good balance transfer card isn't just one with a low advertised rate, it's one where the promotional period is long enough to actually clear your balance, the transfer fee doesn't eat the savings, and the credit limit is high enough that moving your balance doesn't spike your utilisation. This guide covers what to check, not which specific card to pick.
Mohit Juneja
Reviewed by FREED India, Debt Resolution Specialists
 4.7/5
 ₹3,200Cr+
 20,000+
 20,00,000+4.7/5₹3,200Cr+20,000+20,00,000+
Key Takeaways

The interest-free or low-rate promotional period is the single most important factor, and it varies widely, from a few months to over a year, check the exact length, not just that one exists.
A one-time balance transfer fee, typically 1% to 3% of the amount moved, can quietly offset much of the interest savings if you don't do the math first.
If the new card's credit limit isn't meaningfully higher than your transferred balance, your utilisation on that card can spike, working against the credit score benefit you were hoping for.
Whatever balance remains unpaid when the promotional period ends typically reverts to the card's standard interest rate, often higher than what you started with.
What Makes a Credit Card "Good" for a Balance Transfer
Four factors actually determine whether a balance transfer card is a good deal: the length of the promotional low or zero-rate period, the one-time transfer fee, the credit limit relative to your transferred balance, and what the rate reverts to afterward.
The advertised headline rate alone tells you almost nothing without these four data points sitting alongside it. A "0% for balance transfers" banner means very little if the promotional window is too short to clear your balance, or if the approved credit limit turns out to be far below what you actually wanted to move. Understanding what a balance transfer card actually is is worth reading first if the concept itself is still new to you. This piece walks through each of the four factors above and how to weigh them, not which specific card to choose, since offers and terms change too often for a fixed recommendation to stay accurate for long.
The promotional period is worth starting with, since it's usually the deciding factor.

Freed Expert Tip
Before comparing any offers, calculate exactly how many months you'd realistically need to clear the balance. That number should drive which factor matters most to you.
Talk to FREEDThe Promotional Period: What to Actually Check
Promotional periods on Indian balance transfer offers vary widely; some run for a few months, others extend well over a year. This single number matters more than almost anything else on the offer, since it defines the actual window you have to make real progress.
The practical test: if you can't realistically clear the transferred balance within the promotional window, the offer is worth much less than it looks. The point is to pay it down while the rate is low, not to keep carrying it indefinitely and hoping the terms stay favourable. Also worth checking whether the promotional rate is genuinely 0% or just "low,"; some offers advertise a reduced rate rather than a true interest-free period, and that distinction changes the math meaningfully over the length of the window.
Even a great promotional period can be undone by the transfer fee, which is worth understanding on its own terms next.
Balance Transfer Fees: The Cost Most People Miss
Most balance transfer offers charge a one-time fee, commonly 1% to 3% of the amount transferred, charged upfront regardless of how good the promotional rate looks.
Do the actual arithmetic before assuming a transfer saves money. A 2% fee on a ₹1,00,000 transfer is ₹2,000 upfront, worth comparing directly against the interest you'd actually pay if you left the balance where it was for the same period. Some offers waive or cap this fee as a promotional incentive, worth specifically asking about rather than assuming the standard fee automatically applies to every offer you see advertised.
The fee matters less if the card's limit doesn't fit your balance in the first place, which is the next thing worth checking carefully.
Credit Limit vs Transfer Amount: Why This Matters
If the new card's credit limit is only slightly above the amount you're transferring, your utilisation on that card, and by extension your overall credit profile, can end up worse than before, not better.
Keeping the transferred balance lower relative to the new card's credit limit can help keep utilisation lower.If a card offers a great promotional rate but only a modest limit relative to your balance, that's a real trade-off worth weighing, not an automatic disqualifier, but a genuine factor that changes what the transfer actually does for your credit profile beyond the interest savings alone.
What happens once the promotional period actually ends is worth understanding before you commit, not after.
What Happens When the Promotional Period Ends
Any balance remaining once the promotional window closes typically reverts to the card's standard interest rate, which is often higher than the rate on the original debt you transferred away from in the first place.
This is the single most common way a balance transfer backfires, treating the promotional period as if it's permanent rather than a fixed window with a real deadline attached. The practical instruction here is simple: calendar the exact end date for the day you transfer, and track your remaining balance against it monthly, not just once at the start when the motivation is highest.

What the Law Says
RBI's Master Direction on Credit Card and Debit Card Issuance requires card issuers to clearly disclose all fees, charges, and the applicable interest rate, including what a promotional rate reverts to, in the cardholder agreement.
Check My CreditRed Flags in a Balance Transfer Offer
The offer doesn't clearly state the promotional period's exact end date, only a vague "limited time" with no concrete number attached.
The transfer fee isn't disclosed upfront and only appears after you've applied, at which point you've already committed time and a hard inquiry to the process.
The reverting standard rate isn't stated anywhere in the offer material, leaving you to discover it only once the promotional window has already closed.
The credit limit isn't confirmed before you commit to transferring a specific amount, which risks a mismatch you only discover after applying.
The offer pressures immediate action without giving you time to compare against at least one alternative, a genuine offer survives a day or two of comparison shopping.
Drag

How to Compare Offers Side by Side
Build a simple comparison across every offer using the same five columns: promotional period length, promotional rate, transfer fee, credit limit relative to your balance, and reverting standard rate. Fill in real numbers from each offer's terms and conditions, not just the headline marketing rate that gets top billing.
The offer that wins on all five isn't always obvious from the advertised rate alone, sometimes the card with the flashier "0%" banner loses out once the fee, limit, and reversion rate are all accounted for together. The full step-by-step process of actually executing a transfer is worth reading once you've picked an offer, and a dedicated calculator can run the exact savings math for you rather than doing it by hand.
What Are Your Options If a Balance Transfer Isn't Enough
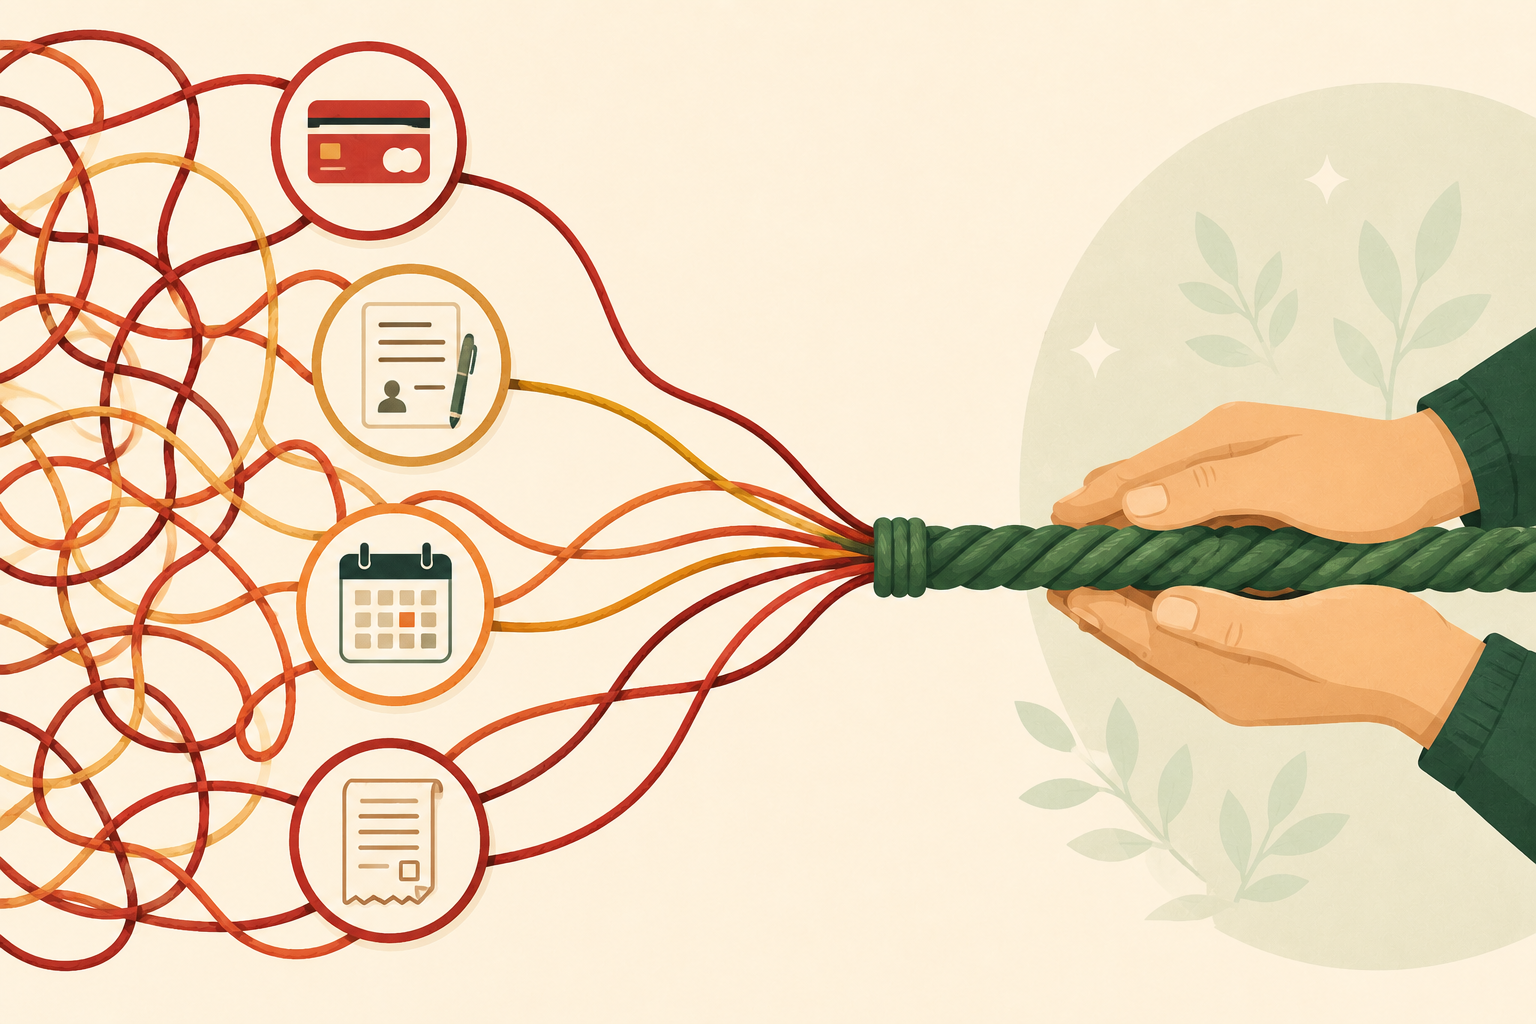
A balance transfer suits one or two balances you're confident you can clear within a promotional window. For several unsecured debts across multiple cards and loans, consolidation into one new loan with a fixed EMI and no reverting rate is often a cleaner structural fix than juggling multiple transfer deadlines across different cards.
For genuine, sustained inability to repay, settlement is the separate, structured last resort. Settlement is not something a borrower chooses out of preference, banks only consider it when someone is genuinely unable to repay in full.
How FREED Helps When Transfers Aren't Enough
For readers juggling several cards where balance transfers would mean tracking multiple promotional deadlines and reverting rates at once, FREED's Debt Consolidation Program replaces them with one new loan at one fixed, predictable EMI, no promotional cliff to track or calendar reminders to set.
For genuine, sustained inability to repay, the Debt Resolution Program is the separate, later-stage option. No specific rate or lending partner can be guaranteed, actual terms depend entirely on your own profile and the lender you're matched to.
See if consolidation beats juggling multiple transfers.
A free assessment shows your real options.
Start My Free AssessmentTips for Using a Balance Transfer Well
Calendar the exact promotional end date the moment you transfer, not an approximate month you'll figure out later.
Set a fixed monthly payment sized to clear the balance before that date, not just the minimum due, which won't get you there in time.
Avoid new spending on the card you transferred away from. That undoes the point of freeing it up and can quietly rebuild the same balance you just moved.
Recheck the math, fee versus savings, before transferring a second time to a new card. The same offer rarely looks as good twice in a row, and issuers often tighten terms for repeat transfers.
Freed Expert Tip
Set your promotional end-date reminder for 30 days before it actually expires, not on the date itself, that gives you a real window to act if you're behind schedule.
Check My Credit ScoreSources
Claim | Source |
Mandatory disclosure of fees, rates, and reverting terms in cardholder agreements | RBI Master Direction on Credit Card and Debit Card Issuance, 2022 |
Typical balance transfer fee range (1–3%) | General, current market practice across Indian card issuers |

Mohit Juneja
Mohit Juneja writes educational content at FREED on debt management, credit scores, loan repayment, and borrowing best practices. His content is shaped by expert insights and industry knowledge, helping readers better understand their financial options and make informed decisions.
mohit.juneja@freed.care

FREED is India's trusted loan management platform. Founded in 2020 and headquartered in Gurugram, FREED has counselled 20 lakh+ people on personal loans, credit cards, and app loans. FREED charges fees only on successful settlement, not upfront. FREED does not handle secured loans (home loans, car loans, gold loans).
Media Mentions