Recovery Agent Calls at Office: What the Rules Allow
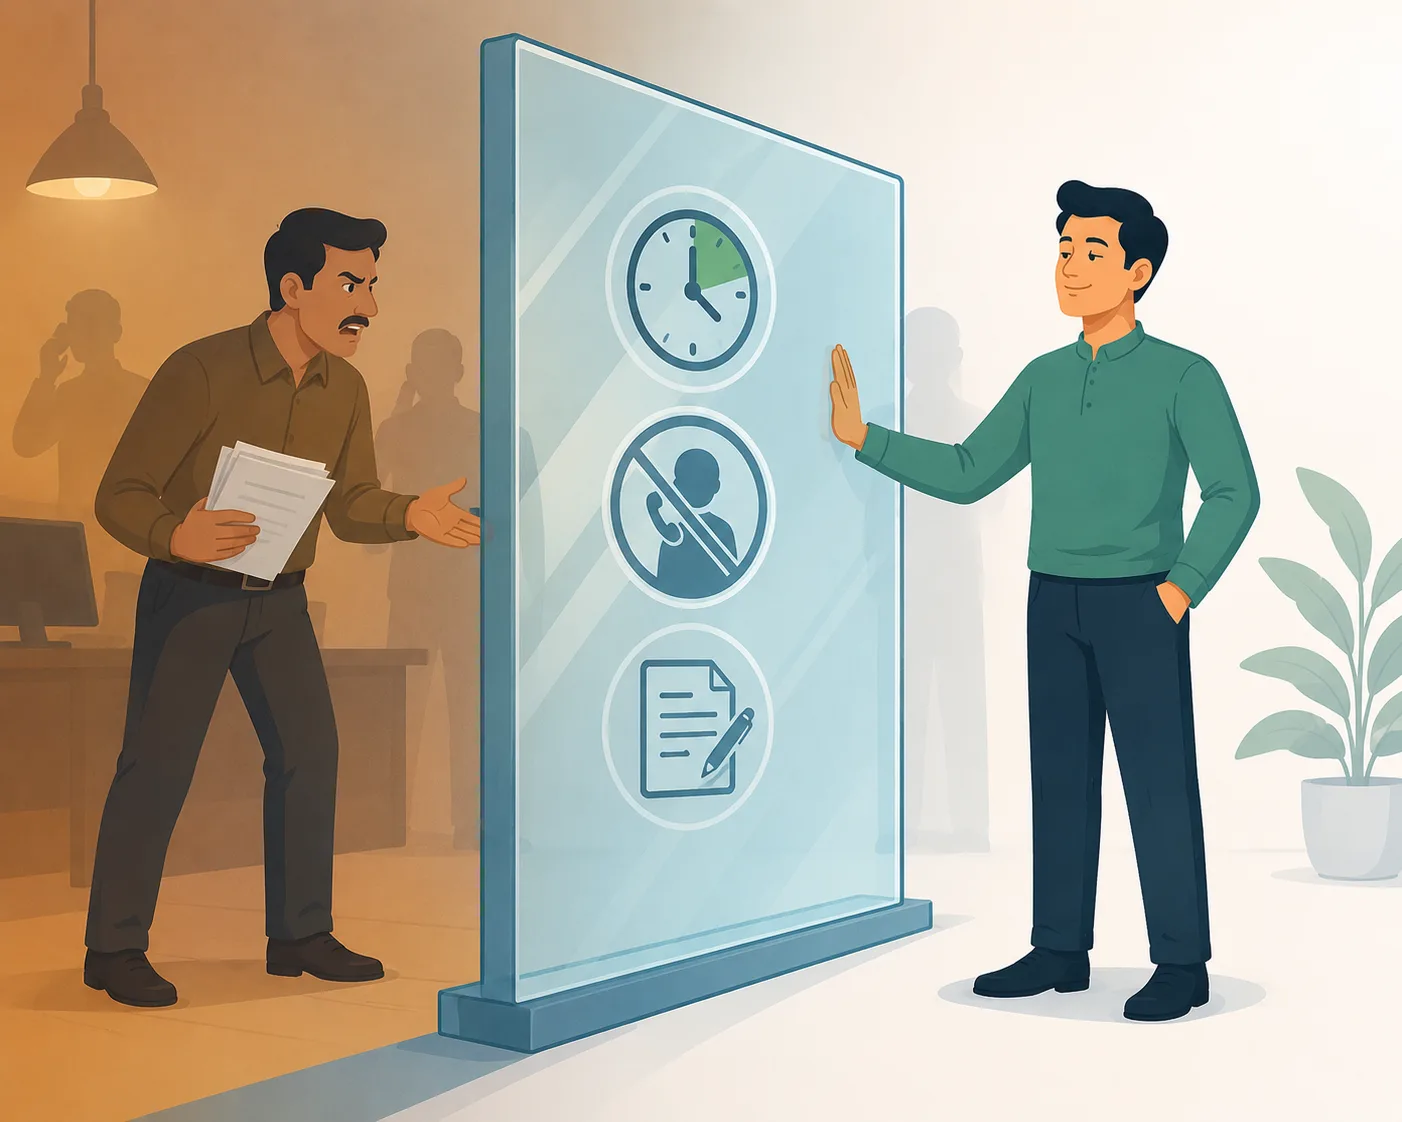
Can a recovery agent visit your office? Only in limited cases. RBI conduct rules say dues can be discussed only with you or your guarantor, and contact is limited to 8:00 am to 7:00 pm. A visit to your place of work is allowed only if no meeting place was agreed or appointments were missed repeatedly. Shaming you before colleagues is not allowed.
Mohit Juneja
Reviewed by FREED India, Debt Resolution Specialists
 4.7/5
 ₹3,200Cr+
 20,000+
 20,00,000+4.7/5₹3,200Cr+20,000+20,00,000+
KEY TAKEAWAYS

A lender may ask to meet you at a place you choose. Your workplace is not the default.
Under RBI directions effective 1 January 2027, an agent may visit your home or place of work only if you named no place, or after two or more missed appointments.
Your loan details can be discussed only with you or your guarantor, not your boss or colleagues.
Calls and messages are limited to 8:00 am to 7:00 pm unless you ask otherwise.
Note every call and visit, then complain to the lender's grievance officer and, if needed, the RBI.
Can a Recovery Agent Visit or Call Your Office?
A call comes to the office landline, or a stranger asks for you at reception. Your first thought is often about what your colleagues will think. So can a recovery agent visit your office, or call your boss? This guide explains what the RBI rules allow, what they do not allow, and what you can do in each case. You can stay calm and in control, because the rules are on your side.
Sometimes, but only in limited cases. And never to discuss your debt with anyone else.
The idea behind the rules is simple. A lender is meant to contact you at a place you choose. Your workplace is not the default. A visit to your home or place of work comes later, as a fallback. It is allowed only if you named no place, or if you missed appointments again and again.
Here is an example. Say you told the lender to meet you at your home on Saturday mornings. The agent comes, and you are not available twice. After two or more missed appointments, the rules allow a visit to your home or your place of work. Until that point, a visit to your office would not be the first step.
A visit or a call is not the same as a disclosure. Even where a call to your office is allowed, the agent cannot share your loan details with your employer or colleagues. Your dues are between you and the lender.
Please note the timing. The RBI's new recovery directions take effect on 1 January 2027. Before that date, the rules rest on the RBI's general fair practices and conduct guidance. So we do not say that workplace visits are banned outright. We say they are limited, and that shaming you before others is never acceptable.
You can read the wider rules in our guide to RBI guidelines for loan recovery. Next, let us look at the rules on time, place and conduct in a bit more detail.

What Do RBI Rules Say About Time, Place and Conduct?
These are the rules that matter most when the issue is your workplace. This is a short summary, and our general recovery guides cover the full list.
Time. Contact is allowed between 8:00 am and 7:00 pm. Earlier or later contact is allowed only if you ask for it or agree to it.
Place. Contact happens at the place you choose. If you named no place, or after two or more missed appointments in a row, an agent may visit your residence or place of work.
Who. Dues are discussed only with you or your guarantor. Nobody else needs to hear about them.
Identity. If a recovery agent visits, ask to see their identification and evidence that they are authorised to act for the lender. Check the applicable RBI directions for any specific documentation or advance-notice requirements.
Sensitive moments. Agents must avoid times such as a bereavement, a medical emergency or a marriage function.
These RBI directions take effect on 1 January 2027.
Here is how this works in daily life. Say an agent rings your office at 8:30 pm, and you have not agreed to late calls. That call falls outside the 8:00 am to 7:00 pm window. You can note the time and number, then use it in a complaint.
For the complete rules, read our guides on personal loan recovery rules and payment recovery agents' rights.
Under RBI directions effective 1 January 2027, loan dues can be discussed only with the borrower or guarantor.

What the Law Says
Under RBI directions effective 1 January 2027, loan dues can be discussed only with the borrower or guarantor.
Read What RBI Allows in RecoveryCan a Recovery Agent Tell Your Boss or Colleagues About Your Loan?
No. Under the RBI directions, loan dues are discussed only with you or your guarantor. Intimidating or harassing your relatives, friends or co-workers is treated as a harsh practice.
It helps to separate three situations:
The agent asks for you by name and hangs up. This is awkward, but it is not a disclosure. No details about your loan were shared.
The agent says why they are calling to a receptionist or colleague. This is the part that crosses the line. Your loan is no one else's business.
The agent shares your details by message or post. This is also not allowed.
If a colleague passes on such a call, a short reply can help. You can say, "I will handle it. Please do not share any details with anyone." It keeps the conversation calm and short.
There is one special case. If your employer is a named reference or a guarantor on the loan, the lender may contact them. Even then, contact is limited to what is needed for recovery. It is not a reason to tell the office about your loan.
This kind of pressure is stressful, and the stress is real. You can read more in our guide on mental harassment by bank. You have not done anything to deserve being shamed at work.
What Counts as Workplace Harassment by a Recovery Agent?
A polite, firm reminder is allowed. Pressure at your workplace that shames or threatens you is not. The lists below show where the line sits.
Usually acceptable:
- A polite call to your own number within the permitted hours.
- A single visit that follows the rules, where the agent shows ID.
- An agent who asks you to name a meeting place.
Crosses the line:
- Repeated calls to your office line.
- Speaking about your debt in front of colleagues.
- Threats about your job.
- Calling your manager to pressure you.
- Waiting outside your office.
- Calls outside 8:00 am to 7:00 pm.
- Abusive or threatening language.
- Posting or sharing your details.
Three facts can bring real calm. A recovery agent cannot arrest you. A recovery agent cannot independently seize your salary or require your employer to repay your loan. Any recovery action must follow the applicable law and legal process. If an agent threatens to take your salary or interfere with your employment, document the threat and raise it with the lender. The legal options available to a lender depend on the type of loan and the circumstances.
An employer may be asked to confirm your employment only where you are a named reference or guarantor. Otherwise, there is no reason for the agent to contact your workplace at all.
Your rights do not disappear when you miss an EMI. You can read more in our guide to understanding your rights as a borrower, even if you default.
What Should You Do If a Recovery Agent Calls or Visits Your Office?
You can handle this calmly, one step at a time. Each step has a short reason, so you know why it helps.
Step 1: Stay calm and move the conversation somewhere private. A private spot keeps the talk away from colleagues.
Step 2: Ask for the agent's name, agency and ID. This tells you who is really calling.
Step 3: Ask which loan and what amount they are calling about. This confirms that the call is about your own account.
Step 4: Say you will reply in writing, and ask them not to share details with anyone else at work. A written reply creates a clear record.
Step 5: Note the date, time, number and what was said. A written record is your strongest tool. Our guide on how to document threats and harassment from recovery agents shows how to keep it.
Step 6: If a colleague took the call, ask them to write down what was said. A second person's note adds weight to your record.
Step 7: Check your own loan statement against the amount quoted. For example, if the agent says ₹42,000 is due but your statement shows ₹39,200, ask for the breakup in writing. Do this before you agree to anything.
Step 8: Tell HR only if you want to. You are not required to share your loan with your employer. The choice is yours.
Please do not feel you must hang up on every call or avoid the lender. A calm written reply is often the best path.
How Do You Complain After a Workplace Visit or Call?
If an agent contacted your workplace and crossed the line, you can complain. The path is short and clear.
Write to the lender's grievance officer. Include your notes with the date, time, phone number and what was said. The RBI directions require recovery communications to carry the grievance officer's name, email, phone and address. If these are missing, ask for them.
Ask for a complaint reference number. This lets you refer to the same complaint again later.
If it is not resolved, escalate. Go to a higher level within the lender, and then to the RBI Complaint Management System. The RBI Integrated Ombudsman Scheme is another route.
Keep copies of everything. Save your complaint, the replies and the proof of sending.
The process is similar across lenders. If you need a format, see our sample complaint letter against recovery agents.
We cannot promise a result or a time frame. But a clear, dated complaint with your notes attached is the strongest way to be heard.
Ask a colleague who took the call to write down what was said and sign it. A witness note strengthens your complaint.
Get Help With My Notice
Ask a colleague who took the call to write down what was said and sign it. A witness note strengthens your complaint.
Get Help With My NoticeAllowed vs Not Allowed: A Quick Reference for the Workplace
This table is a quick check you can read in a minute.
Situation | Allowed? | Why |
|---|---|---|
Agent calls your mobile at 6 pm | Yes | Within 8:00 am to 7:00 pm |
Agent calls your mobile at 9 pm | Not without your consent | Outside the contact window |
Agent visits your office after you named your home as the meeting place | Not as a first step | Contact is at your chosen place first |
Agent visits your office after two missed appointments | Possible | Directions allow a visit to the place of work in that case |
Agent tells your colleague about your loan | No | Dues discussed only with you or your guarantor |
Agent threatens your job or reputation | No | Harsh practice under the directions |
Agent carries no ID | No | ID and authorisation letter required |
Rates and ranges shown are indicative. Final terms decided by the bank. FREED is not a Loan Provider. No outcome is guaranteed. Please verify directly with your bank.
Please note that the rules differ slightly by lender type. The directions apply from 1 January 2027. A table like this is a guide to help you, and it does not replace the exact text of the rules.
Not sure your EMIs are manageable? Check before you talk to the lender. If you want to see your credit position too, Check Credit Insight shows your Experian-based score and the steps to improve it.
Check How Manageable Your EMIs Are
Get a score from 0 to 100 and a plain-language read on your EMIs.
Check My EMI ScoreHow FREED Shield Helps With Recovery Pressure at Work
FREED Shield helps ensure that customers don't have to face recovery-related pressure alone. Anyone can use FREED Shield, not only enrolled customers.
It helps you understand your rights, keep records of calls and visits, and report harassment through the right channels. FREED's in-house legal team can also verify a notice you received, tell you whether a reply is needed, and help you draft that reply. FREED provides pre-litigation support only. This means FREED does not give legal representation once a case is filed in court. FREED does not speak to your employer on your behalf.
The next step depends on where you stand.
If you are still paying your EMIs: FREED's Loan Consolidation Plan is for people who can still repay but need a smarter way to manage their debt. If you can still repay but are struggling with several EMIs, debt consolidation may help simplify your repayments. Whether it reduces your monthly payment or total borrowing cost depends on the interest rate, tenure, fees and loan amount. A new loan does not automatically improve your credit score; repayment behaviour and your overall credit profile remain important.
If repaying in full is genuinely not possible: the Loan Settlement Plan is the last resort. Any waiver can be up to 50%*, at the lender's discretion, and a Settled mark can stay on your report for up to 7 years. There is a non-refundable evaluation fee.
If you are unsure which step fits, FREED counsellors are available for a call. There is no pressure, just someone to think it through with you.
*Rates and ranges shown are indicative. Final terms decided by the bank. FREED is not a Loan Provider. No outcome is guaranteed. Please verify directly with your bank.

Mohit Juneja
Mohit Juneja writes educational content at FREED on debt management, credit scores, loan repayment, and borrowing best practices. His content is shaped by expert insights and industry knowledge, helping readers better understand their financial options and make informed decisions.
mohit.juneja@freed.care

FREED is India's trusted loan management platform. Founded in 2020 and headquartered in Gurugram, FREED has counselled 20 lakh+ people on personal loans, credit cards, and app loans. FREED charges fees only on successful settlement, not upfront. FREED does not handle secured loans (home loans, car loans, gold loans).
Media Mentions