RBI on Loan Recovery: Can a Bank Touch Your Gratuity or Pension?
Generally, pension and gratuity benefits have legal protections against certain forms of attachment for debt recovery, but the exact position depends on the nature of the benefit and the recovery action involved. This is supported by statutory protections and court rulings concerning the attachment and recovery of pensionary and gratuity benefits. Gratuity and pension carry specific statutory protection from attachment, with one narrow exception.
Mohit Juneja
Reviewed by FREED India, Debt Resolution Specialists
 4.7/5
 ₹3,200Cr+
 20,000+
 20,00,000+4.7/5₹3,200Cr+20,000+20,00,000+
KEY TAKEAWAYS

In the Madurai Bench case discussed below, the Madras High Court held that the pensioner's account, maintained primarily for receiving monthly pension, could not be attached or restricted in the circumstances of that case merely to recover loan dues owed to the same bank.
Section 13 of the Payment of Gratuity Act, 1972 states gratuity "shall not be liable for attachment" in execution of any decree. This is an explicit statutory shield.
The only exception is narrow. Gratuity can be forfeited if an employee was terminated specifically for willful misconduct, negligence, or an act causing loss to the employer, not for an unrelated loan default.
Courts have confirmed this protection extends even to a retired employee who acted as a guarantor for someone else's defaulted loan, not just the primary borrower.
Can a Bank Take Your Gratuity or Pension to Recover a Loan? The Short Answer
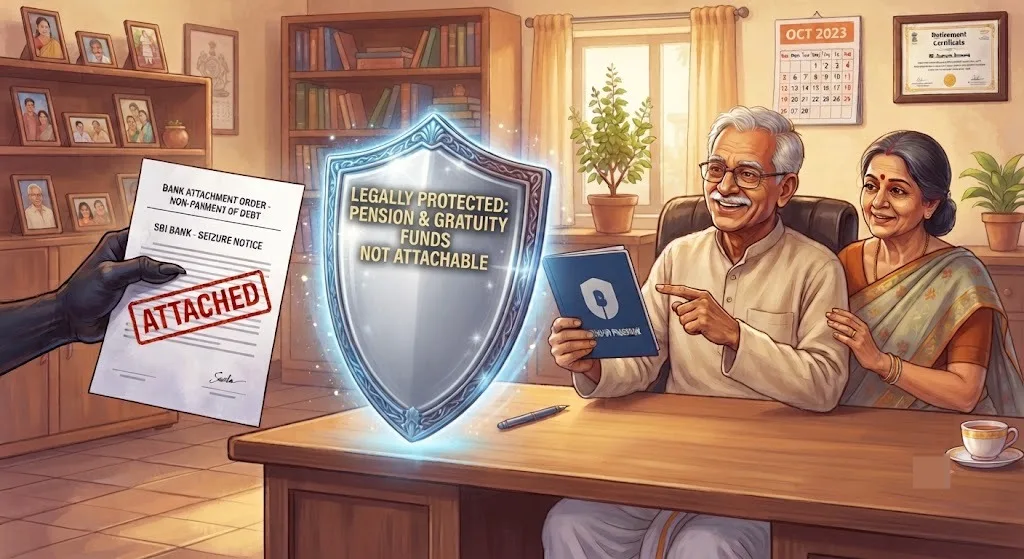
Generally, no. Both gratuity and pension carry specific legal protection from attachment for debt recovery. This isn't a grey area or something a bank does as a courtesy. It's grounded in explicit statute and confirmed directly by court rulings.
Here's the exact scenario this protects against. Say a bank has given you a loan and also happens to be the bank where your pension gets credited. Default on that loan, and the bank still can't touch the pension money itself to recover the dues — that protection attaches to the funds, not the account as a whole. If the same account also holds your salary, savings, or other deposits, that portion doesn't carry the same shield. Only the identifiable pension credit is exempt. That's the practical situation this piece is about, and the law is clear on it.
One honest caveat upfront. There's a narrow exception related to how gratuity itself can be forfeited by an employer, which we'll cover in full further down. It's about misconduct during employment, not about a separate loan default, and it doesn't change the core answer here.
This isn't a theoretical reading of the law either. A real case put this exact question in front of the Madras High Court, and the Court answered it directly.

Freed Expert Tip
If a bank has restricted access to your pension account over a loan default, that's worth challenging directly. This piece gives you the specific legal grounds to do so.
Talk to FREED's TeamThe Madras High Court Case That Confirmed This
In 2015, the Madras High Court's Madurai Bench decided a case that answers this question directly. A. Muthuiruvakkal v. State Bank of India, W.P.(MD) No. 17838 of 2015, decided on 27.11.2015. A pensioner, Mrs. A. Muthuiruvakkal, had her savings account with State Bank of India, an account used solely for receiving her monthly pension, effectively frozen by the bank. The bank had deducted about ₹14,681 from her pension account after preventing her from operating it, to recover an outstanding loan she had defaulted on with that same bank, and had already deducted a specific amount from it before she challenged the action.
Justice K. Ravichandrabaabu ruled in her favour. A Savings Bank Account maintained primarily for the purpose of depositing monthly pension amount could not be attached by a bank just because the account holder had defaulted repayment of a loan availed from them. The bank's action of freezing the account was held to be impermissible in law.
The Court leaned on an earlier Supreme Court ruling to get there, Radhey Shyam Gupta v. Punjab National Bank (2009). In that case, a lower court had allowed a bank to attach Fixed Deposits belonging to a loan guarantor, without recognising that he had converted his pension and gratuity amounts into those very Fixed Deposits. The Supreme Court criticised that approach directly. The money's protected character doesn't disappear just because it changes form, from a pension account into a Fixed Deposit, for instance. That principle is what the Madras High Court applied a few years later to a pensioner's own bank account.
This case isn't an outlier. It sits on top of a statutory basis that goes back much further, and that basis is worth understanding on its own.

What the Law Says
The Madras High Court has ruled that a bank cannot attach or restrict a pension account, maintained primarily for receiving monthly pension, simply because the account holder defaulted on a loan from that same bank.
Understand My RightsWhy Gratuity and Pension Are Legally Protected
Two statutory sources give this protection its teeth. Section 60 of the Code of Civil Procedure, 1908 lists certain pensionary payments and gratuities among amounts protected from attachment in execution of a decree, subject to the provision's specific wording and exceptions. Section 13 of the Payment of Gratuity Act, 1972 goes further and states plainly that gratuity payable under the Act "shall not be liable to attachment in execution of any decree or order of any civil, revenue, or criminal court."
There's a reason this protection exists, and it's not a technicality. Gratuity and pension are deferred compensation, money earned over years of service, paid out at the point when someone can least afford to lose it, retirement or the end of employment. These statutory protections recognise the special nature of certain pensionary and gratuity benefits and restrict their attachment in circumstances covered by the applicable laws.
Worth being precise about the scope here too. This protection applies specifically to debt recovery and civil decree attachment. This piece isn't addressing income tax recovery or other specific statutory recovery mechanisms, which operate under entirely separate laws with their own distinct rules. A pension account can, in some circumstances, be reached for tax dues in a way it cannot for an ordinary loan default. That's a different question from the one this piece is answering.
There's one situation, though, where this protection genuinely narrows, and it's worth knowing exactly where that line sits.

Facing pressure on your pension or gratuity specifically?
Talk to FREED about your situation.
Book My Free CallWhen Can Gratuity Be Forfeited?
Section 4(6) of the Payment of Gratuity Act allows an employer to forfeit gratuity, wholly or partially, but only in narrow circumstances. Forfeiture applies where an employee's services were terminated specifically for an act of willful omission or negligence that caused damage or loss to the employer's property, or for an act constituting an offence involving moral turpitude, committed during the course of employment.
Here's what this exception does not cover. An ordinary loan default has nothing to do with why someone's employment ended. Forfeiture under this section is tied specifically to misconduct during employment, not to an employee's separate financial dealings with a bank. If you retired normally, with no disciplinary finding against you, this exception simply doesn't apply to your situation, whatever loan trouble you might be dealing with separately.
A 2025 Orissa High Court decision discussed the statutory conditions governing forfeiture of gratuity. In a 2025 ruling, the Orissa High Court held that gratuity is neither a gift nor a favour but a deferred payment earned through service, and it cannot be withheld unless the Act's specific conditions are actually met. Where an employee retired normally and the statutory grounds for forfeiture were not established, an unrelated loan default would not, by itself, constitute a ground for forfeiture under Section 4(6).
There's a related question worth asking directly, because it touches a real fear many people carry. What if you didn't take the loan yourself, but stood as a guarantor for someone else's?
Does This Protection Extend to Guarantors Too?
Here's a genuinely important, related question. What happens if a retired employee stood as a guarantor for someone else's loan, and that loan later defaulted? Can the bank withhold that person's own gratuity to recover the guaranteed amount?
A 2025 Orissa High Court case answers this directly. A retired Deputy Manager at a cooperative bank had her gratuity withheld after she stood as guarantor for a loan that the principal borrower later defaulted on. The bank argued that because her liability as guarantor was coextensive with the borrower's, her gratuity could be withheld until the loan was cleared. The Controlling Authority under the Payment of Gratuity Act rejected that argument. The Appellate Authority upheld the rejection. The bank's further challenges, including a writ appeal before a Division Bench of the High Court, failed too. The Court confirmed her gratuity was protected on exactly the same statutory basis as anyone else's. In the cited case, the court did not treat the employee's status as a guarantor as a separate ground for withholding her gratuity.
The practical takeaway is straightforward. The 2025 Orissa High Court decision discussed here indicates that guarantor status does not, by itself, remove the statutory protection applicable to gratuity. A bank cannot bypass this protection simply by pointing to a guarantee agreement instead of a direct loan.
Stood as a guarantor and now facing pressure on your gratuity?
Talk to FREED about your rights here.
Book My Free CallWhat About Provident Fund?
General Provident Fund (GPF) balances carry similar statutory protection. Section 3 of the Provident Funds Act, 1925 makes clear that a compulsory deposit in a government provident fund cannot be assigned, charged, or attached under any court decree. Courts have described this protection as complete, extending even after the amount becomes payable to the employee.
General Provident Fund balances may receive statutory protection under the applicable provident fund law. The exact position can differ for other types of provident fund accounts, so the specific scheme and governing legislation should be checked.
What to Do If a Bank Tries to Attach Your Gratuity or Pension
- 1
Get the bank's action in writing.
Ask specifically which account or amount is being restricted, and on what stated basis. A verbal restriction with no paper trail is harder to challenge later.
- 2
Respond in writing, citing the specific protection.
Reference Section 13 of the Payment of Gratuity Act for gratuity, Section 60 of the CPC for pension, and point directly to the Madras High Court ruling covered above. Citing the relevant statutory provision and explaining the basis of your objection can make your written complaint clearer and easier to assess.
- 3
Escalate if the bank doesn't reverse the action.
Start with the bank's grievance officer. If the complaint is not resolved within the applicable period, or you receive an unsatisfactory response, you may be able to escalate it through the RBI Integrated Ombudsman Scheme if the complaint and regulated entity fall within its scope.
- 4
For a gratuity dispute specifically, approach the Controlling Authority.
For disputes concerning gratuity covered by the Payment of Gratuity Act, the appropriate Controlling Authority may have jurisdiction under the Act, depending on the nature of the dispute.
What Are Your Options for the Underlying Debt
Understanding this protection doesn't make the underlying loan debt disappear. It simply means gratuity and pension aren't available to a bank as a recovery route. The debt itself still needs to be addressed on its own terms.
For genuine, sustained inability to repay unsecured debt, settlement is the structured last resort. Settlement isn't something a borrower chooses out of preference. Lenders may consider settlement in cases involving financial difficulty, subject to their policies, assessment and approval. . If you are eligible and the arrangement is approved on suitable terms, FREED's Loan Consolidation Plan can combine multiple repayments into a single payment that may be lower than the existing combined EMIs.
How FREED Helps
FREED doesn't handle disputes over gratuity or pension attachment directly. That's a matter for the bank's grievance process, the Controlling Authority under the Payment of Gratuity Act, or the courts, and it needs that specific route, not a debt platform.
What FREED does help with is the underlying unsecured debt itself. If you're still managing payments across multiple loans, FREED's Loan Consolidation Plan merges those into one lower EMI. If repayment has genuinely become impossible, FREED's Loan Settlement Plan works with your banks toward a settlement.
Tips for Protecting Your Gratuity and Pension
Know this protection exists before a bank tests it. Don't assume a pension or gratuity account is fair game just because a bank suggests otherwise. Understanding the applicable legal protections can help you respond appropriately if a bank attempts to restrict protected pension or gratuity benefits.
If a bank restricts your account, respond in writing immediately. Cite the specific statutory protection, don't just object generally.
Keep records showing your pension account's purpose clearly. A statement showing that the account is used primarily for pension deposits may help establish the source and nature of the funds if the account is disputed.
If you're a guarantor, know this same protection applies to you. Not just to primary borrowers. This is a common point of confusion, and banks sometimes lean on that confusion.
Freed Expert Tip
Keep a copy of your pension account statement showing it's used solely for pension deposits. This documentation directly supports the Madras HC reasoning if you ever need to invoke it.
Talk to FREED's TeamSources
Claim | Source |
Bank cannot attach pension account to recover loan dues | Order of the Madras High Court, Madurai Bench (2015), Mrs. A. Muthuiruvakkal v. State Bank of India |
Attachment of pension/gratuity, even when converted to Fixed Deposits, held improper | Radhey Shyam Gupta v. Punjab National Bank & Anr., (2009) 1 SCC 376, Supreme Court of India |
Gratuity "shall not be liable for attachment" in execution of any decree | Section 13, Payment of Gratuity Act, 1972 |
Pension and gratuities to pensioners exempt from attachment | Section 60, Code of Civil Procedure, 1908 |
Gratuity forfeiture limited to willful misconduct/negligence causing loss, or an offence involving moral turpitude, not loan default | Section 4(6), Payment of Gratuity Act, 1972 |
Protection extends to a guarantor's gratuity, not just the primary borrower's | Cuttack Central Co-operative Bank Ltd. v. The Joint Labour Commissioner & Ors., Orissa High Court (2025) |
GPF balances not liable to attachment | Section 3, Provident Funds Act, 1925 |

FREED is India's trusted loan management platform. Founded in 2020 and headquartered in Gurugram, FREED has counselled 20 lakh+ people on personal loans, credit cards, and app loans. FREED charges fees only on successful settlement, not upfront. FREED does not handle secured loans (home loans, car loans, gold loans).
Media Mentions