What Is a Consent Decree in Debt Recovery, Explained Simply
A consent decree is a court-approved settlement agreement between a lender, a bank or NBFC, and a borrower. Both parties agree on settlement terms, the document gets filed with the Debt Recovery Tribunal or a civil court, and a judge approves it. A consent decree generally cannot be challenged through a regular appeal. However, limited legal remedies may be available in specific circumstances, such as a dispute over whether a valid compromise was actually reached or whether the compromise was lawful. The applicable remedy depends on the facts and the forum. Unlike a court judgment won after a full trial, a consent decree is a mutual agreement between both sides. It shows the borrower negotiated with the lender, reached a deal, and got the court's stamp on it. The terms can cover the amount payable, payment schedule, interest, security and consequences of default, depending on the compromise reached.
Mohit Juneja
Reviewed by FREED India, Debt Resolution Specialists
 4.7/5
 ₹3,200Cr+
 20,000+
 20,00,000+4.7/5₹3,200Cr+20,000+20,00,000+
KEY TAKEAWAYS

It's a decree of the court, based on an agreement the parties negotiated and the judge signed off on. The compromise is what shapes the terms, but the decree itself carries the same legal weight as any other court decree.
A consent decree gets obtained either through a civil court or the Debt Recovery Tribunal, generally for cases above ₹20 lakh at the DRT.
A decree gets made by a judge with the consent of all parties, a settlement agreement the court has approved.
A consent decree is generally not appealable like an ordinary contested decree. Challenges to the compromise itself are governed by specific procedural rules and may need to be raised before the court that recorded it.
There's no admission of guilt or liability, both parties simply agree to terms and move forward.
It's binding and enforceable on both the lender and the borrower.
What Exactly Is a Consent Decree? (Not a Court Judgment)
This distinction matters more than it might seem. A judgment is what a court decides after a full trial, one side wins, the other loses, based on evidence and arguments. A consent decree is different entirely. The parties reach the compromise, after which the court considers whether the requirements for recording it are satisfied and, where appropriate, passes a decree in accordance with the compromise. The judge isn't deciding a winner here, both sides have already settled before the court gets seriously involved.
Here's a plain example. A bank sues a borrower over an unpaid loan. The case is pending. Outside the courtroom, For illustration only, suppose the parties agree to a payment of 60% of the claimed amount of the total debt over 12 months. Both sides then file a joint application with the Debt Recovery Tribunal, asking the judge to approve these terms. The DRT judge reviews and approves it, and that approved agreement is the consent decree. It helps to understand what a Debt Recovery Tribunal actually is and how it works before going further.

Have Questions About a Case Involving You?
A short, honest conversation about where things stand
Talk to FREED's TeamConsent Decree vs Settlement vs Court Judgment: What's the Difference?
These three terms get used loosely, but they mean genuinely different things.
A settlement is simply the negotiated deal itself, paper only, agreed between two parties, without any court involvement at all. A consent decree is that same settlement, but approved and signed by a judge, which turns it into an actual court order. A judgment is different from both, it's what a court decides after a full trial, with no settlement involved at any point.
A consent decree has the force and enforceability associated with a court decree, subject to the terms of the decree and applicable law. A settlement is a contractual agreement between the parties. Its enforceability and the remedy available after a breach depend on how the settlement was documented and the applicable law. A court-recorded compromise has an additional procedural and enforcement framework. It's worth reading understanding your rights as a borrower, even if you default, since these protections apply regardless of which of these three paths your case ends up on.
Understand Where Your Situation Stands
See how a settlement compares to a consent decree for your case.
Check your optionsWhere Does Consent Decree Happen? DRT vs Civil Court
Two forums generally handle these. The Debt Recovery Tribunal handles cases where the loan amount exceeds ₹20 lakh, under the Recovery of Debts Due to Banks and Financial Institutions Act, 1993. Civil courts generally handle smaller amounts below that threshold.
Both forums can issue a consent decree. The DRT is a specialised forum for recovery proceedings covered by the Recovery of Debts and Bankruptcy Act. Its statutory pecuniary jurisdiction is subject to the applicable threshold and other requirements. Civil courts may have jurisdiction in matters that fall outside the DRT framework. The correct forum depends on the nature of the claim and the law governing the recovery action, while larger defaults, business loans and bigger secured lending typically end up at the DRT instead.
In practice, this usually looks like: the bank files a case at the DRT, negotiations happen either alongside or outside that process, both sides reach an agreement, then jointly apply for a consent decree, and the DRT judge approves it during a sitting.

Freed Expert Tip
A consent decree is non-appealable. Once it's signed, neither side can challenge it later on an "unfair terms" basis in a higher court. That means negotiating hard before court approval matters far more than usual, once the judge signs, the deal is locked. Get a lawyer to review the terms before you agree to anything.
Check your optionsHow Does a Consent Decree Get Passed? Step by Step
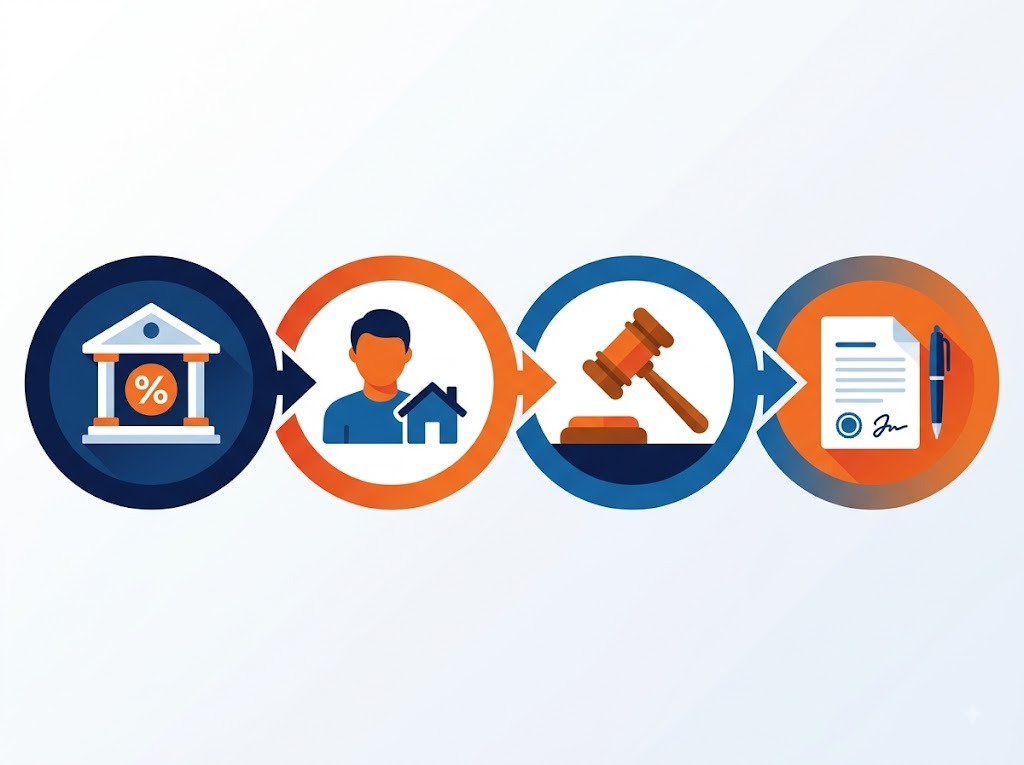
Step 1. Default happens. Payments stop, and the account moves into arrears.
Step 2. The lender sends notices and attempts recovery. Standard collection efforts begin before anything reaches court, and it's worth knowing RBI's guidelines for loan recovery at this stage, since they govern how these early attempts are allowed to happen.
Step 3. A case gets filed in DRT or civil court. This depends on the loan amount involved.
Step 4. The bank and borrower negotiate. This can happen outside court entirely or alongside an already-filed case.
Step 5. Both sides reach an agreement. Terms get worked out on the amount, schedule, and timeline.
Step 6. A joint application gets filed. Both parties submit the agreed settlement terms to the court or tribunal together.
Step 7. The judge reviews the terms.
Step 8. The judge approves it, and the consent decree is passed.
Step 9. The decree becomes binding on both parties.
If the matter is resolved by compromise, the court or tribunal does not need to decide the underlying dispute on its merits in the same way as a fully contested matter. Both sides have already gotten part of what they wanted before the court ever gets formally involved.
Talk Through Where Your Case Stands
See what this process could look like for you.
Check your optionsWhat Are Typical Terms in a Consent Decree?
Terms generally cover a handful of core elements. The amount to be paid, usually reduced from the original debt, sits at the centre. A payment schedule follows, either a lump sum or structured installments, along with a defined time frame, months or years, depending on what was negotiated. Interest implications get spelled out too, along with how any collateral gets handled if the loan was secured, and what happens if a payment under the decree gets missed.
Where the compromise is intended to provide full and final settlement, the decree or settlement terms should clearly state when the obligation will be treated as fully satisfied and what happens after the agreed payments are completed. Both parties sign off on this. The borrower's obligation is clear, pay according to the agreed schedule. The lender's obligation is equally clear, accept the reduced amount and stop all collection efforts once the terms are being honoured.

What the Law Says
Consent decrees are binding under India's Civil Procedure Code. They're non-appealable, meaning final, with the only exception being fraud or mutual error, both extremely rare and difficult to prove. If a party fails to comply with an enforceable term of the decree, the other party may have remedies through the applicable execution or enforcement process. The precise remedy depends on the terms of the decree and the forum. The same protection applies in reverse if the borrower is the one who breaches.
Learn your rights
Why Would a Borrower Agree to a Consent Decree?
A borrower may consider a consent decree when the negotiated terms provide greater certainty or a manageable repayment arrangement compared with continuing the dispute. Whether it is beneficial depends entirely on the proposed terms and the borrower's circumstances. If the dispute is contested, the eventual outcome depends on the claims, evidence, contractual terms and applicable law. A consent decree, by contrast, is negotiated down, 60% of the debt instead of 100%, for example, and it avoids trial entirely, which tends to be faster and less costly for both sides.
Worth reading how to file a complaint if recovery agents cross a line even after a decree is signed, since agreeing to a decree doesn't automatically guarantee every recovery contact stops immediately. A structured repayment schedule tends to feel far more manageable than an open-ended default hanging over someone indefinitely. There's also real value in certainty itself, knowing exactly what's owed, when it's due, and that there won't be sudden surprises down the line. For the lender, the benefit runs the other way, a guaranteed, agreed recovery beats the genuine risk of a trial outcome that could go either way.
Understand Your Rights in Debt Recovery
Know what recovery agents can and cannot do under RBI rules.
Learn My RightsAfter Consent Decree: What Happens to Your CIBIL Score?
A consent decree still means a default happened, the bank took legal action, and that fact stays on your CIBIL report. A consent decree does not erase the underlying credit history. If the lender reports the account as 'Settled', that status may remain relevant to future lenders when they assess your credit profile.
Once the debt is marked settled in full under the decree, the recovery process closes out. There is no fixed timeline for a credit score to recover. Future impact depends on the reported account status, the rest of your credit history and your subsequent repayment behaviour. The account's reported status can remain part of your credit history and may affect future lending decisions. It isn't a fresh start in the truest sense, but it is a clear, structured path forward, which is more than an unresolved default ever offers.

Mohit Juneja
Mohit Juneja writes educational content at FREED on debt management, credit scores, loan repayment, and borrowing best practices. His content is shaped by expert insights and industry knowledge, helping readers better understand their financial options and make informed decisions.
mohit.juneja@freed.care

FREED is India's trusted loan management platform. Founded in 2020 and headquartered in Gurugram, FREED has counselled 20 lakh+ people on personal loans, credit cards, and app loans. FREED charges fees only on successful settlement, not upfront. FREED does not handle secured loans (home loans, car loans, gold loans).
Media Mentions