Rule 8(1) SARFAESI Explained: What It Means for Borrowers
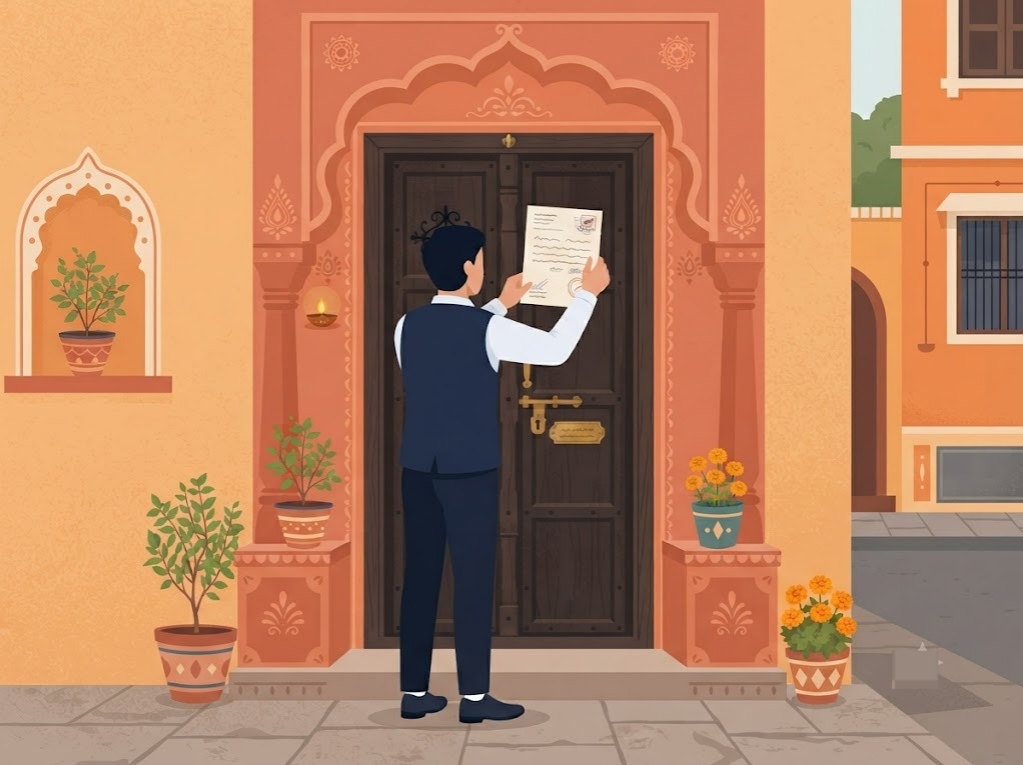
Rule 8(1) of the Security Interest (Enforcement) Rules, 2002 requires an authorised officer to take possession of immovable secured property by delivering a formal possession notice to the borrower and affixing a copy on the property itself. Rule 8(2), the companion provision, requires this notice be published in two newspapers within 7 days of taking possession. Courts have quashed possession actions where banks got either step wrong.
Mohit Juneja
Reviewed by FREED India, Debt Resolution Specialists
 4.7/5
 ₹3,200Cr+
 20,000+
 20,00,000+4.7/5₹3,200Cr+20,000+20,00,000+
KEY TAKEAWAYS

Rule 8(1) requires two things together: delivering a possession notice to the borrower, and physically affixing it on the property's outer door or another conspicuous place, in the format set out in Appendix IV.
The 7-day publication deadline under Rule 8(2) is counted from the date possession is actually taken, not from the date of the earlier demand notice.
The Supreme Court has held that a borrower may approach the DRT under Section 17 at the stage of the possession notice under Rules 8(1) and 8(2), without waiting for actual physical possession to be taken. The remedy remains subject to the applicable facts, procedural requirements and limitation rules.
Courts and tribunals have treated proven non-compliance with Rule 8 requirements seriously, and in some cases have set aside possession notices and subsequent actions. The effect of a particular defect depends on the evidence, the nature of the non-compliance and the applicable judicial interpretation.
What Rule 8(1) Actually Requires
Once the demand notice period runs out and a bank moves to take possession of immovable secured property, the authorised officer has two jobs, not one. The authorised officer must deliver a possession notice prepared as nearly as possible in the form prescribed in Appendix IV, and affix the notice on the outer door or at another conspicuous place on the property. Second, separately affix a copy of that same notice on the outer door of the property, or some other conspicuous place on it.
Both steps matter, and neither substitutes for the other. Delivery to the borrower gives you direct, personal notice of what's happening. Affixing the notice at a conspicuous place on the property provides notice at the secured asset itself, in addition to delivery to the borrower. The statutory requirement should be followed independently of whether other interested parties are present. Courts treat the two as necessary parts of one requirement, not as alternatives where doing either one is enough.
Here's the practical thing worth checking the moment you're facing this: get a copy of exactly what was delivered to you, word for word, and where possible, look for documented proof of what was actually affixed on the property. A gap between what the bank says was delivered and what was actually put on your door is a real, checkable compliance question, not a technicality you'd have to imagine.
That covers what's supposed to happen at this stage. What comes right after it, the newspaper publication step, has its own strict deadline that's easy to miscalculate if you're counting from the wrong date.

Freed Expert Tip
Ask for proof the notice was actually affixed, a photograph, a witnessed record, not just the bank's word for it. This becomes important if you ever need to challenge the process.
Talk to FREED's TeamThe 7-Day Deadline: How It's Actually Calculated
Rule 8(2) requires the possession notice to be published as soon as possible, and no later than seven days from the date of taking possession, in two leading newspapers, including one vernacular newspaper having sufficient circulation in the locality.
Here's where the confusion usually starts. That 7-day window runs from the date possession is actually taken, meaning the date the notice was delivered and affixed under Rule 8(1). It does not run from the date of the original Section 13(2) demand notice sent months earlier. Those are two entirely different reference points, and mixing them up leads to a wrong deadline, one calculated from the wrong starting line.
Record the dates of delivery and affixation, and obtain the authorised officer’s possession records. A qualified lawyer can help determine the legally relevant date for calculating the publication deadline. . Count seven days forward from that specific date. That's the window within which newspaper publication is genuinely supposed to happen, and it's worth checking whether it actually did.

What the Law Says
Rule 8(2) requires the possession notice to be published in two leading newspapers, one in the vernacular language of the locality, within seven days of the date possession was actually taken, not from the date of any earlier demand notice.
Understand My RightsWhy You Don't Have to Wait for Physical Possession to Challenge This
A lot of borrowers assume they can only challenge a SARFAESI action once the bank has actually, physically taken over the property. That's not correct, and it's worth knowing this early rather than after you've already waited too long.
Courts have held that delivering a possession notice under Rule 8(1), together with affixing it on the property, is itself a recognised mode of "taking possession" under Section 13(4)(a). A full bench of the Allahabad High Court confirmed this directly: once possession is taken this way, Section 17 becomes available immediately. There's no requirement to wait for a later, actual physical takeover to happen first.
The practical takeaway is straightforward. If you've received a possession notice and had it affixed on your property, that alone is enough to trigger your right to file a Section 17 application before the DRT, provided you have genuine grounds to challenge the process. Don't assume you need anything further to happen before you can act.
What happens when a bank skips a step here isn't just theoretical either. There's a real case where getting this exact stage wrong cost the bank the entire enforcement action.

Received a possession notice and considering your options?
Talk to FREED about your timeline.
Check your optionsWhen Sloppy Compliance Gets the Whole Action Quashed
In a case before the DRAT Kolkata, the bank had admittedly not affixed the possession notice on the property at all. There was no proof the notice had been served on the borrowers either. And when it came to newspaper publication, the bank's claim amounted to, in the tribunal's own words, a vague statement without proof.
The tribunal didn't treat this as a minor slip to be overlooked. Relying on established precedent that this kind of failure vitiates the entire proceeding, the DRAT quashed both the possession notice and every action that had followed from it.
The lesson here is direct. This wasn't waived because the bank's underlying claim against the borrower was otherwise valid. A genuine failure to properly affix the notice, and a genuine failure to prove publication, was enough on its own to unravel the whole enforcement action up to that point. If you can show either of these failures in your own case, that's a substantive ground worth raising, not a minor point to mention in passing.
Think your notice wasn't properly affixed or published?
Get a free, honest read on your situation.
Get a Free AssessmentA Couple of Related Questions Worth Knowing
Does SARFAESI prevail over an ongoing arbitration proceeding on the same property? This is a genuinely complex, fact-specific area. The interaction between SARFAESI proceedings and pending civil or arbitral proceedings is fact-specific. The applicable statutory provisions, the nature of the dispute and the relevant judicial decisions should be reviewed before drawing conclusions about whether one proceeding affects the other. This isn't something a general answer can settle, it needs advice built around your actual proceeding.
Does SARFAESI apply to MSME loans covered under a credit guarantee scheme like CGTMSE? Being covered by a credit guarantee scheme doesn't automatically pull a loan out of SARFAESI's scope. The guarantee scheme is a separate arrangement between the lender and the guarantee fund. Coverage under a credit guarantee scheme does not, by itself, establish whether SARFAESI enforcement is available. Applicability depends on the loan structure, the security interest, statutory conditions and the relevant scheme terms. That said, how this interaction plays out in practice can matter for how the lender ultimately recovers, so specifics are worth checking case by case.
Neither of these questions has a tidy, universal answer, and this piece won't pretend otherwise. Both genuinely need advice built around your own facts before you rely on them.
What Are Your Options If You Also Have Unsecured Debt
FREED doesn't act on Rule 8(1) or Rule 8(2) compliance challenges, possession notice disputes, or Section 17 applications. Those need qualified legal representation, not a debt platform.
But if separate unsecured debt exists alongside a secured loan that's reached this stage, that's a genuinely different problem, and here the honest framing applies: settlement isn't something a borrower chooses out of preference. Settlement decisions depend on the borrower’s financial circumstances, repayment capacity, account status and the lender’s policies. Settlement may be considered in cases involving financial difficulty. If your personal loans or credit cards are still manageable even while a secured loan is going through this process, bringing them together through debt consolidation is usually the first thing worth exploring before settlement comes into the picture.
How FREED Helps
FREED doesn't handle secured loans or challenges to possession notice compliance. Those need qualified legal representation, especially given how time-sensitive a Section 17 filing can be once the clock starts running.
What FREED does help with is the unsecured debt that often sits alongside these situations, the personal loans, credit cards, and BNPL dues. Consolidation may combine eligible unsecured debts into one repayment arrangement and may reduce the monthly EMI, depending on the borrower’s eligibility and the applicable terms. Settlement works with your banks to bring that debt down if repaying in full genuinely isn't possible anymore.
Tips If You're Facing a Rule 8(1) Possession Notice
Get and keep a copy of exactly what was delivered to you. Where you can, document what was actually affixed on the property, a photo helps more than memory.
Calculate the 7-day publication window from the actual possession date, not from the earlier demand notice date, those are different starting points and mixing them up gives you the wrong deadline. Know that you can file a Section 17 application as soon as this stage is reached, you don't have to wait for physical possession later. And if you spot a genuine affixation or publication compliance failure, get qualified legal advice promptly, this is a time-sensitive window, not something to sit on.
Freed Expert Tip
Photograph the actual state of the property's door or entrance the moment you become aware of a possession notice. This can be useful evidence either way about whether proper affixation genuinely occurred.
Talk to FREED's TeamSources
Claim | Source |
Rule 8(1) requires delivery and affixation of possession notice, in Appendix IV format | Security Interest (Enforcement) Rules, 2002, Rule 8(1) |
Rule 8(2) 7-day publication deadline, counted from date of taking possession | Security Interest (Enforcement) Rules, 2002, Rule 8(2) |
Delivery/affixation under Rule 8(1)/(2) itself constitutes "taking possession," Section 17 available immediately | Full bench ruling, Allahabad High Court |
Possession notice and subsequent actions quashed over unproven affixation and publication | DRAT Kolkata ruling on non-compliance with Rule 8(1) and (2) |
Disclaimer
Rates, fees, tenures, and other loan-related information shown are indicative in nature and based on publicly available information and market inputs available at the time of publishing. The actual applicable interest rates, processing fees, eligibility criteria, loan amounts, repayment terms, and approval decisions are solely determined by the respective bank, NBFC, or financial institution based on the applicant’s individual profile, credit assessment, and prevailing internal policies.
FREED does not act as the lender and does not guarantee loan approval, final sanction terms, or accuracy of lender-specific policies that may be revised without prior notice. Financial institutions may modify their products, rates, and eligibility criteria from time to time at their sole discretion.
Users are advised to independently verify all applicable terms and conditions directly with the respective lender before making any financial decision or submitting an application. FREED shall not be held responsible for any discrepancy, rejection, revision, or decision taken by the lender in this regard.

Mohit Juneja
Mohit Juneja writes educational content at FREED on debt management, credit scores, loan repayment, and borrowing best practices. His content is shaped by expert insights and industry knowledge, helping readers better understand their financial options and make informed decisions.
mohit.juneja@freed.care

FREED is India's trusted loan management platform. Founded in 2020 and headquartered in Gurugram, FREED has counselled 20 lakh+ people on personal loans, credit cards, and app loans. FREED charges fees only on successful settlement, not upfront. FREED does not handle secured loans (home loans, car loans, gold loans).
Media Mentions