Six Reasons You Should Avoid FREED
6 Reasons to Avoid FREED" offers an unexpectedly candid look at our methods, the reasons we advocate for loan settlement or consolidation, and how we help you become debt-free.
Mohit Juneja
Reviewed by FREED India, Debt Resolution Specialists
 4.7/5
 ₹3,200Cr+
 20,000+
 20,00,000+4.7/5₹3,200Cr+20,000+20,00,000+
Key Takeaways

FREED sincerely hopes you won't require us twice. The sincere reasoning behind these six reasons to reconsider your decision is that we want you to be debt-free and remain so.
We don't want to be your last option. We encourage you to get in touch with us before, not after, your debt load worsens.
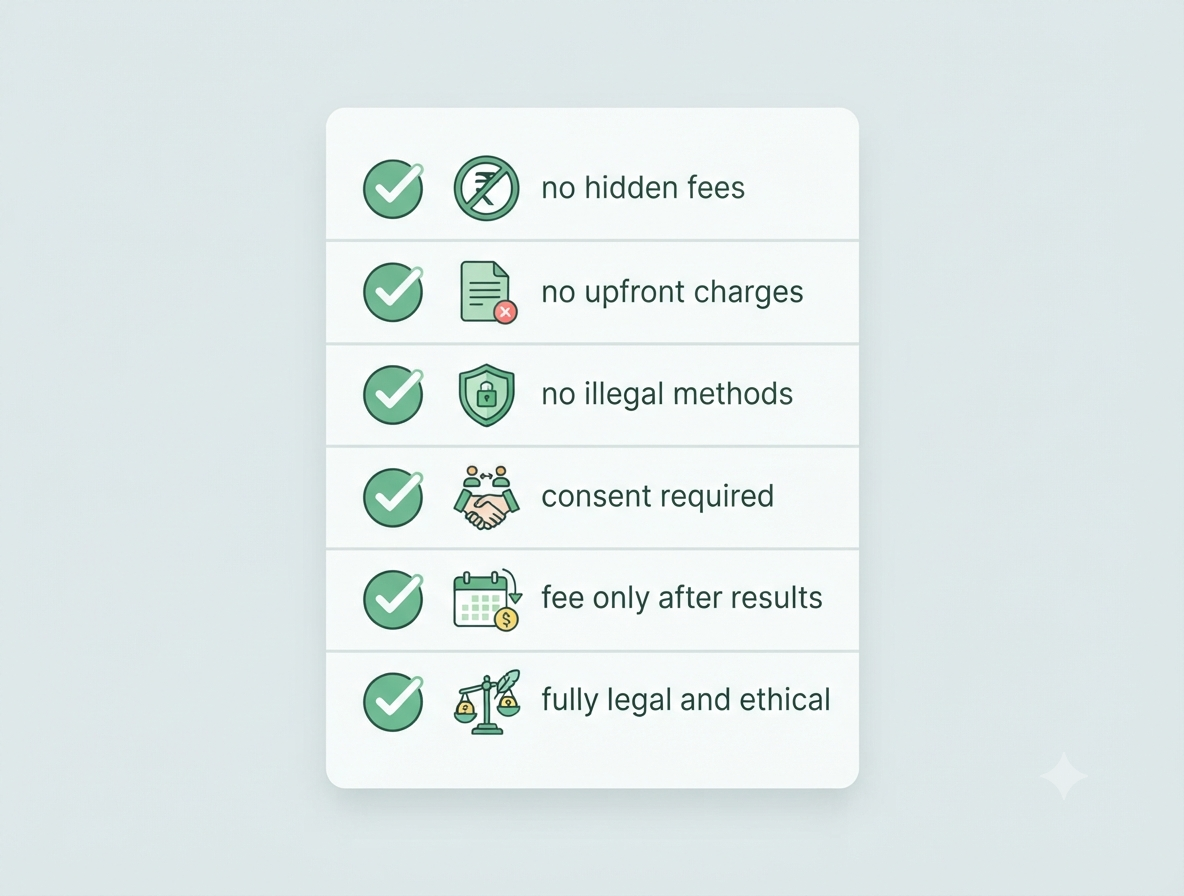
There are no additional costs. Before you make any commitments, everything regarding loan settlement and loan consolidation is thoroughly explained.
You only pay us when we get results; we don't charge a service fee until your debt is paid off.
We are willing to give you six reasons to stay away from FREED before we provide you one reason to join because FREED has always operated in a morally and legally responsible manner with complete transparency at every stage.
Why Are We Telling You to Avoid Us?
The majority of businesses simply tell you positive things about themselves. We're going to take a different approach.
We'll give you six reasons to really consider your options before selecting FREED.
We don't want to lose you. However, we think that the most knowledgeable clientele are the best. You'll make the best choice for yourself if you know exactly what FREED is and isn't.
We'll be here if you still want to chat to us after reading all six of the reasons.
Reason 1: We Don't Want Repeat Customers
Really, yes.
The majority of companies want devoted, recurring clients. Actively, FREED doesn't.
Our objective is to assist you in paying off your debt so you won't require our assistance ever again. Our goal is to assist you in correctly resolving your debt load and developing sound financial practices that will ensure that you never find yourself in this situation again.
The goal of FREED's program is to help you stay out of debt by providing continual education, financial discipline assistance, and budgeting support.
You won't need to call us again if we've done our work well
Therefore, FREED is not the service you're searching for if you want it to be a permanent part of your life.
However, we are the perfect match if you're looking for someone who will put in a lot of effort to become unnecessary.
Reason 2: We Don't Want to Be Your Last Resort
FREED is typically contacted after months of hardship. The debt has already increased significantly. Calls for collections have been ongoing for some time. The options are now more limited.
We do a good job of helping folks in that circumstance. However, we wish they had called earlier.
Because you have more options the earlier you get in touch, whether it's loan settlement or consolidation.
This is the ideal moment to speak with us if you're reading this and thinking, "My debt is a little difficult but not yet a crisis." We may be able to assist you completely avoid the crisis.
Don't wait for your monthly wage to reach 60% if your total EMIs exceed 40%. Give FREED a call right now.
Don't wait for three credit cards to get into problems if the balance on one is rising despite your minimum payments. Give FREED a call right now.
When everything is already on fire, FREED doesn't want to be the one to enter. We would prefer to be the ones who assisted you in identifying the smoke.

FREED Expert Tip
You are already in a debt danger zone if your total monthly EMIs, including credit card minimum dues, exceed 40% of your take-home pay. Avoid waiting for it to become the default. You have more possibilities the sooner you act.
Talk to a FREED Counsellor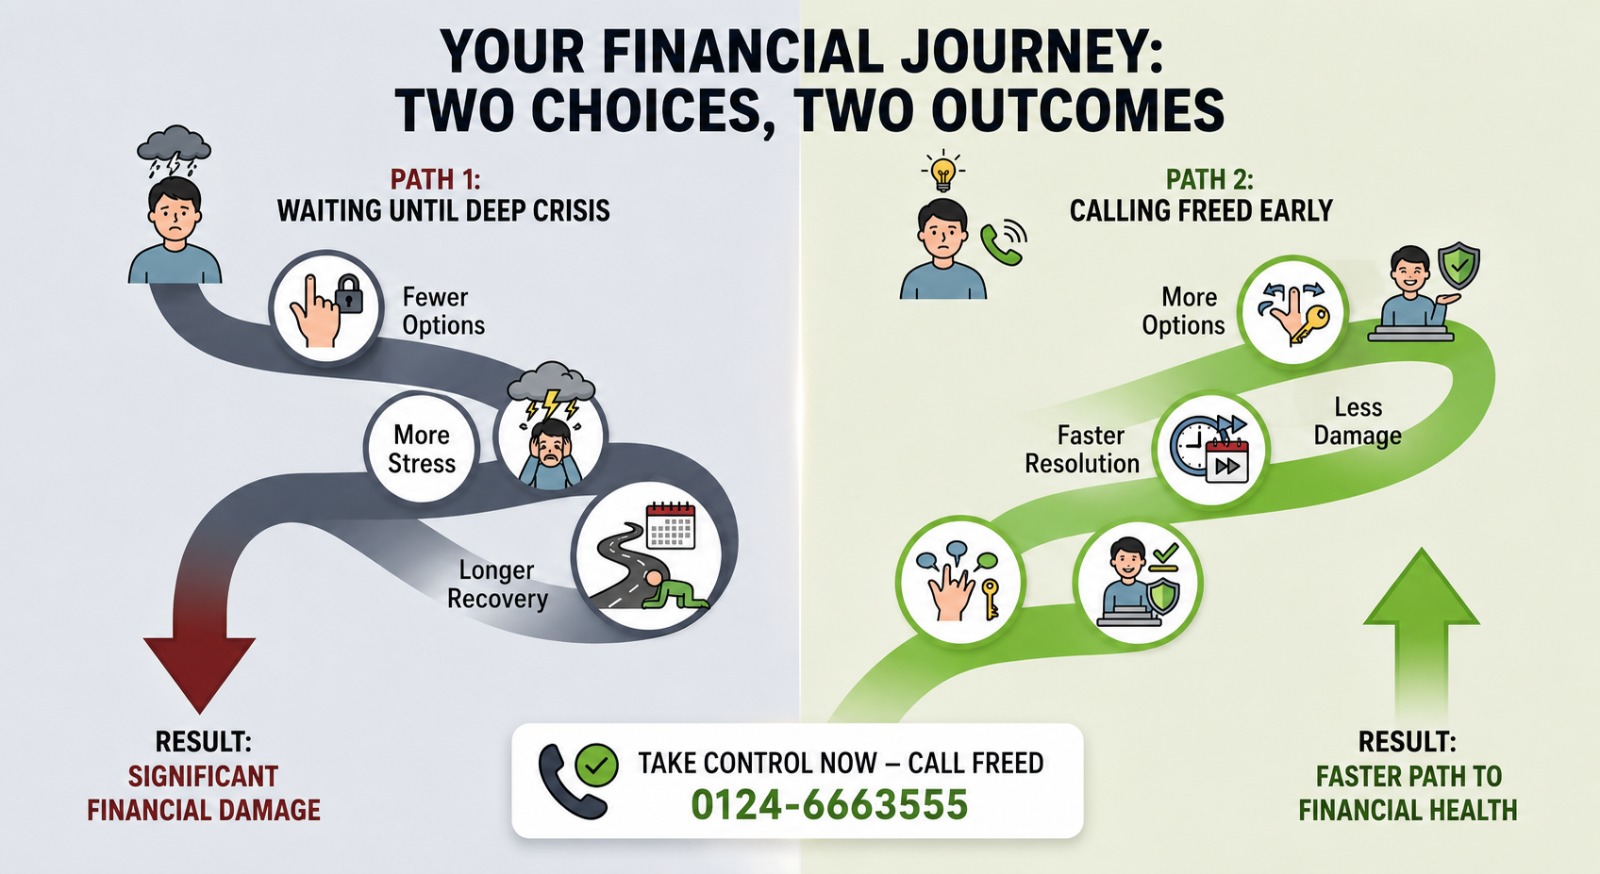
Reason 3: We Don't Charge Hidden Fees
This may seem apparent. However, it's important to be transparent in a market where a lot of financial services firms hide fees in fine print.
You pay for what you see when using FREED. Nothing more.
Before you sign up, we go over every expense:
Subscription Fee per Month (MSF). All program services, including your relationship manager, legal assistance, negotiation services, and FREED Shield protection, are covered by a nominal monthly charge. It is distinct from the money you save each month in your Special Purpose Account.
Fee for settlement. only when a debt has been satisfactorily closed and settled. Not earlier.
That's all. There is no startup cost. There are no "processing charges." No unexpected deductions.
Transparency has been the foundation of our reputation. Thousands of customers have come to us because someone they know attested to our integrity; many of them are from smaller cities where confidence is difficult to gain.
We plan to maintain that reputation. Therefore, FREED is not the place to look for hidden fees.
Reason 4: We Don't Take a Service Fee Before Settlement
In this regard, this is the most significant practical distinction between FREED and dishonest operators.
Before beginning any service, several purported "debt relief" firms demand a sizable payment up front. The money is collected by them. After then, they either do nothing at all or completely vanish.
Only when your debt has been satisfactorily resolved through loan settlement does FREED impose a settlement fee.
In other words, we only succeed when you succeed.
You don't have to pay a settlement fee if we don't pay off your debt. This keeps us incredibly driven to provide each customer with tangible outcomes.
Since your relationship manager, legal team, and FREED Shield are working for you right away, the Monthly Subscription Fee (MSF) does begin following enrollment. However, the primary charge on the agreed-upon sum is only due once the task is completed.
FREED is not the firm you're searching for if you want to be charged first and work second.
Reason 5: We Don't Let You Pay Your Full Debt Load
It sounds too good to be true. But that's precisely what we do.
Through negotiations with your lenders, FREED's Loan Settlement Program lowers the amount of your debt. The remaining amount is waived if you pay less than what you initially owed.
FREED typically negotiates a 56% decrease in client debt.
Accordingly, our clients often settle for about ₹88,000 if they owe ₹2,00,000. Negotiated away is the remaining ₹1,12,000.
This isn't a ruse. It is a legitimate settlement that you and your lender have agreed upon. Because a partial recovery is preferable to a protracted default that might yield no recovery, banks concur.
The skilled negotiators at FREED know exactly what banks are ready to accept, and they work hard to secure the most decrease for you.
Therefore, FREED will ensure that you don't have to pay every rupee that you owe.

What the Law Says
In India, debt settlement is entirely legal. Indian contract law permits banks and borrowers to reach a mutually agreeable settlement amount. According to RBI requirements, before any payment is made, the borrower must have written confirmation of all settlement terms. Your legal interests are always safeguarded because FREED makes sure that every settlement agreement is examined and recorded before you pay a single rupee.
Read your full rights as a borrower in IndiaReason 6: We Don't Do Anything Illegal or Unethical - Ever
FREED has worked by a single, unambiguous norm since 2021: transparency, ethics, and legality. Always.
This implies:
If settlement isn't truly the best choice for you, we never suggest it. We'll let you know if loan restructuring or consolidation works better for you.
We never engage in negotiations without your awareness and approval. Your consent is needed for each stage. Before a rupee is paid, you are informed of every settlement offer.
We never promise something we can't fulfill. We don't tell you what you want to hear; we tell you what is actually possible.
We never give false information about what we do. We are transparent about our fees. We have a defined process. We are obviously limited.
We never condone or participate in harassment. Indeed, we actively shield you from harassment by recovery agencies with FREED Shield.
Empathy, passion, and service are more than just words on a wall. They are evident in our negotiators' interactions with banks, our counselors' interactions with clients, and our honest handling of challenging circumstances.
If you're searching for a business that takes short cuts, makes inflated claims, or charges for outcomes it is unable to provide, FREED is not the one.
So, Should You Avoid FREED?
Let's be honest.
Avoid FREED if you want a business that will accept your money up front and do nothing. Avoid FREED if you desire a business that employs unethical or unlawful practices. Steer clear of FREED if you want a business that costs you unexpected and hidden fees. Steer clear of FREED if you want a firm that will force you to pay off all of your debt without attempting to lower it. Steer clear of FREED if you want a business that wants you to return again and time again.
However, if you're looking for a business that
Only when you win does it work
tells you the whole truth right away.
negotiates a loan settlement or loan consolidation to reduce your debt as much as possible.
keeps you safe from harassment
is completely morally, legally, and openly
sincere desire for you to remain debt-free
If so, FREED is precisely what you're searching for.
A open discussion is the first step. No costs. No dedication. Just being clear.
Are You in a Loan Trap? Quick Check
Move the slider to your total EMIs as a % of monthly salary. See your debt stress level instantly.
EMIs as % of Monthly Salary
Mohit Juneja
Mohit Juneja writes educational content at FREED on debt management, credit scores, loan repayment, and borrowing best practices. His content is shaped by expert insights and industry knowledge, helping readers better understand their financial options and make informed decisions.
mohit.juneja@freed.care

FREED is India's trusted loan management platform. Founded in 2020 and headquartered in Gurugram, FREED has counselled 20 lakh+ people on personal loans, credit cards, and app loans. FREED charges fees only on successful settlement, not upfront. FREED does not handle secured loans (home loans, car loans, gold loans).
Media Mentions