Budgeting: The Basics and a Little More
Most people think budgeting means cutting down on everything fun. It doesn't. It just means telling your money where to go - before it disappears on its own.
Mohit Juneja
Reviewed by FREED India, Debt Resolution Specialists
 4.7/5
 ₹3,200Cr+
 20,000+
 20,00,000+4.7/5₹3,200Cr+20,000+20,00,000+
Key Takeaways

A budget is simply a plan for your money - nothing more, nothing less.
Most people fail at budgeting because they don't track what they actually spend.
The goal is not to spend zero - it's to spend with intention.
If EMIs take up more than 40–50% of your income, you need debt help, not just a budget.
Small, consistent money habits beat big, complicated financial plans every time.
What Is a Budget, Really?
Let's keep this simple.
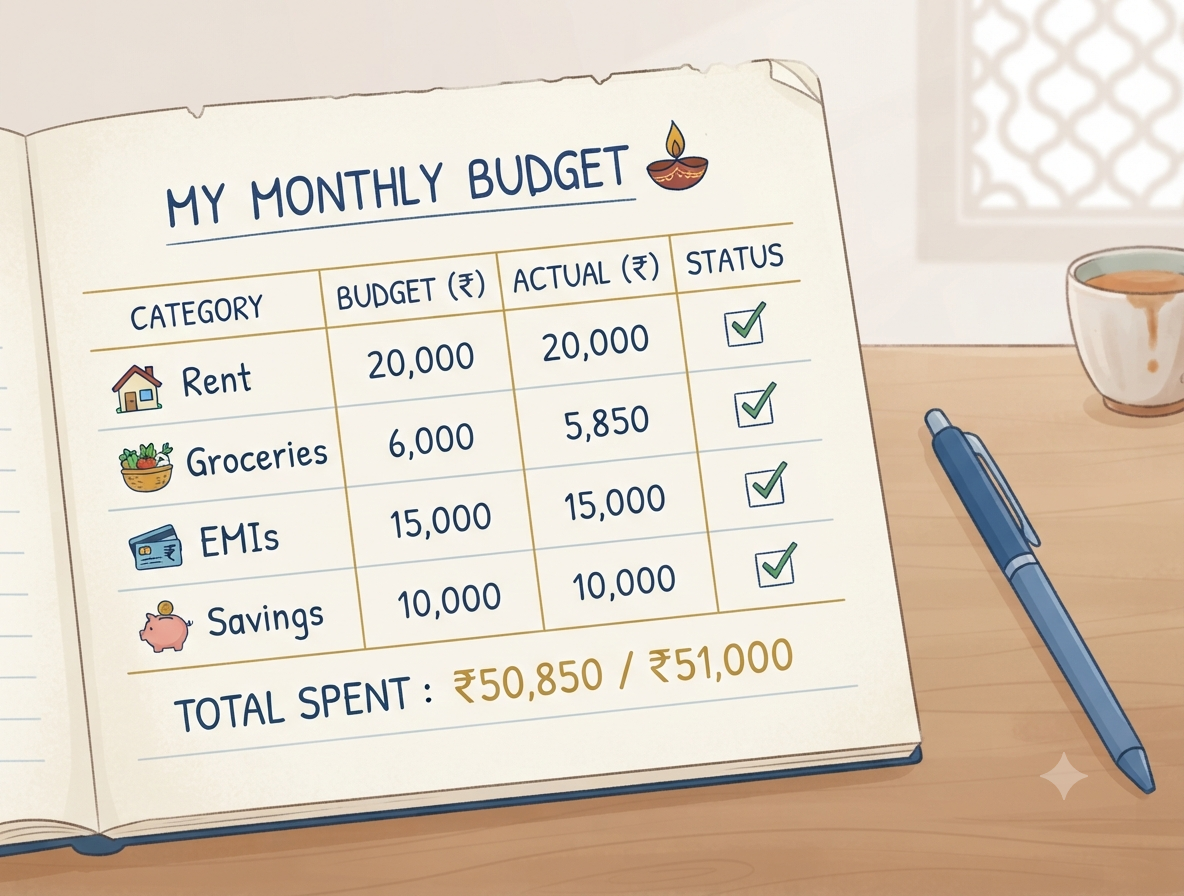
A budget is a list. Income on one side. Expenses on the other.
That's it.
You're not giving up chai. You're not counting every single rupee forever. You're just making sure you know where your money is going before it goes there.
Most people don't have a budget. They have a rough feeling about money. That feeling is usually wrong and by the 20th of the month, it becomes panic.
A budget replaces the feeling with facts.
Step 1: Know What Comes In
Before you plan anything, you need one number: your monthly take-home income.
Not your CTC. Not your gross salary. What actually lands in your account every month, after tax and PF deductions.
If your income is irregular freelance, business, daily wages use the average of your last 3 months. Or use the lowest month as your base. Better to be safe.
Write this number down. This is your starting point.
Step 2: Know What Goes Out
Now list everything you spend money on in a month.
Divide it into two types:
Fixed expenses are the same every month. Rent, EMIs, school fees, insurance premiums, subscriptions.
Variable expenses change month to month. Groceries, transport, dining out, clothes, medicines, entertainment.
Don't guess. Look at your last month's bank statement and UPI history. This is where most people get a shock.
Write every number down. Even the small ones Swiggy, auto, recharge. They add up faster than you think.
Step 3: Find the Gap
Now subtract your total expenses from your income.
Income – Expenses = Your Gap
Three things can happen here:
Positive gap - you have money left over. Good. This goes into savings or debt repayment.
Zero gap - every rupee is accounted for. Okay. But there's no room for surprises. You need to find cuts.
Negative gap - you're spending more than you earn. This is a serious problem and it's more common than people admit.
If your gap is negative, don't panic. But don't ignore it either. Something has to change either income goes up, or expenses come down.
Step 4: Make a Plan That Actually Works
Here's a simple structure that works for most Indian households:
Category | Ideal % of Income |
Needs (rent, groceries, bills, EMIs) | 50% |
Wants (dining, shopping, entertainment) | 20–30% |
Savings & investments | 20% |
This is the 50-30-20 framework. It's a guide, not a law.
If your EMIs alone are 40–50% of income, the "needs" category is already over budget before food and rent. That's a debt problem not a budgeting problem. We'll come to that.
For everyone else: start with this split. Adjust based on your real expenses. The goal is direction, not perfection.

What the Law Says:
Under RBI guidelines, banks must clearly disclose the total interest cost of any loan before you sign. You have the legal right to a loan amortisation schedule - a month-by-month breakdown of exactly what you'll pay. Always ask for this before taking any EMI. If a lender refuses, you can escalate to the RBI Banking Ombudsman.
Know your rights as a borrower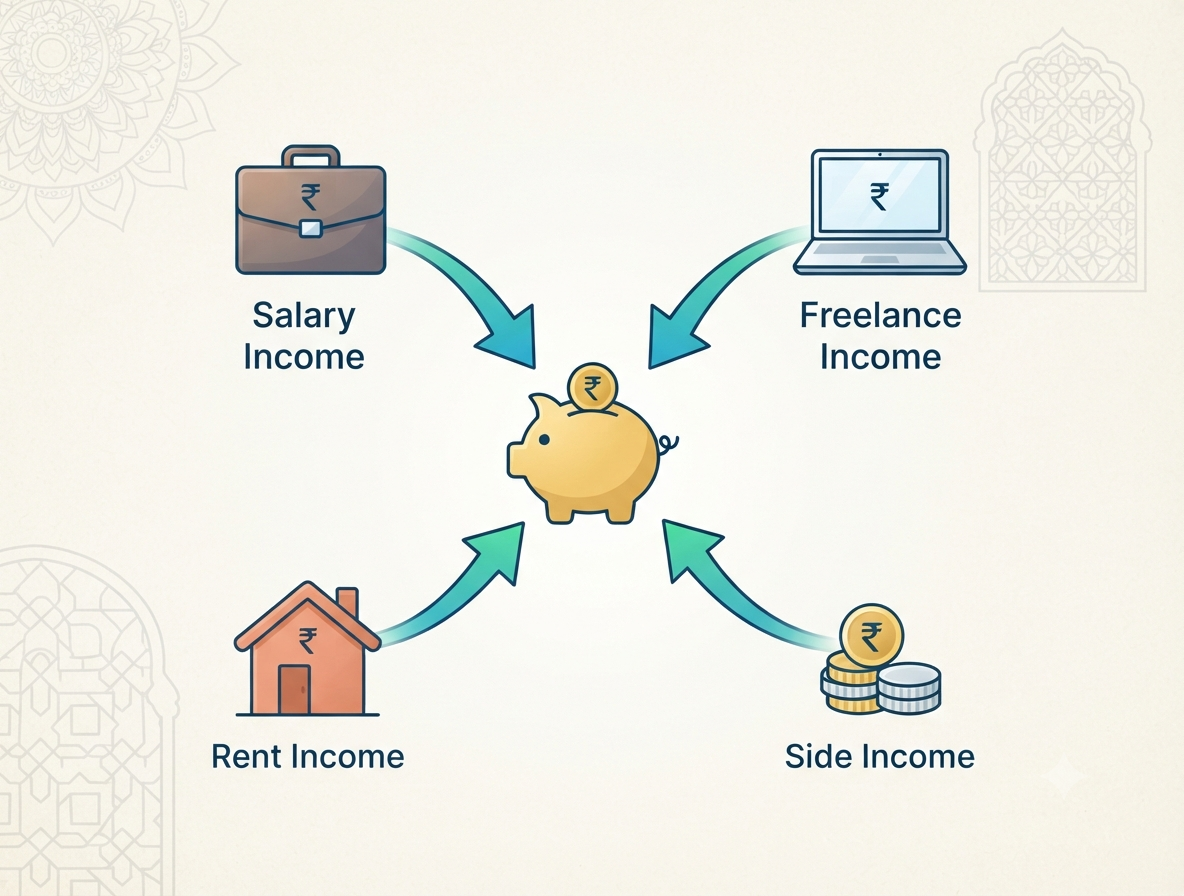

FREED Expert Tip
Most people underestimate variable expenses by 20–30%. When in doubt, round up - not down. An honest budget always beats an optimistic one.
Check My Credit InsightsThe Little More - Beyond Basic Budgeting
Once you have the basics down, here's what separates people who just budget from people who actually build wealth.
1. Build your emergency fund first. Before investments, before anything - save 3 months of total expenses in a separate account. Don't touch it unless there's a real emergency. This is the fund that stops debt from happening.
2. Review your budget every month. Life changes. A budget that worked in January may not work in March. Spend 15 minutes at the end of each month comparing what you planned vs. what actually happened. Adjust accordingly.
3. Watch out for lifestyle creep. When income goes up, expenses tend to go up too - silently. A new phone. A bigger flat. More eating out. This is lifestyle creep. It's not wrong to spend more as you earn more - but do it intentionally, not automatically.
4. Automate what you can. Set up auto-transfers for savings. Auto-pay for EMIs. The less willpower budgeting requires, the more sustainable it becomes.
5. Have one "guilt-free" spending category. If your budget is 100% discipline with zero joy, you'll quit. Allow yourself one category dining, movies, travel where you spend without guilt, within a fixed limit. This keeps budgeting human.
When EMIs Are the Real Budget Problem
Sometimes the budget is fine and the EMIs are the issue. If your total EMIs take more than 50% of your take-home salary, no spending plan will fix that on its own. Before you take on any new credit, check your EMI Score to see where you stand.
If several loans are the cause, our guide to debt consolidation and its trade-offs explains when combining them helps. If you are already behind, read about the debt relief options in India and how each one affects your credit.
When Debt Makes Budgeting Impossible
There's a version of this problem that a budget can't fix alone.
Drag
If your EMIs, credit cards, personal loans, BNPL are eating 50% or more of your monthly income, there's no budget framework in the world that will give you breathing room.
Drag
In these situations, the problem isn't how you're spending. The problem is how much you owe.
Drag
FREED helps people in exactly this situation. We look at your full debt picture and find a way to reduce your monthly EMI burden - through consolidation or resolution. Once your debt load drops to a manageable level, budgeting becomes possible. Even easy. Your EMI Score tells you, on a 0 to 100 scale, whether your current EMIs leave room for a new one.
Drag
Over 10,000 Indians have used FREED to get to that point. The first step is a free conversation.
Are You in a Loan Trap? Quick Check
Move the slider to your total EMIs as a % of monthly salary. See your debt stress level instantly.
EMIs as % of Monthly Salary
More Guides on Budgeting and Money Planning
These guides go deeper into saving, spending and planning around EMIs.
- 6 Financial Tips For Millenials
- 6 Practical Ways to Control Overspending Right Now
- 7 Money Management Tips for a Stronger Financial Future
- A New Year, A New Financial You: Where to Start
- Avoid a Personal Financial Crisis: The Smarter Way
- BNPL: Buy Now Pay Later: The Modern Credit Boon or Curse?
- Budgeting Basics : Finding the Right Approach for You
- Budgeting Mantras for Millennials
- Budgeting Tips for Better Financial Goals
- Building an Emergency Fund: Financial Security on Any Budget
- Can Your Spending Habits Put You In Trouble? Know More!
- Credit Advice vs Debit Advice: Meaning, Format & Example
- Emergency Fund: A Plan to Tackle Life's Uncertainty
- Explaining Net Worth: How to Calculate It?
- Extra Savings? Here is what to do with them!
- Festive Season and Overspending: Not This Time
- Financial Discipline: The First Step Towards a Secure Financial Future
- Financial Freedom: Here's Everything You Need to Know
- Financial Health: Importance and Ways to Improve it
- Financial Literacy: Why Is It Important and How to Improve
- Financial mistakes you should avoid: Know and Grow
- Financial Planning Tips for Women: Build Freedom on Your Own Terms
- Financial Security: Take the Step Toward Financial Independence
- Habits of a Healthy Borrower
- Highest Spending Limit on Debit & Prepaid Cards
- How and Why to Reduce Expenses in Debt
- How Long Do You Think You Can Manage Paycheck to Paycheck?
- How to Adjust Your Monthly Budget When Expenses Change
- How to Manage Your Finances During a Prolonged or Recurring Crisis
- How to Manage Your Finances During Financial Hardship
- Impulse Buying and its Impact on Financial Security
- Is It Time to Marie Kondo Your Finances?
- Learn How to Get Out of the Paycheck-to-Paycheck Cycle
- Money Management: How Tough Is It?
- Not Sure How Much to Save Every Month? Here It Is
- Overspending? Here Is How to Control It
- Passive Income: Leveraging Side and Investment Earnings for Stability
- Personal Finance Habits to Build for a Debt-Free Life
- Quick Ways to Save Money: Even with a Low Income
- SMART Financial Goal Setting for Short- & Long-Term Milestones
- Smart Financial Planning Tips for Salaried Professionals
- Spend Smart- Ways To Control Overspending This Diwali
- Stick To Your Budget: Budgeting Made Easy For You!
- The 50-30-20 Budget Rule: The Simplest Way to Take Control of Your Money
- The Do’s and Don’ts of Personal Finance: What Actually Works
- The Importance Of An Emergency Fund
- The Psychology of Overspending
- The Real Difference Between Savings and Investments
- The Urgent Need for Better Financial Planning
- Top 12 Financial Mistakes Business Owners Often Make
- Understanding Cash Flow Analysis & Why is it important?
- Understanding the Basics of Financial Planning
- Understanding Wealth Management: Everything You Should Know
- What Is a Daily Spending Limit? Meaning Explained
- What Is BNPL and How Does It Work?
- What Is Cap Credit? Meaning Explained

Mohit Juneja
Mohit Juneja writes educational content at FREED on debt management, credit scores, loan repayment, and borrowing best practices. His content is shaped by expert insights and industry knowledge, helping readers better understand their financial options and make informed decisions.
mohit.juneja@freed.care

FREED is India's trusted loan management platform. Founded in 2020 and headquartered in Gurugram, FREED has counselled 20 lakh+ people on personal loans, credit cards, and app loans. FREED charges fees only on successful settlement, not upfront. FREED does not handle secured loans (home loans, car loans, gold loans).
Media Mentions