A New Year, A New Financial You - Where to Start
Make this new financial year different - set one financial goal, do a financial review, and turn resolutions into real action.
Mohit Juneja
Reviewed by FREED India, Debt Resolution Specialists
 4.7/5
 ₹3,200Cr+
 20,000+
 20,00,000+4.7/5₹3,200Cr+20,000+20,00,000+
Key Takeaways

The majority of financial resolutions—saving more, reducing expenses, and paying off debt—fail because they are unclear. One clear monthly action linked to a single, verifiable financial goal is what works.
A thorough financial analysis of the previous year, including revenue received, total expenses incurred, debt accrued, and savings accumulated, provides you with factual information for planning rather than hopeful projections.
Before the initial motivation wanes, the habit is established by automating saves on the opening day of a new fiscal year.
The one thing that will most likely improve your financial status this year is to specifically address any unpaid debt from the previous year.
Thousands of Indians have benefited from FREED by using the beginning of a new year as a true turning point rather than merely a resolution.
Why Financial Resolutions Fail - And How This Year Will Be Different
The pattern is unmistakable. December is a time for introspection. January is a month of resolve. The same old routines return in February.
Financial resolutions nearly always fail for the same reason: they are expressed as directions rather than destinations.
Increasing savings is not a goal. The objective is to start saving Rs 2,000 a month into a different account on January 1st.
Reducing spending is not a goal. One goal is to cook at home on weekdays in order to cut monthly food delivery expenses from Rs 4,000 to Rs 2,000.
Paying off debt is not an objective. My objective is to pay Rs 5,000 more than the minimum amount owed on my HDFC credit card each month until it is zero.
Specificity makes a difference. When one's willpower weakens, hazy goals fade away. Because they only need to be decided upon once before being carried out, specific plans with tangible actions endure.
With the aid of this guide, you may transform your financial intentions into realistic financial goals for the upcoming fiscal year.
Step 1: Do a Complete Financial Review of the Past Year
In advance of creating any plans for this year, make sure you fully comprehend what transpired the previous year.
Calculate:
total earnings during the last 12 months. Total amount spent, including on shopping, entertainment, transportation, food, rent, and other expenses. Net change in debt: Is the total amount you owe now higher or lower than it was a year ago? Net change in savings: did savings increase, decrease, or remain unchanged
Regardless of how it felt, these four figures give you the truth about your fiscal year. Even though they believe they were being cautious, many consumers are shocked to see that their savings did not increase at all. Many find that their debt has increased without them being able to completely register it.
Step 2: Set One Specific Financial Goal for This Quarter
Not for the entire year. For January through March of this quarter.
one monetary objective. particular. quantifiable. with a distinct monthly action.
For instance:
Save Rs 5,000 every month beginning on January 1st to accumulate an emergency fund of Rs 15,000 by March 31st.
Instead of paying the existing minimum of Rs 3,000 per month, spend Rs 8,000 per month to pay off the credit card with the smallest outstanding balance by March.
Reduce monthly food delivery orders from 15 to 6 and cancel three subscriptions to cut monthly expenses by Rs 3,000.
One objective. A quarter. Just one action. Reach it, rejoice, and schedule the next one for April or June.
This strategy is effective because it is doable rather than overwhelming and because short deadlines foster accountability that annual goals do not.
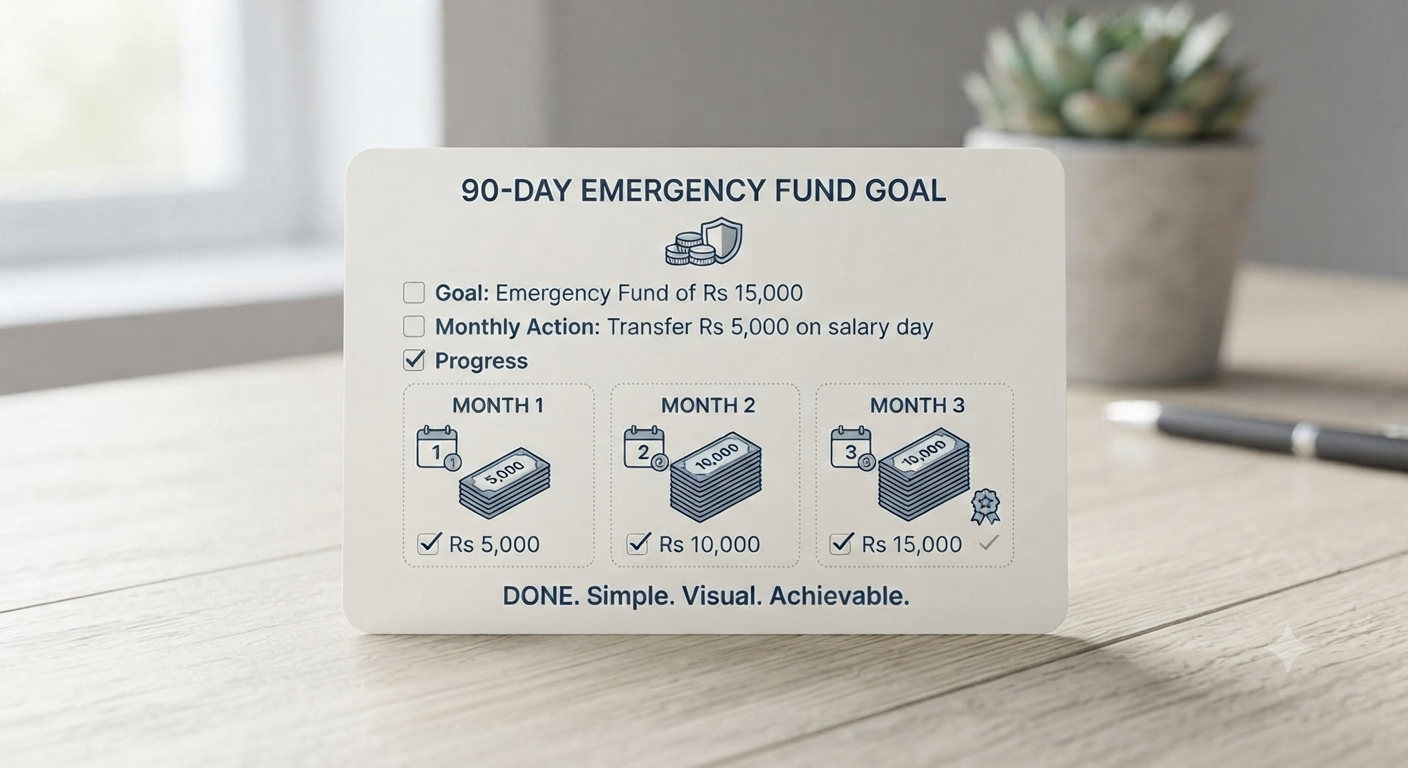
Step 3: Automate Your Savings on Day One
Set up the automatic transfer now, regardless of your savings goal. Not the following month. Not until the paycheck comes in. Right now.
The best financial system you can implement at the beginning of a new financial year is a standing instruction from your primary account to a different savings account that is activated on the day your salary comes.
Because it takes the decision out of the equation, this works. Before you can see it and spend it, the money moves. You survive on what's left. You make adjustments. The savings accumulate.
There is hardly ever anything left if you wait until the end of the month to salvage what's left.

FREED Expert Tip
For your financial objectives, open a savings account at a separate bank than your primary account. Make it a little difficult to access: don't carry an ATM card in your wallet, and don't set up online banking for rapid transfers. There is value in this friction. It implies that gaining access to the savings needs a deliberate choice as opposed to an instinct. When they do this, the majority of people discover that their savings account balance increases far more quickly than when they keep their savings and spending in the same account.
Check My Financial Health ScoreStep 4: Address the Debt That Has Been Ignored
The majority of people bring debt from the previous year into the new year with only a hazy plan to pay it off. Then February comes. March comes next. Additionally, the debt remains, albeit somewhat increased as a result of interest.
This month, decide on a specific course of action for each outstanding debt:
Can I use an aggressive payment plan to pay this off in six months? If so, make the plan and automate it.
Is it necessary to combine several loans into a single, lower EMI in order to make repayment feasible? If so, speak with FREED.
Has this debt grown to the point that I truly can't pay it back in full? If so, FREED can assist you in negotiating a settlement, which is a valid choice.
It's not necessary to make the choice by yourself. In just one call, FREED's free consultation explains the practical solutions for your particular situation.

What the Law Says
According to RBI regulations, you must be notified in writing of any changes to your loan terms, including interest rate, EMI amount, and tenure, before they become effective. Your rights have been violated if your bank has altered the interest rate, EMI, or other terms of your loan without giving you written notice beforehand. Examine your loan statements thoroughly at the beginning of each year to look for any modifications that were made without proper notice. You have the right to contest any unauthorized modifications with the bank and, if the issue is not resolved, to take it to the RBI Banking Advocate.
Talk to a FREED Expert - It's FreeStep 5: Build One New Financial Habit - Not Five
At the beginning of a new financial year, there is a temptation to make all the changes at once. Begin meal planning, budgeting, saving, investing, and keeping track of your spending on January 1st.
This hardly ever works. When you attempt to develop five new habits at once, none of them endure.
For this quarter, pick one new financial habit:
For ninety days, keep track of every expense in a notepad or an app. Cook at home every day of the week, Monday through Thursday. Every Sunday nite, check your bank statement. Set up auto-debit now and pay all credit card bills in full before the due date.
Just one habit. 90 days. Add the following one once it starts to happen automatically.
One well-established new habit is worth more than five that are started at the same time and abandoned in a matter of weeks, according to research on habit formation. This is the true basis for making a new fiscal year truly different from the previous one.
Are You in a Loan Trap? Quick Check
Move the slider to your total EMIs as a % of monthly salary. See your debt stress level instantly.
EMIs as % of Monthly Salary

Mohit Juneja
Mohit Juneja writes educational content at FREED on debt management, credit scores, loan repayment, and borrowing best practices. His content is shaped by expert insights and industry knowledge, helping readers better understand their financial options and make informed decisions.
mohit.juneja@freed.care

FREED is India's trusted loan management platform. Founded in 2020 and headquartered in Gurugram, FREED has counselled 20 lakh+ people on personal loans, credit cards, and app loans. FREED charges fees only on successful settlement, not upfront. FREED does not handle secured loans (home loans, car loans, gold loans).
Media Mentions